Strategy vault / Trend following
High Frequency Price Volume Trend Following with Volume Analysis Adaptive Strategy
This strategy is an automated trading system based on a 5-minute timeframe, combining moving average trend following and volume analysis methods. The strategy uses a 50-period Simple Moving Average (SMA) to determine…
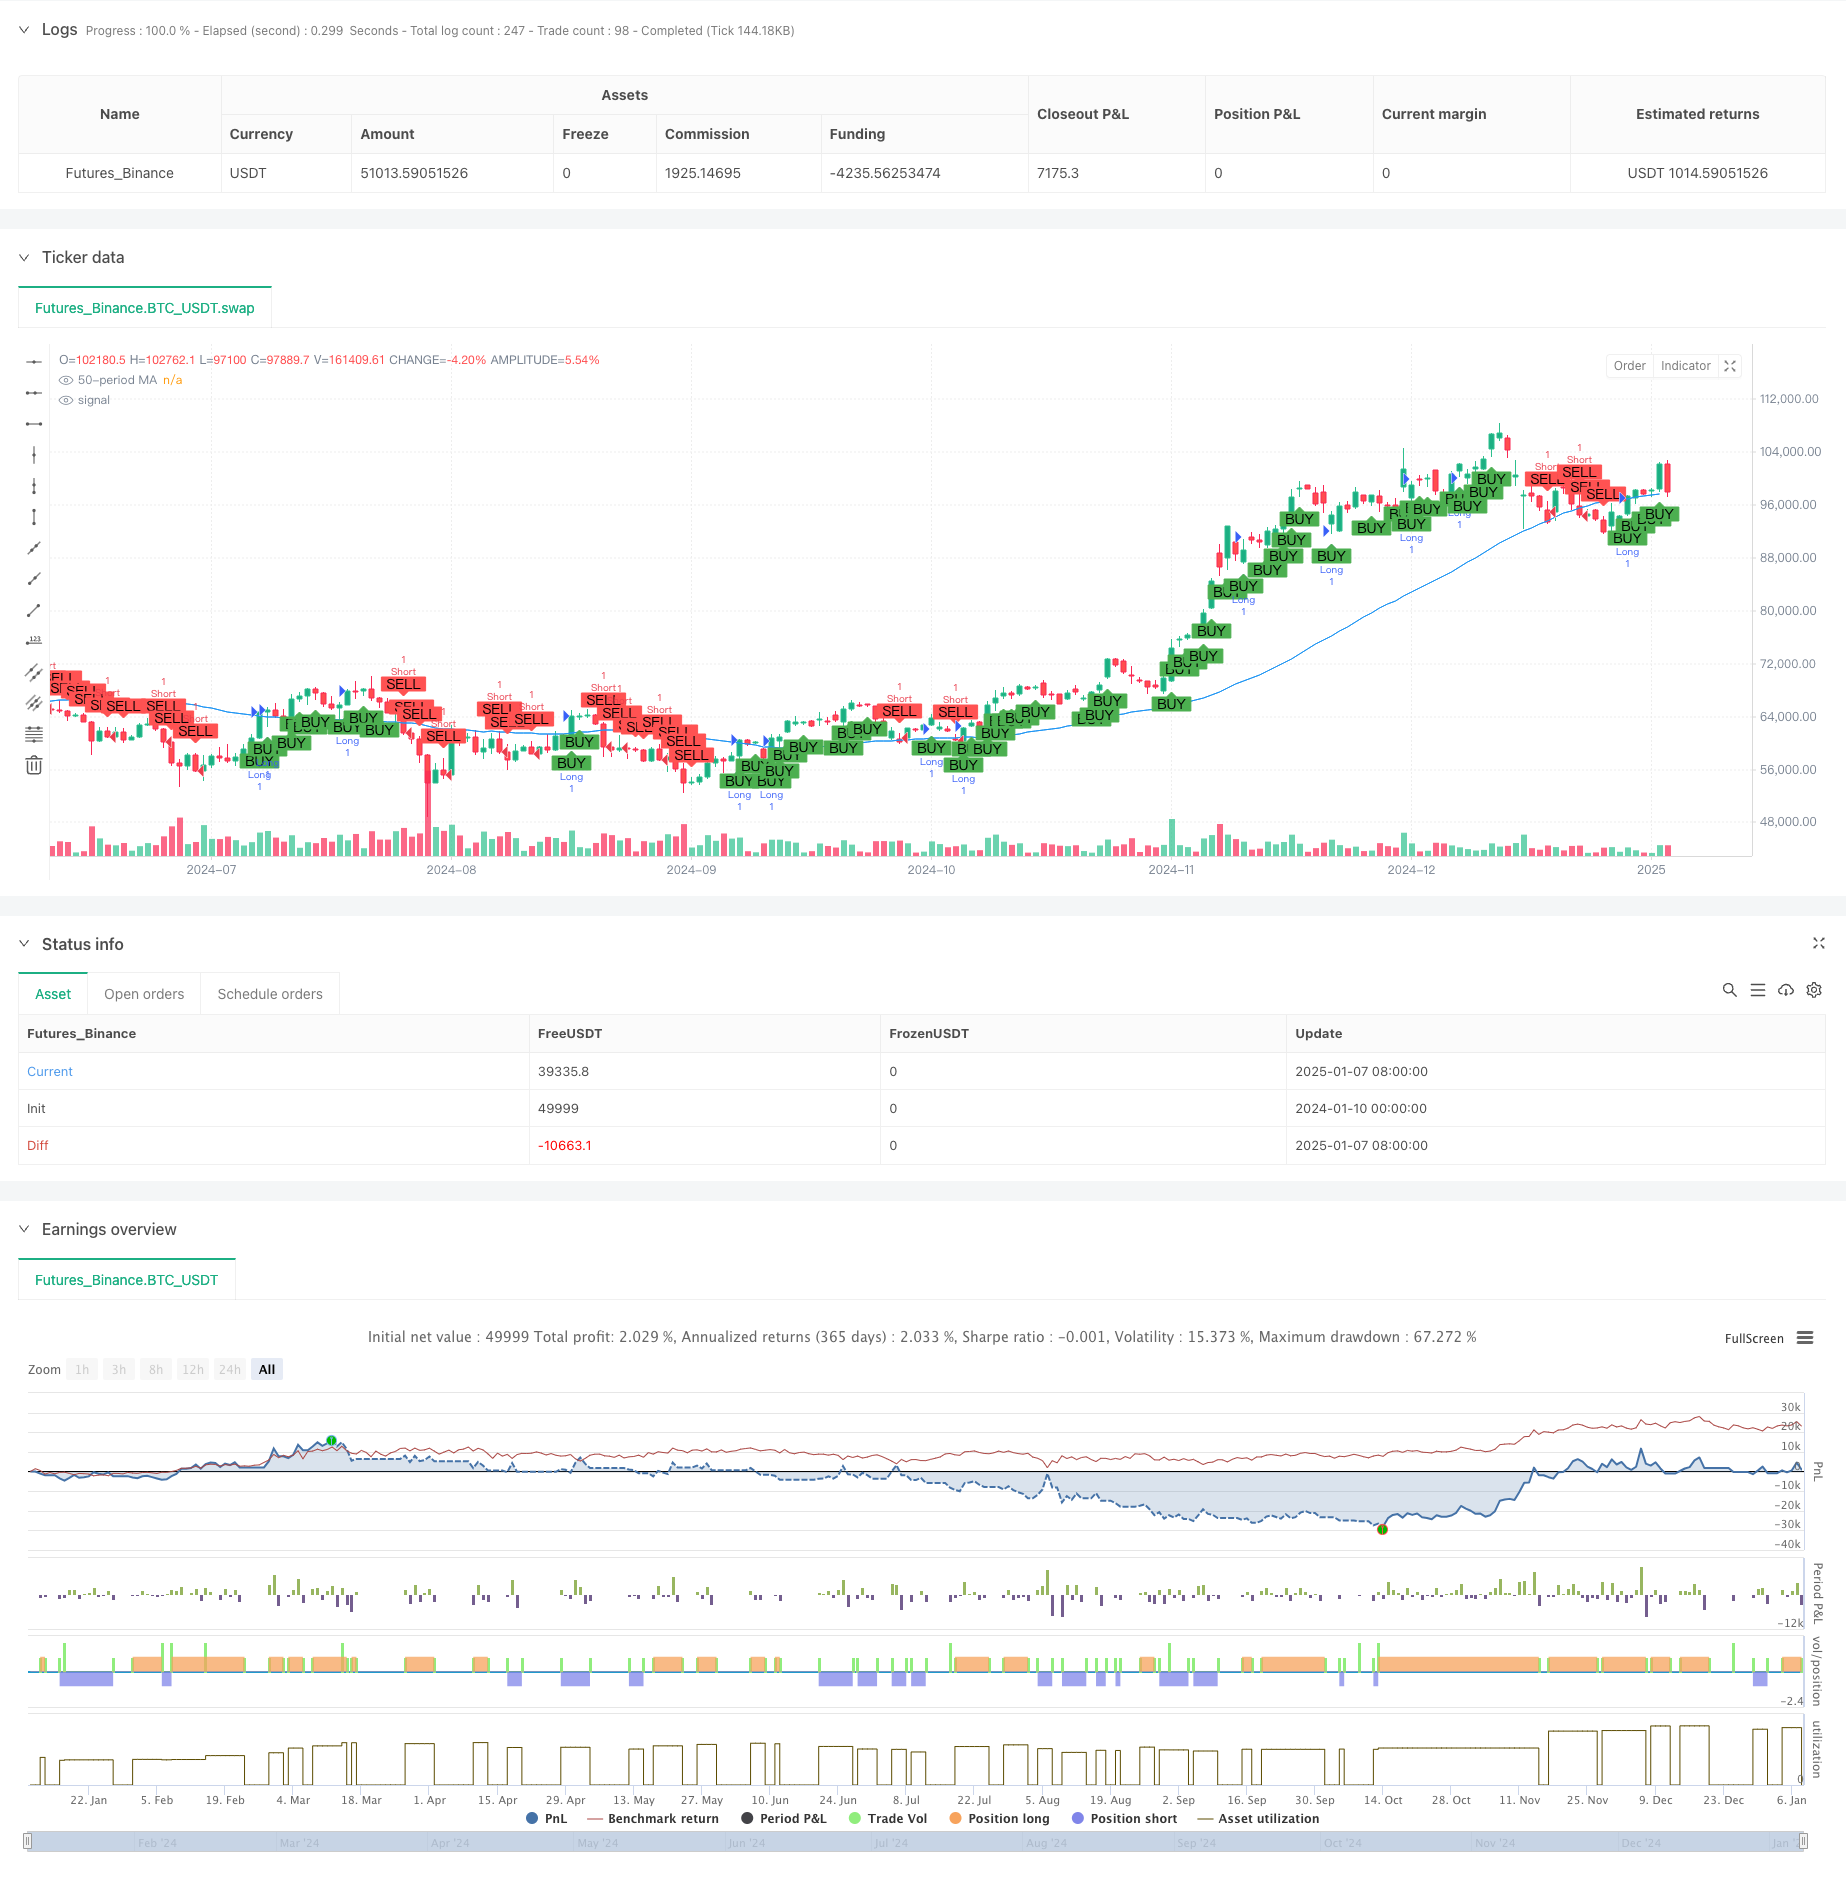
Overview
This strategy is an automated trading system based on a 5-minute timeframe, combining moving average trend following and volume analysis methods. The strategy uses a 50-period Simple Moving Average (SMA) to determine market trends while incorporating volume analysis to validate trading signals. The system implements fixed stop-loss and take-profit targets for fully automated trading.
Strategy Principles
The core logic includes the following key components:
- Trend Identification: Uses 50-period SMA to determine market direction, considering uptrend when close is above MA and downtrend when below. Also confirms trends using price movement over the last 30 minutes (6 candles).
- Volume Analysis: Calculates buy and sell volumes based on price movement, distributing volume within each candle according to closing price position.
- Signal Generation: Generates long signals when buy volume exceeds sell volume in uptrends; generates short signals when sell volume exceeds buy volume in downtrends.
- Risk Management: Implements 3% stop-loss and 29% take-profit targets to manage risk-reward ratio for each trade.
Strategy Advantages
- Multi-dimensional Trend Confirmation: Combines moving average and short-term price movement for improved trend accuracy.
- Volume Validation: Incorporates volume analysis as a signal filter to avoid false breakouts in low-volume environments.
- Comprehensive Risk Management: Sets clear stop-loss and take-profit targets for effective trade risk control.
- Strong Adaptability: Strategy automatically adjusts trading direction based on market conditions.
Strategy Risks
- Choppy Market Risk: May generate frequent false breakout signals in range-bound markets, leading to consecutive losses.
- Slippage Risk: High-frequency trading may face significant slippage, affecting execution quality.
- Parameter Sensitivity: Strategy performance is sensitive to moving average period and volume calculation period parameters.
- Market Environment Dependency: Performs well in trending markets but may experience drawdowns during trend transitions.
Strategy Optimization Directions
- Dynamic Parameter Optimization: Introduce adaptive parameter mechanisms to adjust MA and volume calculation periods based on market volatility.
- Market Environment Filtering: Add volatility or trend strength indicators to automatically stop trading in unsuitable market conditions.
- Improved Stop-Loss Mechanism: Implement dynamic stop-loss, such as trailing stops or ATR-based stops, for more flexible risk control.
- Enhanced Signal Generation: Consider incorporating additional technical indicators for cross-validation to improve signal reliability.
Summary
This strategy combines trend following and volume analysis to create a comprehensive high-frequency trading system. Its main strengths lie in multi-dimensional signal confirmation and robust risk control. While inherent risks exist, the proposed optimization directions can further enhance strategy stability and adaptability. The strategy is particularly suitable for trending market environments and can achieve stable trading results through proper parameter optimization and risk management.
Source Pine Script
/*backtest
start: 2024-01-10 00:00:00
end: 2025-01-08 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Jerryorange

//@version=6
//@version=6
strategy("Autonomous 5-Minute Robot", overlay=true, fill_orders_on_standard_ohlc=true)

// --- Inputs ---
maLength = input.int(50, title="Trend MA Length")  // Moving average length for trend detection
volumeLength = input.int(10, title="Volume Length") // Length for volume analysis
stopLossPercent = input.float(3, title="Stop Loss (%)")  // 3% stop loss
takeProfitPercent = input.float(29, title="Take Profit (%)")  // 29% take profit

// --- Market Trend Detection ---
ma = ta.sma(close, maLength)  // Simple moving average for trend direction
isBullish = close > ma  // Market is bullish if the close is above the moving average
isBearish = close < ma  // Market is bearish if the close is below the moving average

// --- Volume Analysis ---
buyVolume = (high != low) ? volume * (close - low) / (high - low) : 0
sellVolume = (high != low) ? volume * (high - close) / (high - low) : 0
totalVolume = volume

// --- Define Market Direction over Last 30 Minutes (6 candles in 5-minute chart) ---
lookback = 6  // 30 minutes / 5 minutes = 6 bars

prevClose = close[lookback]  // Previous close 30 minutes ago
currentClose = close  // Current close
uptrend = currentClose > prevClose and isBullish  // Uptrend condition
downtrend = currentClose < prevClose and isBearish  // Downtrend condition

// --- Strategy Logic ---
longCondition = uptrend and buyVolume > sellVolume  // Buy signal when trend is up and buy volume exceeds sell volume
shortCondition = downtrend and sellVolume > buyVolume  // Sell signal when trend is down and sell volume exceeds buy volume

// --- Entry and Exit Strategy ---
if (longCondition)
    strategy.entry("Long", strategy.long)

if (shortCondition)
    strategy.entry("Short", strategy.short)

// --- Exit Strategy based on Stop Loss and Take Profit ---
strategy.exit("Exit Long", "Long", stop=close * (1 - stopLossPercent / 100), limit=close * (1 + takeProfitPercent / 100))
strategy.exit("Exit Short", "Short", stop=close * (1 + stopLossPercent / 100), limit=close * (1 - takeProfitPercent / 100))

// --- Plotting for Visualization ---
plot(ma, color=color.blue, title="50-period MA")  // Trend line
plotshape(longCondition, style=shape.labelup, location=location.belowbar, color=color.green, text="BUY")
plotshape(shortCondition, style=shape.labeldown, location=location.abovebar, color=color.red, text="SELL")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/High-Frequency-Price-Volume-Trend-Following-with-Volume-Analysis-Adaptive-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m