High Reward to Risk Price Structure Breakout Trading Strategy
This is a pure price action breakout trading strategy with a 1:5 risk-reward ratio design. The strategy executes trades by identifying breakouts of key price levels and dynamically sets stop-loss and profit targets…
Overview
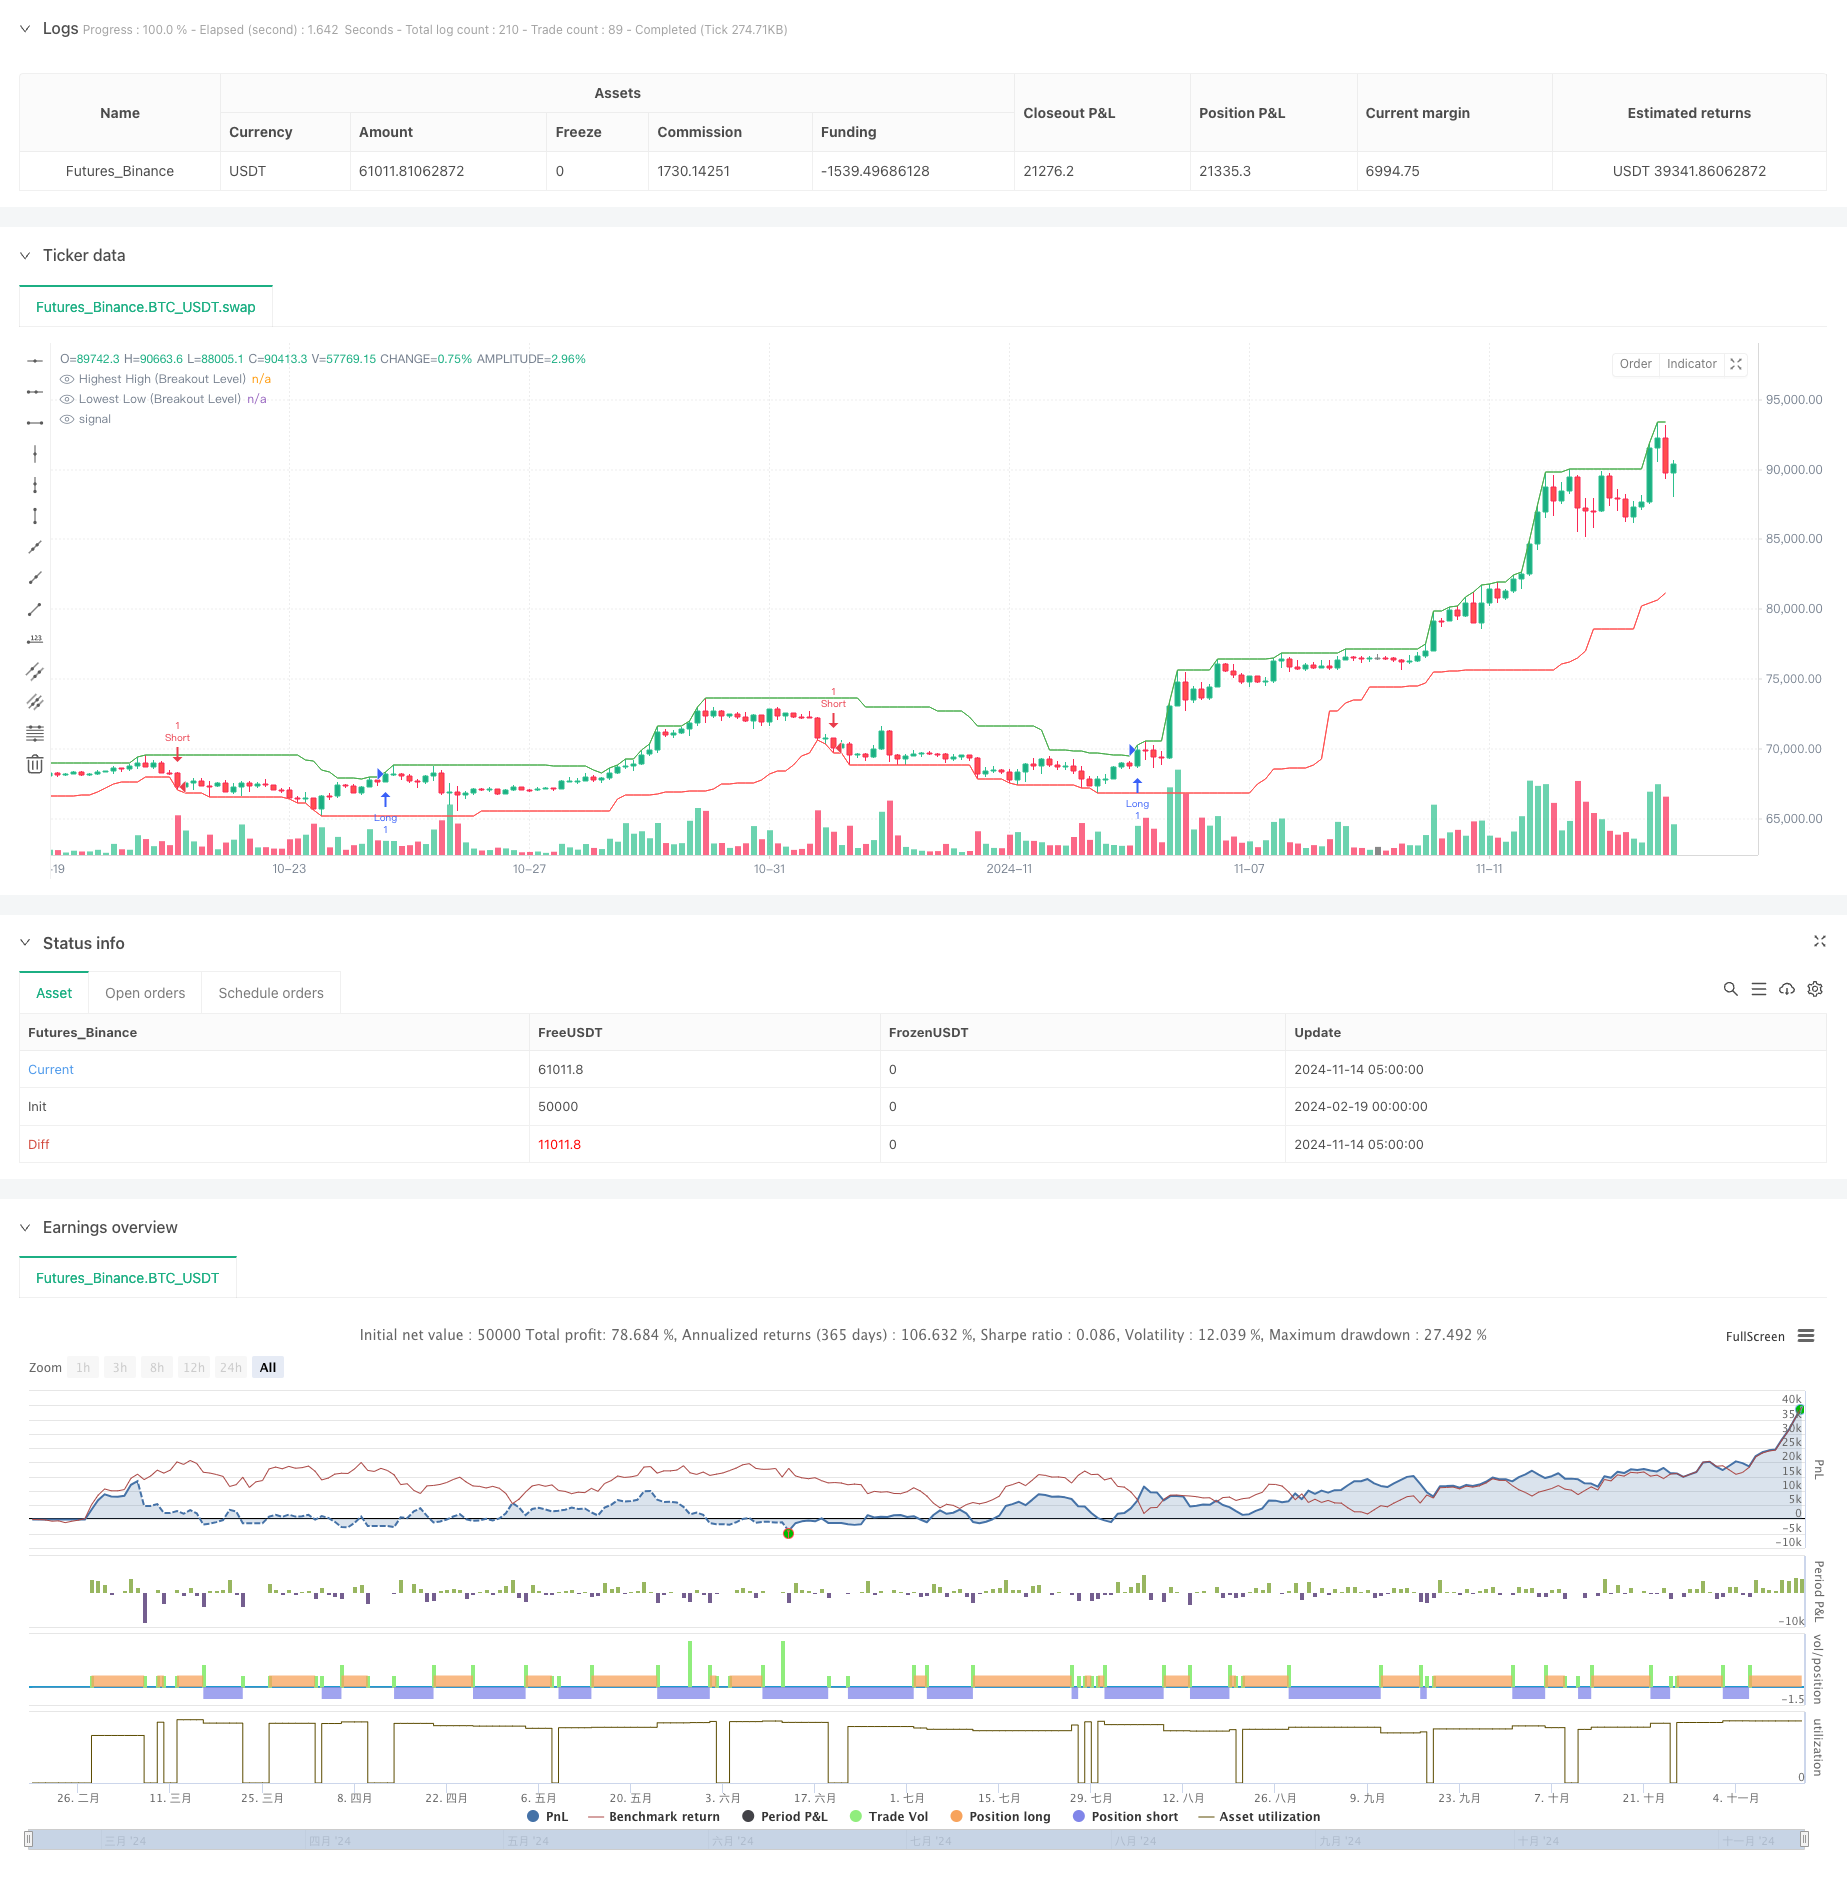
This is a pure price action breakout trading strategy with a 1:5 risk-reward ratio design. The strategy executes trades by identifying breakouts of key price levels and dynamically sets stop-loss and profit targets based on market structure. It operates without any technical indicators, relying solely on real-time price action for trading decisions.
Strategy Principles
The core logic includes several key components:
- Identifies highest and lowest price levels through a lookback period to establish breakout reference points
- Opens long positions when closing price breaks above previous highs, and short positions when breaking below previous lows
- Sets dynamic stop-loss levels based on recent volatility, with longs stopped at swing lows and shorts at swing highs
- Calculates profit targets based on a 1:5 risk-reward ratio
- Implements daily trade limits to prevent overtrading The entire trading process is based purely on price action without any technical indicators.
Strategy Advantages
- Pure price action trading, avoiding indicator lag interference
- High risk-reward ratio design, with potential profit 5 times the risk per trade
- Dynamic stop-loss setting that adapts to market structure
- Clear trading signals and visual markers for easy execution
- Highly adjustable parameters to adapt to different market conditions
- Strict risk control, including daily trade limits
Strategy Risks
- May generate frequent false breakout signals in ranging markets
- High risk-reward ratio might result in relatively lower win rate
- Post-breakout retracements may trigger stop-losses
- Market volatility changes can affect strategy performance
- Requires significant price movement to reach profit targets
Mitigation measures:
- Use the strategy in trending markets
- Avoid trading during major news releases
- Set appropriate position sizes
- Regularly review and optimize parameters
Strategy Optimization Directions
- Add trend filters to trade only in the main trend direction
- Implement volume confirmation to improve breakout reliability
- Dynamically adjust risk-reward ratio based on volatility
- Incorporate multi-timeframe analysis for better accuracy
- Develop smarter stop-loss mechanisms, such as trailing stops
- Add market condition recognition for adaptive parameter adjustment
Summary
This is a well-designed price action trading strategy with clear logic. Through its high risk-reward ratio design, it pursues substantial returns while effectively controlling risk. The strategy's strengths lie in its pure price-driven approach, flexible parameters, and comprehensive risk control. While there are risks of false breakouts, the suggested optimization directions can further enhance the strategy's stability and reliability. The strategy is best suited for clearly trending markets and requires strict trading discipline from the trader.
Source Pine Script
/*backtest
start: 2024-02-19 00:00:00
end: 2024-11-14 08:00:00
period: 3h
basePeriod: 3h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("Filtered Price Action Breakout", overlay=true)

// === INPUTS ===
lookback = input.int(20, title="Breakout Lookback Period", minval=5)
stopLookback = input.int(10, title="Stop Loss Lookback Period", minval=3)
rrMultiplier = input.float(5.0, title="Risk-to-Reward Multiplier", step=0.1)
maxTradesPerDay = input.int(5, title="Max Trades Per Day", minval=1)

// Ensure there are enough bars for calculations
inRange = bar_index >= lookback

// === CALCULATIONS ===
// Highest high and lowest low over the 'lookback' period
highestHigh = ta.highest(high, lookback)
lowestLow = ta.lowest(low, lookback)

// Define breakout conditions (using previous bar's level)
bullBreakout = ta.crossover(close, highestHigh[1])
bearBreakout = ta.crossunder(close, lowestLow[1])

// Store breakout signals in variables to prevent inconsistencies
bullBreakoutSignal = bullBreakout
bearBreakoutSignal = bearBreakout

// Determine stop levels based on recent swing lows/highs
longStop = ta.lowest(low, stopLookback)
shortStop = ta.highest(high, stopLookback)

// Track number of trades per day (fixing boolean condition issue)
newDay = ta.change(time("D")) != 0
todayTrades = ta.barssince(newDay)
tradeCount = 0
if newDay
    tradeCount := 0
else
    tradeCount := tradeCount + 1

// === STRATEGY LOGIC: ENTRY & EXIT ===
if bullBreakoutSignal and tradeCount < maxTradesPerDay
    entryPrice = close
    stopLevel = longStop
    risk = entryPrice - stopLevel
    if risk > 0
        target = entryPrice + rrMultiplier * risk
        strategy.entry("Long", strategy.long)
        strategy.exit("Long Exit", from_entry="Long", stop=stopLevel, limit=target)
        tradeCount := tradeCount + 1

        // // Draw Markups
        // label.new(bar_index, entryPrice, text="Long Entry", color=color.green, textcolor=color.white, size=size.small, style=label.style_label_down)
        // line.new(x1=bar_index, y1=entryPrice, x2=bar_index + 5, y2=entryPrice, color=color.green, width=2)
        // line.new(x1=bar_index, y1=stopLevel, x2=bar_index + 5, y2=stopLevel, color=color.red, width=2, style=line.style_dotted)
        // line.new(x1=bar_index, y1=target, x2=bar_index + 5, y2=target, color=color.blue, width=2, style=line.style_dashed)
        // label.new(bar_index, stopLevel, text="Stop Loss", color=color.red, textcolor=color.white, size=size.small, style=label.style_label_down)
        // label.new(bar_index, target, text="Target", color=color.blue, textcolor=color.white, size=size.small, style=label.style_label_up)

if bearBreakoutSignal and tradeCount < maxTradesPerDay
    entryPrice = close
    stopLevel = shortStop
    risk = stopLevel - entryPrice
    if risk > 0
        target = entryPrice - rrMultiplier * risk
        strategy.entry("Short", strategy.short)
        strategy.exit("Short Exit", from_entry="Short", stop=stopLevel, limit=target)
        tradeCount := tradeCount + 1

        // // Draw Markups
        // label.new(bar_index, entryPrice, text="Short Entry", color=color.red, textcolor=color.white, size=size.small, style=label.style_label_up)
        // line.new(x1=bar_index, y1=entryPrice, x2=bar_index + 5, y2=entryPrice, color=color.red, width=2)
        // line.new(x1=bar_index, y1=stopLevel, x2=bar_index + 5, y2=stopLevel, color=color.green, width=2, style=line.style_dotted)
        // line.new(x1=bar_index, y1=target, x2=bar_index + 5, y2=target, color=color.blue, width=2, style=line.style_dashed)
        // label.new(bar_index, stopLevel, text="Stop Loss", color=color.green, textcolor=color.white, size=size.small, style=label.style_label_up)
        // label.new(bar_index, target, text="Target", color=color.blue, textcolor=color.white, size=size.small, style=label.style_label_down)

// === PLOTTING ===
plot(highestHigh, color=color.green, title="Highest High (Breakout Level)")
plot(lowestLow, color=color.red, title="Lowest Low (Breakout Level)")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/High-Reward-to-Risk-Price-Structure-Breakout-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- Dual Thrust StrategyPine Script · Breakout · 10m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- Dynamic Dual Moving Average Breakthrough Trading System Dynamic Dual Moving Average Breakthrough Trading SystemPine Script · Breakout · 1d
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d