Strategy vault / Mean reversion
High Win Rate Trend Mean Reversion Trading Strategy
This is a quantitative trading strategy based on mean reversion principles, combining technical indicators such as Bollinger Bands, Relative Strength Index (RSI), and Average True Range (ATR) to identify market…
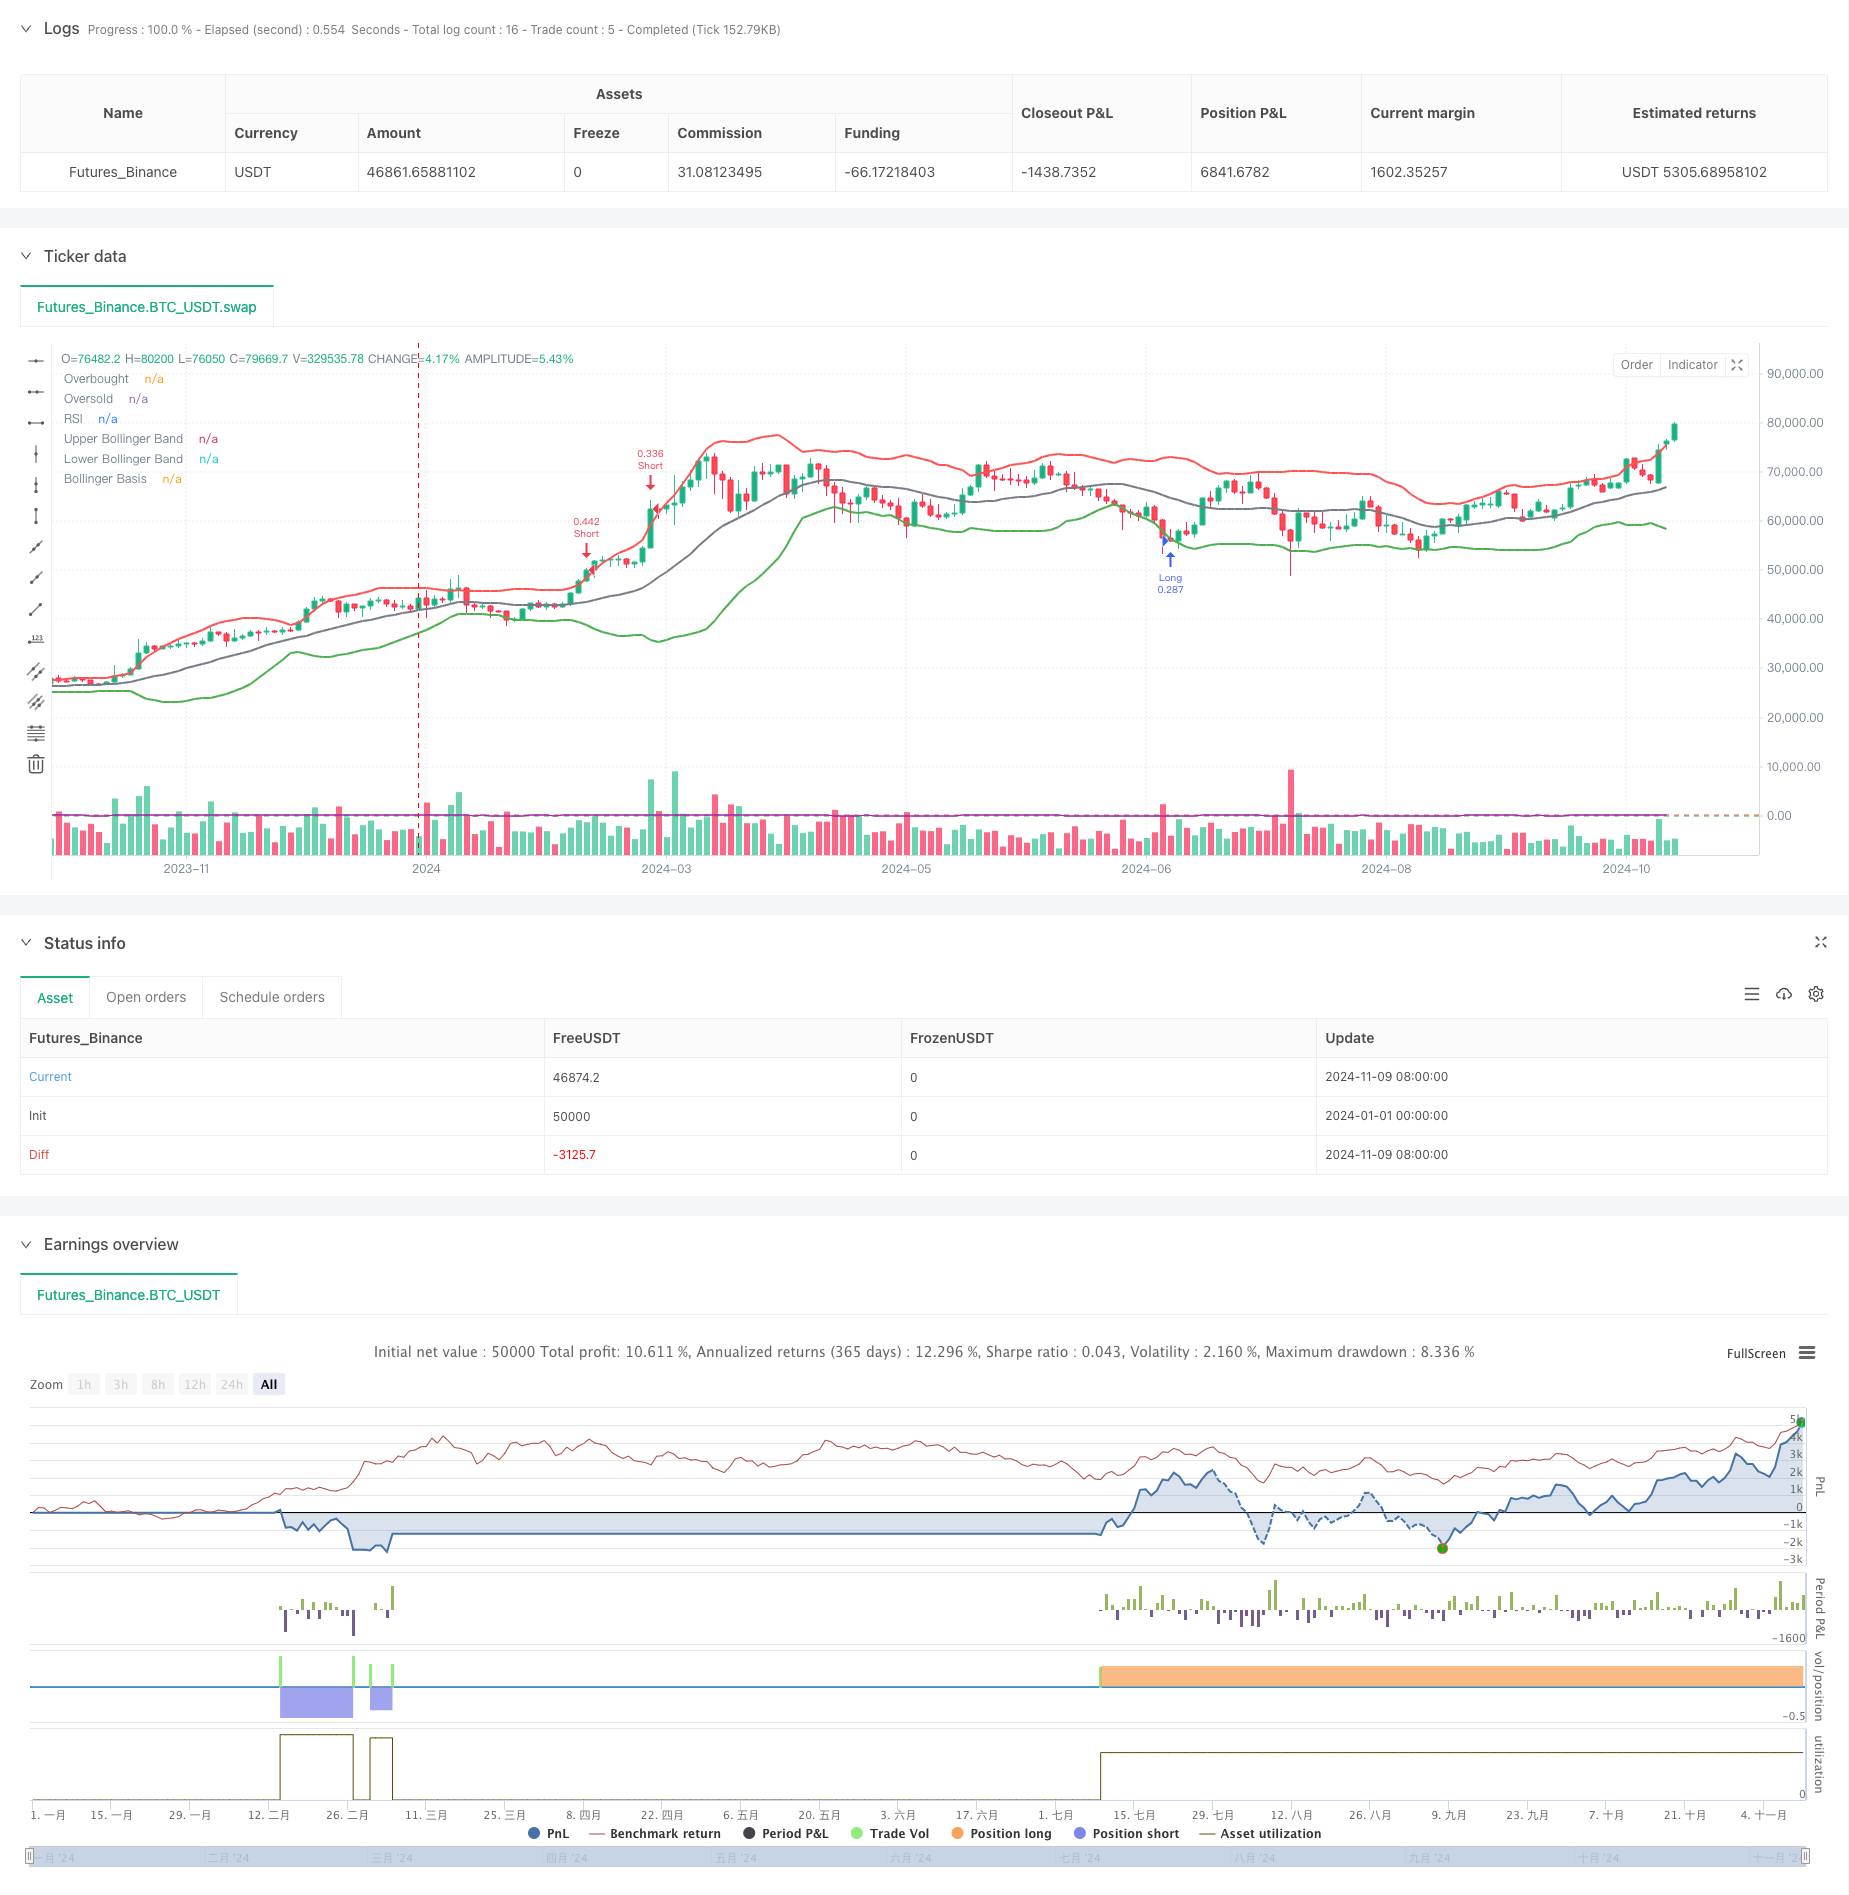
Overview
This is a quantitative trading strategy based on mean reversion principles, combining technical indicators such as Bollinger Bands, Relative Strength Index (RSI), and Average True Range (ATR) to identify market overbought and oversold conditions. The strategy employs a low risk-reward ratio to achieve high win rates and implements risk management through position sizing.
Strategy Principles
The strategy executes trades through the following aspects:
- Uses Bollinger Bands (20-day) to determine price movement ranges
- Employs RSI (14-day) to identify overbought and oversold conditions
- Utilizes ATR (14-day) for dynamic stop-loss and take-profit levels
- Enters long positions when price breaks below the lower band and RSI is below 30
- Enters short positions when price breaks above the upper band and RSI is above 70
- Sets a 0.75 risk-reward ratio to achieve higher win rates
- Implements 2% risk per trade based on account equity
Strategy Advantages
- Combines multiple technical indicators for reliable signals
- Captures market opportunities through mean reversion characteristics
- Uses ATR for dynamic stop-loss adjustment
- Higher win rate through low risk-reward ratio setting
- Effective capital allocation through percentage-based risk management
- Clear and easy-to-understand strategy logic
- Good scalability and optimization potential
Strategy Risks
- May face frequent stop-losses in strong trend markets
- Lower potential profits per trade due to low risk-reward ratio
- Potential lag in Bollinger Bands and RSI indicators
- Stop-loss positions may be suboptimal during high volatility
- Trading costs may impact overall returns Solutions:
- Add trend filters
- Optimize entry timing
- Adjust indicator parameters
- Introduce additional confirmation signals
Optimization Directions
- Incorporate trend indicators to avoid counter-trend trades
- Optimize RSI and Bollinger Bands parameters for better accuracy
- Implement dynamic risk-reward ratios based on market conditions
- Add volume indicators for signal confirmation
- Include time filters to avoid specific trading periods
- Develop adaptive parameter mechanisms
- Enhance position sizing and risk management system
Conclusion
The strategy builds a robust trading system through mean reversion principles and multiple technical indicators. The low risk-reward ratio setting helps achieve higher win rates, while strict risk management ensures capital preservation. Despite inherent risks, continuous optimization and refinement could lead to improved performance. This strategy is suitable for conservative traders, particularly in markets with high volatility.
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-11-11 00:00:00
period: 2d
basePeriod: 2d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("High Win Rate Mean Reversion Strategy for Gold", overlay=true)

// Input Parameters
bbLength = input.int(20, title="Bollinger Bands Length")
bbMult = input.float(2, title="Bollinger Bands Multiplier")
rsiLength = input.int(14, title="RSI Length")
rsiOverbought = input.int(70, title="RSI Overbought Level")
rsiOversold = input.int(30, title="RSI Oversold Level")
atrLength = input.int(14, title="ATR Length")
rrRatio = input.float(0.75, title="Risk/Reward Ratio", step=0.05)  // Lower RRR to achieve a high win rate
riskPerTrade = input.float(2.0, title="Risk per Trade (%)", step=0.1) / 100  // 2% risk per trade

// Bollinger Bands Calculation
basis = ta.sma(close, bbLength)
dev = bbMult * ta.stdev(close, bbLength)
upperBand = basis + dev
lowerBand = basis - dev

// RSI Calculation
rsi = ta.rsi(close, rsiLength)

// ATR Calculation for Stop Loss
atr = ta.atr(atrLength)

// Entry Conditions: Mean Reversion
longCondition = close < lowerBand and rsi < rsiOversold
shortCondition = close > upperBand and rsi > rsiOverbought

// Stop Loss and Take Profit based on ATR
longStopLoss = close - atr * 1.0  // 1x ATR stop loss for long trades
shortStopLoss = close + atr * 1.0  // 1x ATR stop loss for short trades

longTakeProfit = close + (close - longStopLoss) * rrRatio  // 0.75x ATR take profit
shortTakeProfit = close - (shortStopLoss - close) * rrRatio  // 0.75x ATR take profit

// Calculate position size based on risk
equity = strategy.equity
riskAmount = equity * riskPerTrade
qtyLong = riskAmount / (close - longStopLoss)
qtyShort = riskAmount / (shortStopLoss - close)

// Long Trade
if (longCondition)
    strategy.entry("Long", strategy.long, qty=qtyLong)
    strategy.exit("Take Profit/Stop Loss", from_entry="Long", limit=longTakeProfit, stop=longStopLoss)

// Short Trade
if (shortCondition)
    strategy.entry("Short", strategy.short, qty=qtyShort)
    strategy.exit("Take Profit/Stop Loss", from_entry="Short", limit=shortTakeProfit, stop=shortStopLoss)

// Plot Bollinger Bands
plot(upperBand, color=color.red, linewidth=2, title="Upper Bollinger Band")
plot(lowerBand, color=color.green, linewidth=2, title="Lower Bollinger Band")
plot(basis, color=color.gray, linewidth=2, title="Bollinger Basis")

// Plot RSI for visual confirmation
hline(rsiOverbought, "Overbought", color=color.red)
hline(rsiOversold, "Oversold", color=color.green)
plot(rsi, color=color.purple, title="RSI")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/High-Win-Rate-Trend-Mean-Reversion-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Moving Average RSI Synergy Options Quantitative Trading StrategyPine Script · Mean reversion · 1h
- Multi Indicator Reversal Point Capture Trading StrategyPine Script · Mean reversion · 1d
- Multi Timeframe Adaptive Mean Reversion with Volume Analysis StrategyPine Script · Mean reversion · 1h
- Reversal Trading Strategy with Bollinger Bands RSI ADX and ATRPine Script · Mean reversion · 1h
- CCTBBO Reversal Tracking StrategyPine Script · Mean reversion · 45m
- Multi Timeframe Gold Reversal Tracking StrategyPine Script · Mean reversion · 2h