Strategy vault / Trend following
Ichimoku Cloud MACD and Stochastic Based Multi Timeframe Trend Tracking Strategy
This strategy integrates Ichimoku Cloud, moving average, MACD, Stochastic and ATR indicators to identify and track trends across multiple timeframes. It adopts ATR-based stop loss and take profit methods for risk…
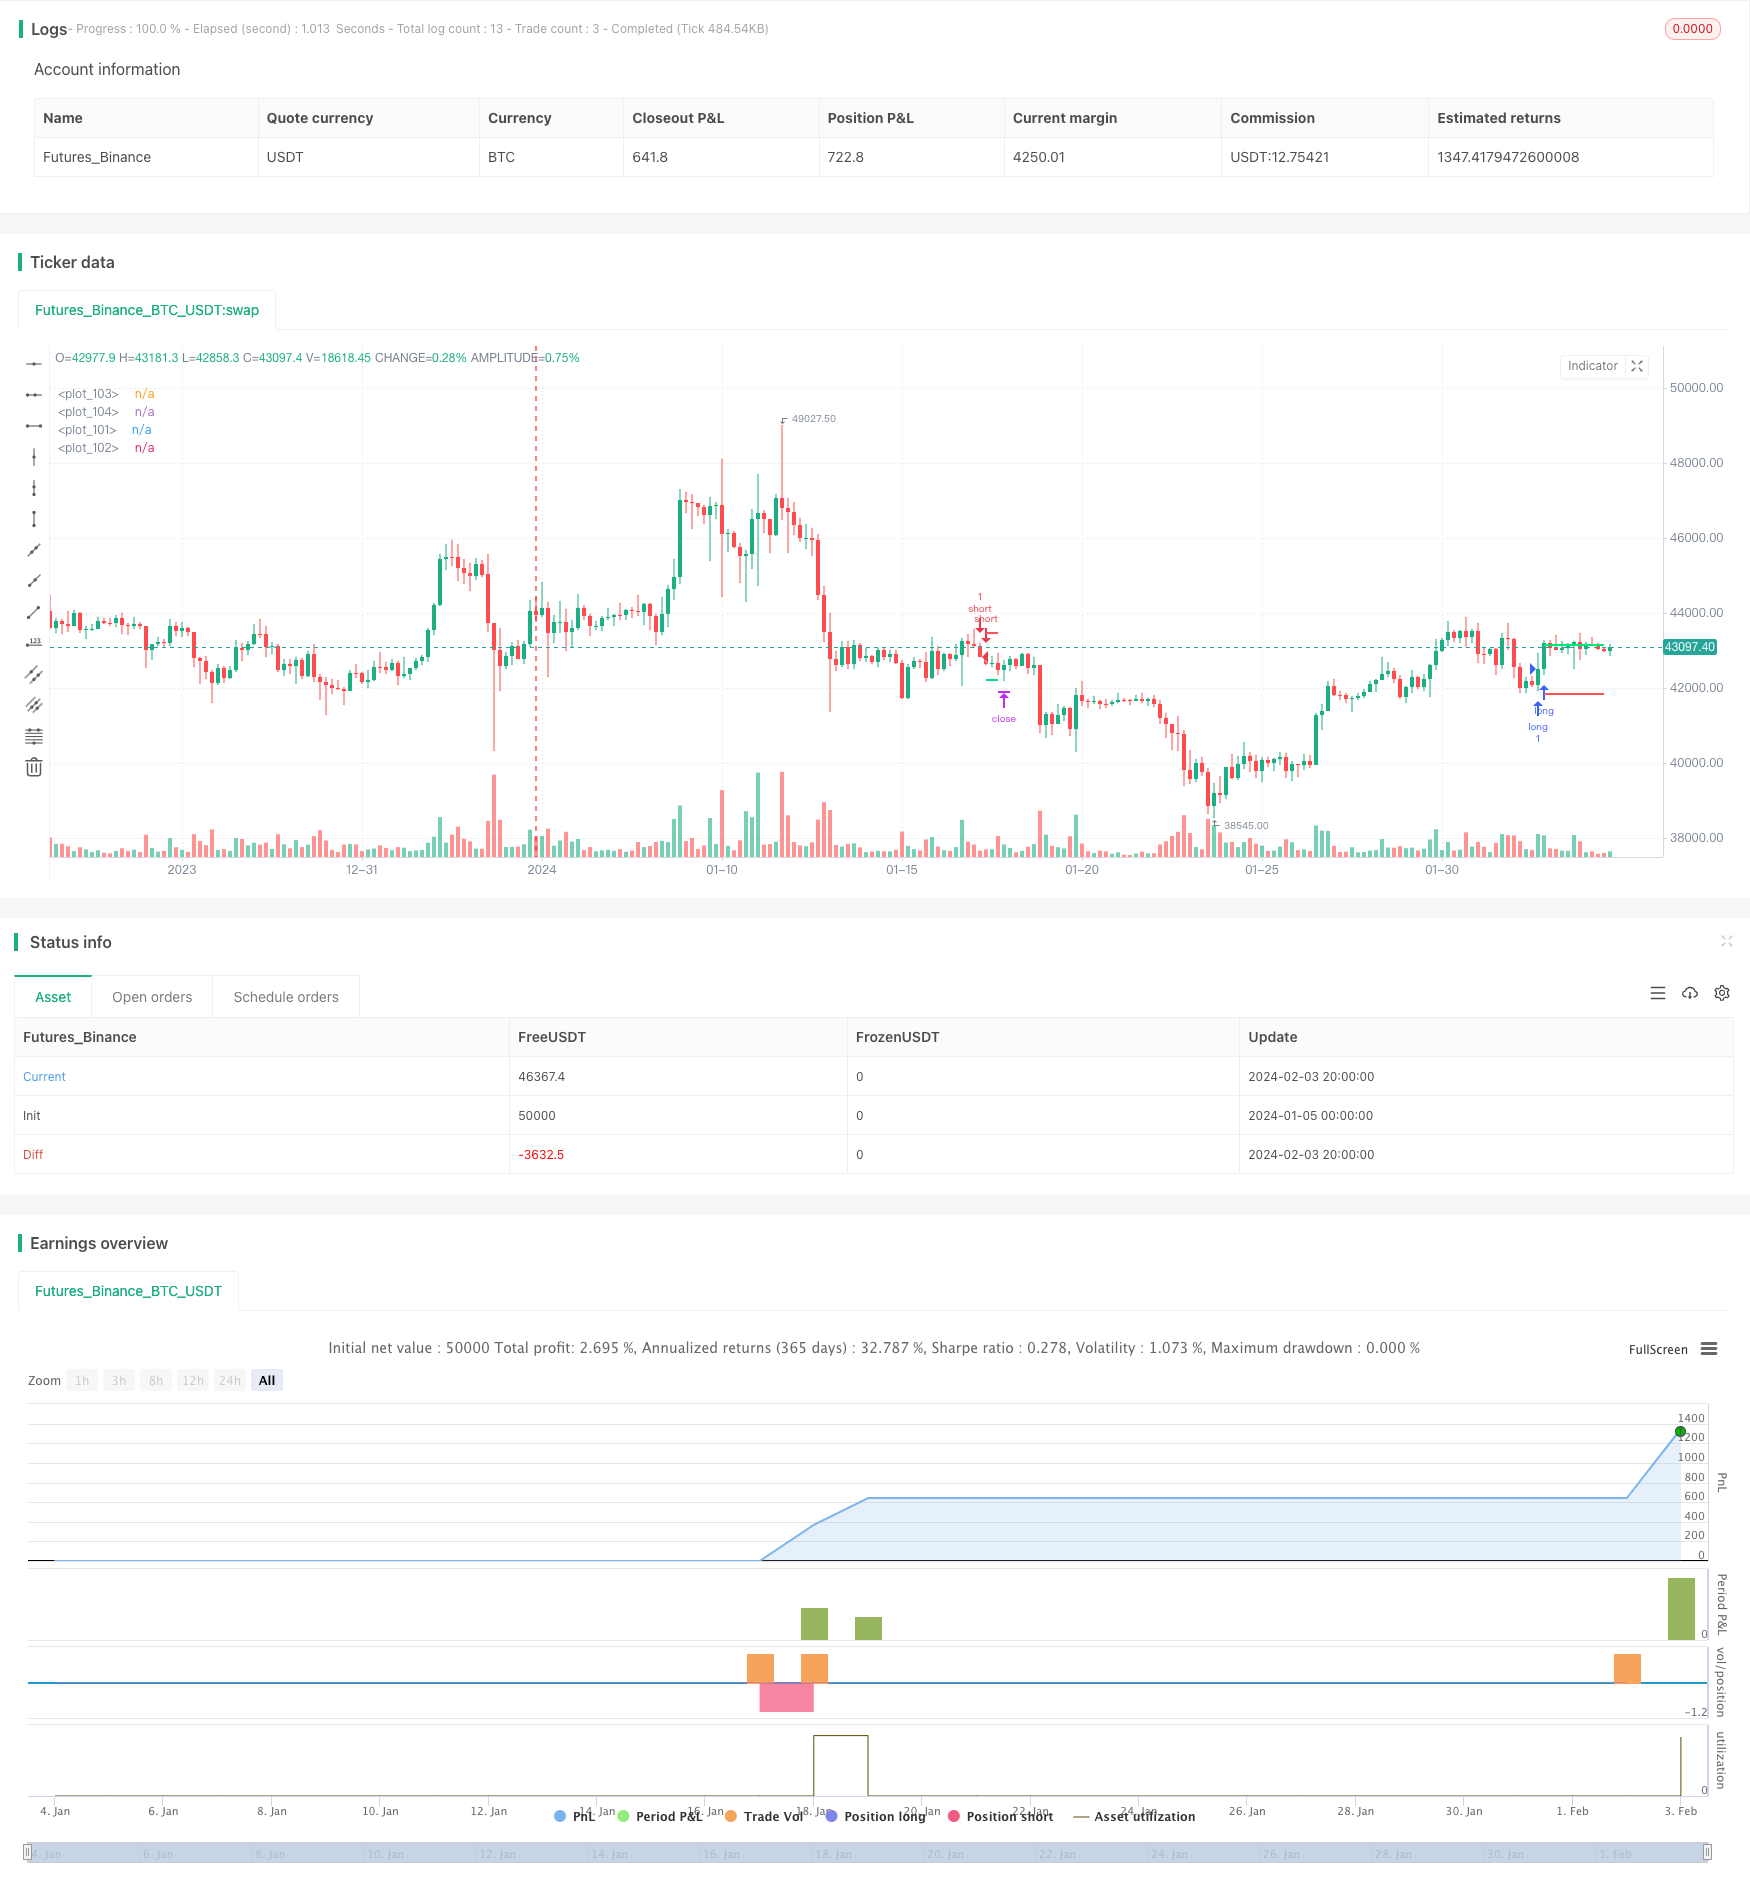
Overview
This strategy integrates Ichimoku Cloud, moving average, MACD, Stochastic and ATR indicators to identify and track trends across multiple timeframes. It adopts ATR-based stop loss and take profit methods for risk control after obtaining high probability trend signals.
Strategy Logic
Ichimoku Cloud judges medium and long term trend directions. The CLOSE price crossing above Ichimoku's turning line and baseline is a bullish signal, and crossing below them is a bearish signal.
MACD judges short-term trends and overbought/oversold situations. MACD histogram crossing above MACD signal line is a bullish signal, and crossing below is a bearish signal.
Stochastic KD judges overbought/oversold zones. K line crossing above 20 is a bullish signal, and crossing below 80 is a bearish signal.
Moving average judges medium-term trends. Close price crossing above MA is a bullish signal, and crossing below is a bearish signal.
Integrate signals from the above indicators to filter out some false signals and form high probability sustainable trend signals.
Use ATR to calculate stop loss and take profit price. Use a certain multiple of ATR as stop loss and take profit bits to control risks.
Advantages
Identify trends across multiple timeframes to improve signal accuracy.
Widely employ indicator combos to effectively filter out false signals.
ATR-based stop loss & take profit significantly limits per trade loss.
Customizable strictness of entry conditions caters to different risk appetites.
Risks
Trend following nature fails to detect reversals caused by black swan events.
Idealized ATR stop loss is hard to fully replicate in live trading.
Improper parameter settings may lead to overtrading or insufficient signal accuracy.
Parameter tweak is needed to fit different products and market environments.
Enhancement Areas
Introduce machine learning to aid judging trend reversal points.
Optimize ATR multiplier parameter values for different products.
Incorporate other factors like volume changes to improve breakthrough signal accuracy.
Keep optimizing parameters based on backtest results to find best parameter combinations.
Summary
This strategy leverages Ichimoku Cloud, MACD, Stochastic and more for multi-timeframe trend identification, capturing trends while avoiding being trapped by black swan events. The ATR-based stop loss & take profit effectively limits per trade loss. With more auxiliary judgments and machine learning methods introduced, this strategy has further optimization potential.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 9 | Conversion Line Length |
| v_input_2 | 26 | Base Line Length |
| v_input_3 | 52 | Lagging Span 2 Length |
| v_input_4 | 26 | Displacement |
| v_input_5 | 12 | Fast Length |
| v_input_6 | 26 | Slow Length |
| v_input_7_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_8 | 9 | Signal Smoothing |
| v_input_9 | false | Simple MA (Oscillator) |
| v_input_10 | false | Simple MA (Signal Line) |
| v_input_11 | 5 | %K Length |
| v_input_12 | 3 | %K Smoothing |
| v_input_13 | 3 | %D Smoothing |
| v_input_14 | 8 | Atr Length |
| v_input_15 | true | Stop loss multi Atr |
| v_input_16 | true | Take profit multi Atr |
| v_input_17 | 0 | Smoothing: RMA | SMA | EMA | WMA |
| v_input_18 | 0 | Position side: Both | Short | Long |
| v_input_19 | true | Show sl&tp lines |
| v_input_20 | 100 | MA Length |
| v_input_21 | timestamp(1 Jan 2020 00:00 +0000) | Backtesting Start Time |
| v_input_22 | timestamp(31 Dec 2025 23:59 +0000) | Backtesting End Time |
Source Pine Script
/*backtest
start: 2024-01-05 00:00:00
end: 2024-02-04 00:00:00
period: 4h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © FXFUNDINGMATE

//@version=4
strategy(title="FXFUNDINGMATE TREND INDICATOR", overlay=true)

//Ichimoku Cloud
conversionPeriods = input(9, minval=1, title="Conversion Line Length")
basePeriods = input(26, minval=1, title="Base Line Length")
laggingSpan2Periods = input(52, minval=1, title="Lagging Span 2 Length")
displacement = input(26, minval=1, title="Displacement")
donchian(len) => avg(lowest(len), highest(len))
conversionLine = donchian(conversionPeriods)
baseLine = donchian(basePeriods)
leadLine1 = avg(conversionLine, baseLine)[displacement - 1]
leadLine2 = donchian(laggingSpan2Periods)[displacement - 1]


//macd
fast_length = input(title="Fast Length", type=input.integer, defval=12)
slow_length = input(title="Slow Length", type=input.integer, defval=26)
src = input(title="Source", type=input.source, defval=close)
signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9)
sma_source = input(title="Simple MA (Oscillator)", type=input.bool, defval=false)
sma_signal = input(title="Simple MA (Signal Line)", type=input.bool, defval=false)

fast_ma = sma_source ? sma(src, fast_length) : ema(src, fast_length)
slow_ma = sma_source ? sma(src, slow_length) : ema(src, slow_length)
macd = fast_ma - slow_ma
signal = sma_signal ? sma(macd, signal_length) : ema(macd, signal_length)
hist = macd - signal


//kd
periodK = input(5, title="%K Length", minval=1)
smoothK = input(3, title="%K Smoothing", minval=1)
periodD = input(3, title="%D Smoothing", minval=1)
k = sma(stoch(close, high, low, periodK), smoothK)
d = sma(k, periodD)


//atr
atrlength = input(title="Atr Length", defval=8, minval=1)
SMulti = input(title="Stop loss multi Atr", defval=1.0)
TMulti = input(title="Take profit multi Atr", defval=1.0)
smoothing = input(title="Smoothing", defval="RMA", options=["RMA", "SMA", "EMA", "WMA"])
ma_function(source, length) =>
	if smoothing == "RMA"
		rma(source, length)
	else
		if smoothing == "SMA"
			sma(source, length)
		else
			if smoothing == "EMA"
				ema(source, length)
			else
				wma(source, length)
atr = ma_function(tr(true), atrlength)


operation_type = input(defval = "Both", title = "Position side", options = ["Long", "Short", "Both"])
operation = operation_type == "Long" ? 1 : operation_type == "Short" ? 2 : 3
showlines = input(true,  title="Show sl&tp lines")

// MA
sma_len = input(100, title="MA Length", type=input.integer)
sma = sma(close, sma_len)

longCond = crossover(k, 20) and macd > 0 and close > sma and close > leadLine1 and close > leadLine2
shortCond = crossunder(k, 80)  and macd < 0 and close < sma and close < leadLine1 and close < leadLine2

entry_price  = float(0.0) //set float
entry_price := strategy.position_size != 0 or longCond or shortCond ? strategy.position_avg_price : entry_price[1]
entry_atr = valuewhen(longCond or shortCond, atr,0)
short_stop_level     = float(0.0)   //set float
short_profit_level   = float(0.0)   //set float
long_stop_level      = float(0.0)   //set float
long_profit_level    = float(0.0)   //set float
short_stop_level    := entry_price + SMulti * entry_atr
short_profit_level  := entry_price - TMulti * entry_atr
long_stop_level     := entry_price - SMulti * entry_atr
long_profit_level   := entry_price + TMulti * entry_atr


//  Strategy Backtest Limiting Algorithm
i_startTime = input(defval = timestamp("1 Jan 2020 00:00 +0000"), title = "Backtesting Start Time", type = input.time)
i_endTime = input(defval = timestamp("31 Dec 2025 23:59 +0000"), title = "Backtesting End Time", type = input.time)
timeCond = true

if (operation == 1 or operation == 3)
    strategy.entry("long" , strategy.long , when=longCond and timeCond, alert_message = "Long")
    strategy.exit("SL/TP", from_entry = "long" , limit = long_profit_level , stop = long_stop_level , alert_message = "Long exit")

if (operation == 2 or operation == 3)
    strategy.entry("short", strategy.short, when=shortCond and timeCond, alert_message="Short")
    strategy.exit("SL/TP", from_entry = "short", limit = short_profit_level , stop = short_stop_level , alert_message = "Short exit")

if time > i_endTime
    strategy.close_all(comment = "close all", alert_message = "close all")

plot(showlines and strategy.position_size <= 0 ? na : long_stop_level,    color=color.red,  style=plot.style_linebr, linewidth = 2)
plot(showlines and strategy.position_size <= 0 ? na : long_profit_level,  color=color.lime, style=plot.style_linebr, linewidth = 2)
plot(showlines and strategy.position_size >= 0 ? na : short_stop_level,   color=color.red,  style=plot.style_linebr, linewidth = 2)
plot(showlines and strategy.position_size >= 0 ? na : short_profit_level, color=color.lime, style=plot.style_linebr, linewidth = 2)

//}
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ichimoku-Cloud-MACD-and-Stochastic-Based-Multi-Timeframe-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Triple Supertrend Ichimoku Cloud Quantitative Trading StrategyPine Script · Trend following · 1d
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h
- Three Exponential Moving Averages and Stochastic Relative Strength Index Trading StrategyPine Script · Trend following · 1h
- TrendHunter w MF Multi Timeframe Trend StrategyPine Script · Trend following · 1h
- Multi Technical Indicator Gold Real Time Movement Detection and Risk Management StrategyPine Script · Trend following · 1d