Intraday Pivot Breakout Strategy
This strategy generates trading signals based on price breakouts within a specified time period. The main idea is to observe price movements during certain periods and use breakouts in price range to determine trend…
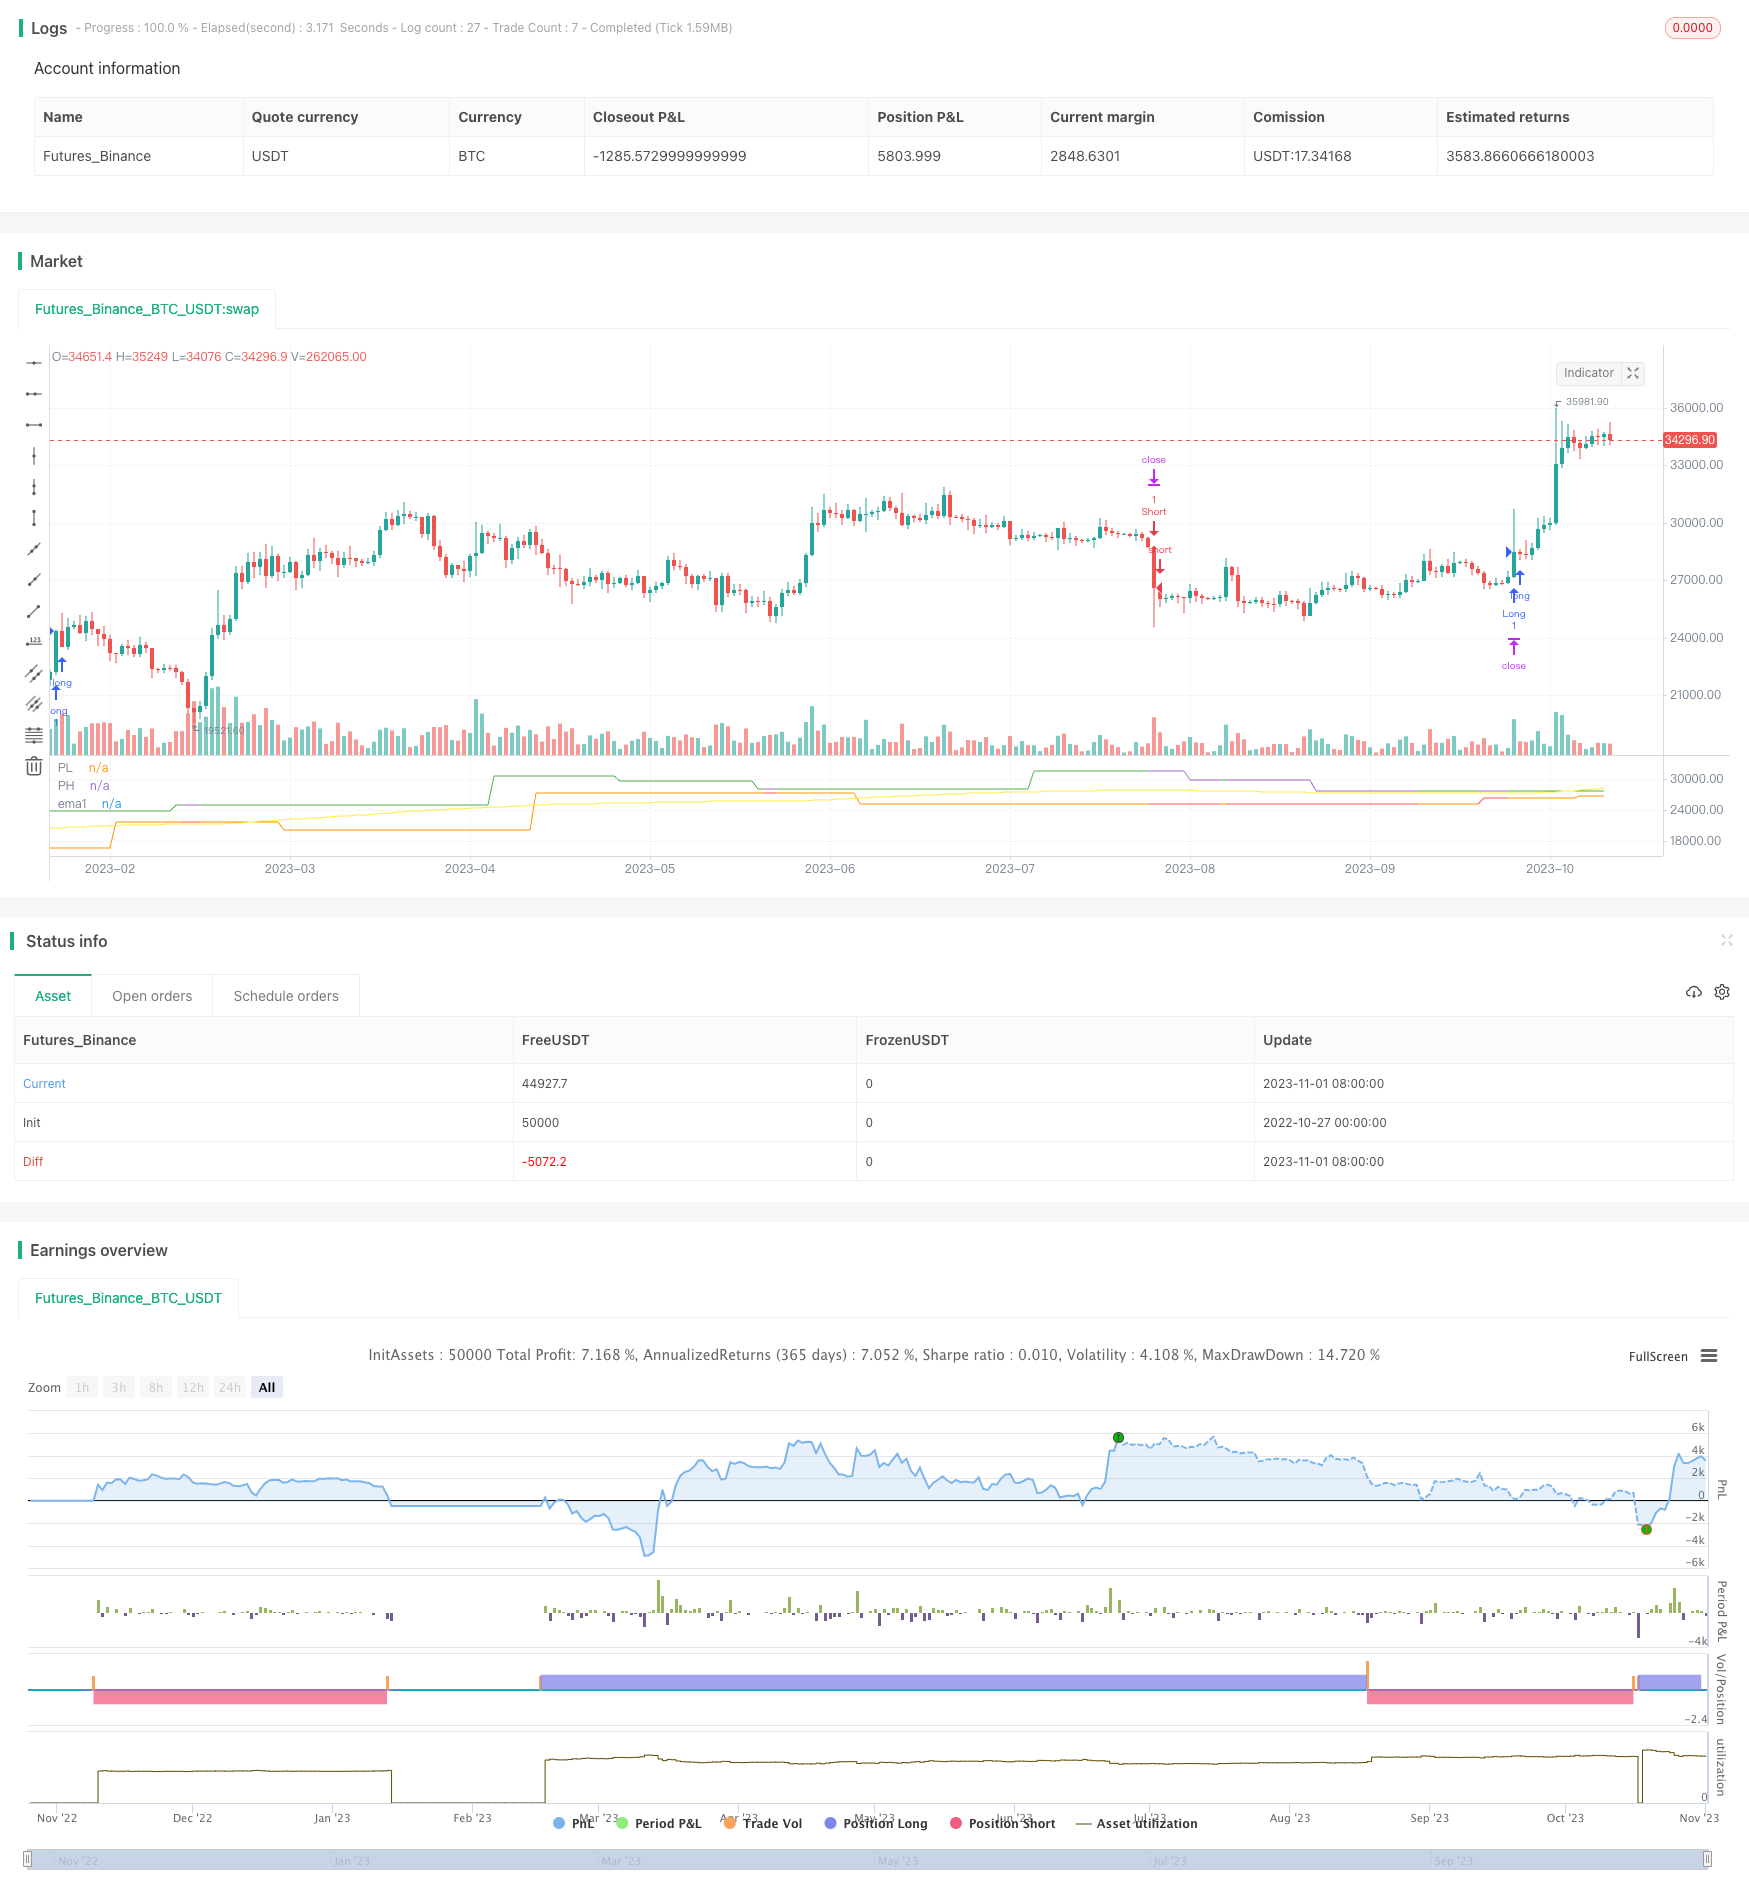
Overview
This strategy generates trading signals based on price breakouts within a specified time period. The main idea is to observe price movements during certain periods and use breakouts in price range to determine trend changes.
Strategy Logic
The strategy calculates the highest high and lowest low of price within a certain timeframe, known as pivot high and pivot low, to gauge price movements.
Specifically, it computes the highest high of past N bars as the pivot high and the lowest low of past M bars as the pivot low. A long signal is generated when the current bar's high breaks above the pivot high. A short signal is generated when the current bar's low breaks below the pivot low.
After entry, the strategy uses ATR for stop loss and intraday stop loss. It also closes all positions at a specific timeframe (e.g. 14:55).
The strategy effectively captures trends using simple price breakouts during certain periods, making it ideal for intraday trading. The logic is clear and easy to implement.
Advantages
- Captures trend changes reliably using price breakouts
- Simple implementation with basic OHLC data
- Reasonable stop loss and intraday stop loss manage risks
- Avoids overnight risks suitable for intraday trading
- Few parameters easy to optimize
Risks and Mitigations
Potential lag, may miss early trend start
Adjust timeframe or combine other indicators for entry
More false signals when trend is unclear
Tune parameters, add filters like indicators, volume etc.
Higher capital costs for active intraday trading
Adjust position sizing, extend holding period
Reliance on parameter optimization
Adapt parameters to changing market conditions using machine learning etc.
Enhancement Opportunities
Test other price data like typical price, median price etc.
Add filters like volume, volatility
Try different parameter combinations
Incorporate trend indicators to determine direction
Auto-optimize parameters using machine learning
Expand to multiple timeframes for better entry
Conclusion
The strategy has a clear and concise logic, effectively capitalizing on price breakouts to capture short-term trends with good profit factors. With few tunable parameters easy for testing and optimization, it is well suited for intraday trading. While lag and false signals exist, they can be addressed through parameter tuning, adding filters etc. The strategy provides a robust breakout-based trading framework with ample optimization space.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | leftbars |
| v_input_2 | 15 | rightbars |
| v_input_int_1 | 150 | PRICE CROSS EMA |
| v_input_float_1 | 3.2 | _ATR LONG |
| v_input_float_2 | 3.2 | _ATR SHORT |
| v_input_float_3 | 200 | RISK |
Source Pine Script
/*backtest
start: 2022-10-27 00:00:00
end: 2023-11-02 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//   ____________        _________           _____________
//  |____________|      ||________|          ||__________|
//       ||             ||        ||         ||
//       ||             ||________||         ||
//       ||     H E     ||________   U L L   ||       H A R T I S T
//       ||             ||        ||         ||
//       ||             ||________||         ||__________
//       ||             ||________|          ||__________|

//@version=5
// strategy("PIVOT STRATEGY [5MIN TF]",overlay=true ,commission_type = strategy.cash, commission_value = 30 , slippage = 2, default_qty_value = 60, currency = currency.NONE, pyramiding = 0)
leftbars = input(defval = 10)
rightbars = input(defval = 15)

// ═══════════════════════════ //
// ----------> INPUTS <------- //
// ═══════════════════════════ //

EMA1 = input.int(title='PRICE CROSS EMA', defval = 150, minval = 10 ,maxval = 400)
factor1 = input.float(title='_ATR LONG',defval = 3.2 , minval = 1 , maxval = 5 , step = 0.1, tooltip = "ATR TRAIL LONG")
factor2 = input.float(title='_ATR SHORT',defval = 3.2 , minval = 1 , maxval = 5 , step = 0.1, tooltip = "ATR TRAIL SHORT")
risk = input.float(title='RISK',defval = 200 , minval = 1 , maxval = 5000 , step = 50, tooltip = "RISK PER TRADE")

var initialCapital = strategy.equity
t = time(timeframe.period, '0935-1400:1234567')
time_cond = true

// ══════════════════════════════════ //
// -----------> EMA DATA <----------- //
// ══════════════════════════════════ //
ema1 = ta.ema(close, EMA1)

plot(ema1, color=color.new(color.yellow, 0), style=plot.style_linebr, title='ema1')

// ══════════════════════════════════ //
// --------> TRAIL DATA <------------ //
// ══════════════════════════════════ //
// *******Calculate LONG TRAIL data*****
ATR_LO = ta.atr(14)*factor1

// *******Calculate SHORT TRAIL data*****
ATR_SH = ta.atr(14)*factor2

longStop = close - ATR_LO
shortStop = close + ATR_SH

// Plot atr data
//plot(longStop, color=color.new(color.green, 0), style=plot.style_linebr, title='Long Trailing Stop')
//plot(shortStop , color=color.new(color.red, 0), style=plot.style_linebr, title='Short Trailing Stop')

// ══════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════ //
// --------------------------------------------------------> PIVOT DATA <---------------------------------------------------------------------------------------------------- //
// ══════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════ //

ph = ta.pivothigh(close,leftbars, rightbars)
pl = ta.pivotlow(close,leftbars, rightbars)

pvt_condition1 = not na(ph)

upper_price = 0.0
upper_price := pvt_condition1 ? ph : upper_price[1]

pvt_condition2 = not na(pl)

lower_price = 0.0
lower_price := pvt_condition2 ? pl : lower_price[1]

// Signals
long  = ta.crossover(high, upper_price + syminfo.mintick)
short = ta.crossunder(low, lower_price - syminfo.mintick)

plot(upper_price, color= close > ema1  ? color.green : na, style=plot.style_line, title='PH')

plot(lower_price,  color= close <  ema1  ? color.red : na, style=plot.style_line, title='PL')


// ══════════════════════════════════//
// --------> LONG POSITIONS <--------//
// ══════════════════════════════════//
//******barinstate.isconfirmed used to avoid repaint in real time*******

if ( long and strategy.opentrades==0 and barstate.isconfirmed and time_cond and close >= ema1 )
    strategy.entry(id= "Long" ,direction = strategy.long, comment = "B")

//plot(longStop , color=color.new(color.blue, 0), style=plot.style_linebr, title='long Stop')

if strategy.position_size > 0
    strategy.exit("long tsl", "Long" , stop = longStop ,comment='S')


// ═════════════════════════════════════//
// --------> SHORT POSITIONS <--------- //
// ═════════════════════════════════════//
if ( short and strategy.opentrades==0 and barstate.isconfirmed and time_cond and close <= ema1 )
    strategy.entry(id = "Short" ,direction = strategy.short,  comment = "S")

if strategy.position_size < 0
    strategy.exit("short tsl", "Short" ,  stop = shortStop ,comment='B')

// ════════════════════════════════════════════════//
// --------> CLOSE ALL POSITIONS BY 3PM <--------- //
// ════════════════════════════════════════════════//
strategy.close_all(when = hour == 14 and minute == 55)

// ════════════════════════════════════════//
// --------> MAX INTRADAY LOSS  <--------- //
// ════════════════════════════════════════//
// strategy.risk.max_intraday_loss(type = strategy.cash, value = risk)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Intraday-Pivot-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Kana Candle Breakout Strategy Based on Moving Average and Support ResistancePine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Trading Strategy Based on Ichimoku with Multiple SignalsPine Script · Breakout · 1h
- Honey Trend ATR Breakout StrategyPine Script · Breakout · 1h