Isolation Band Oscillation Tracking Strategy
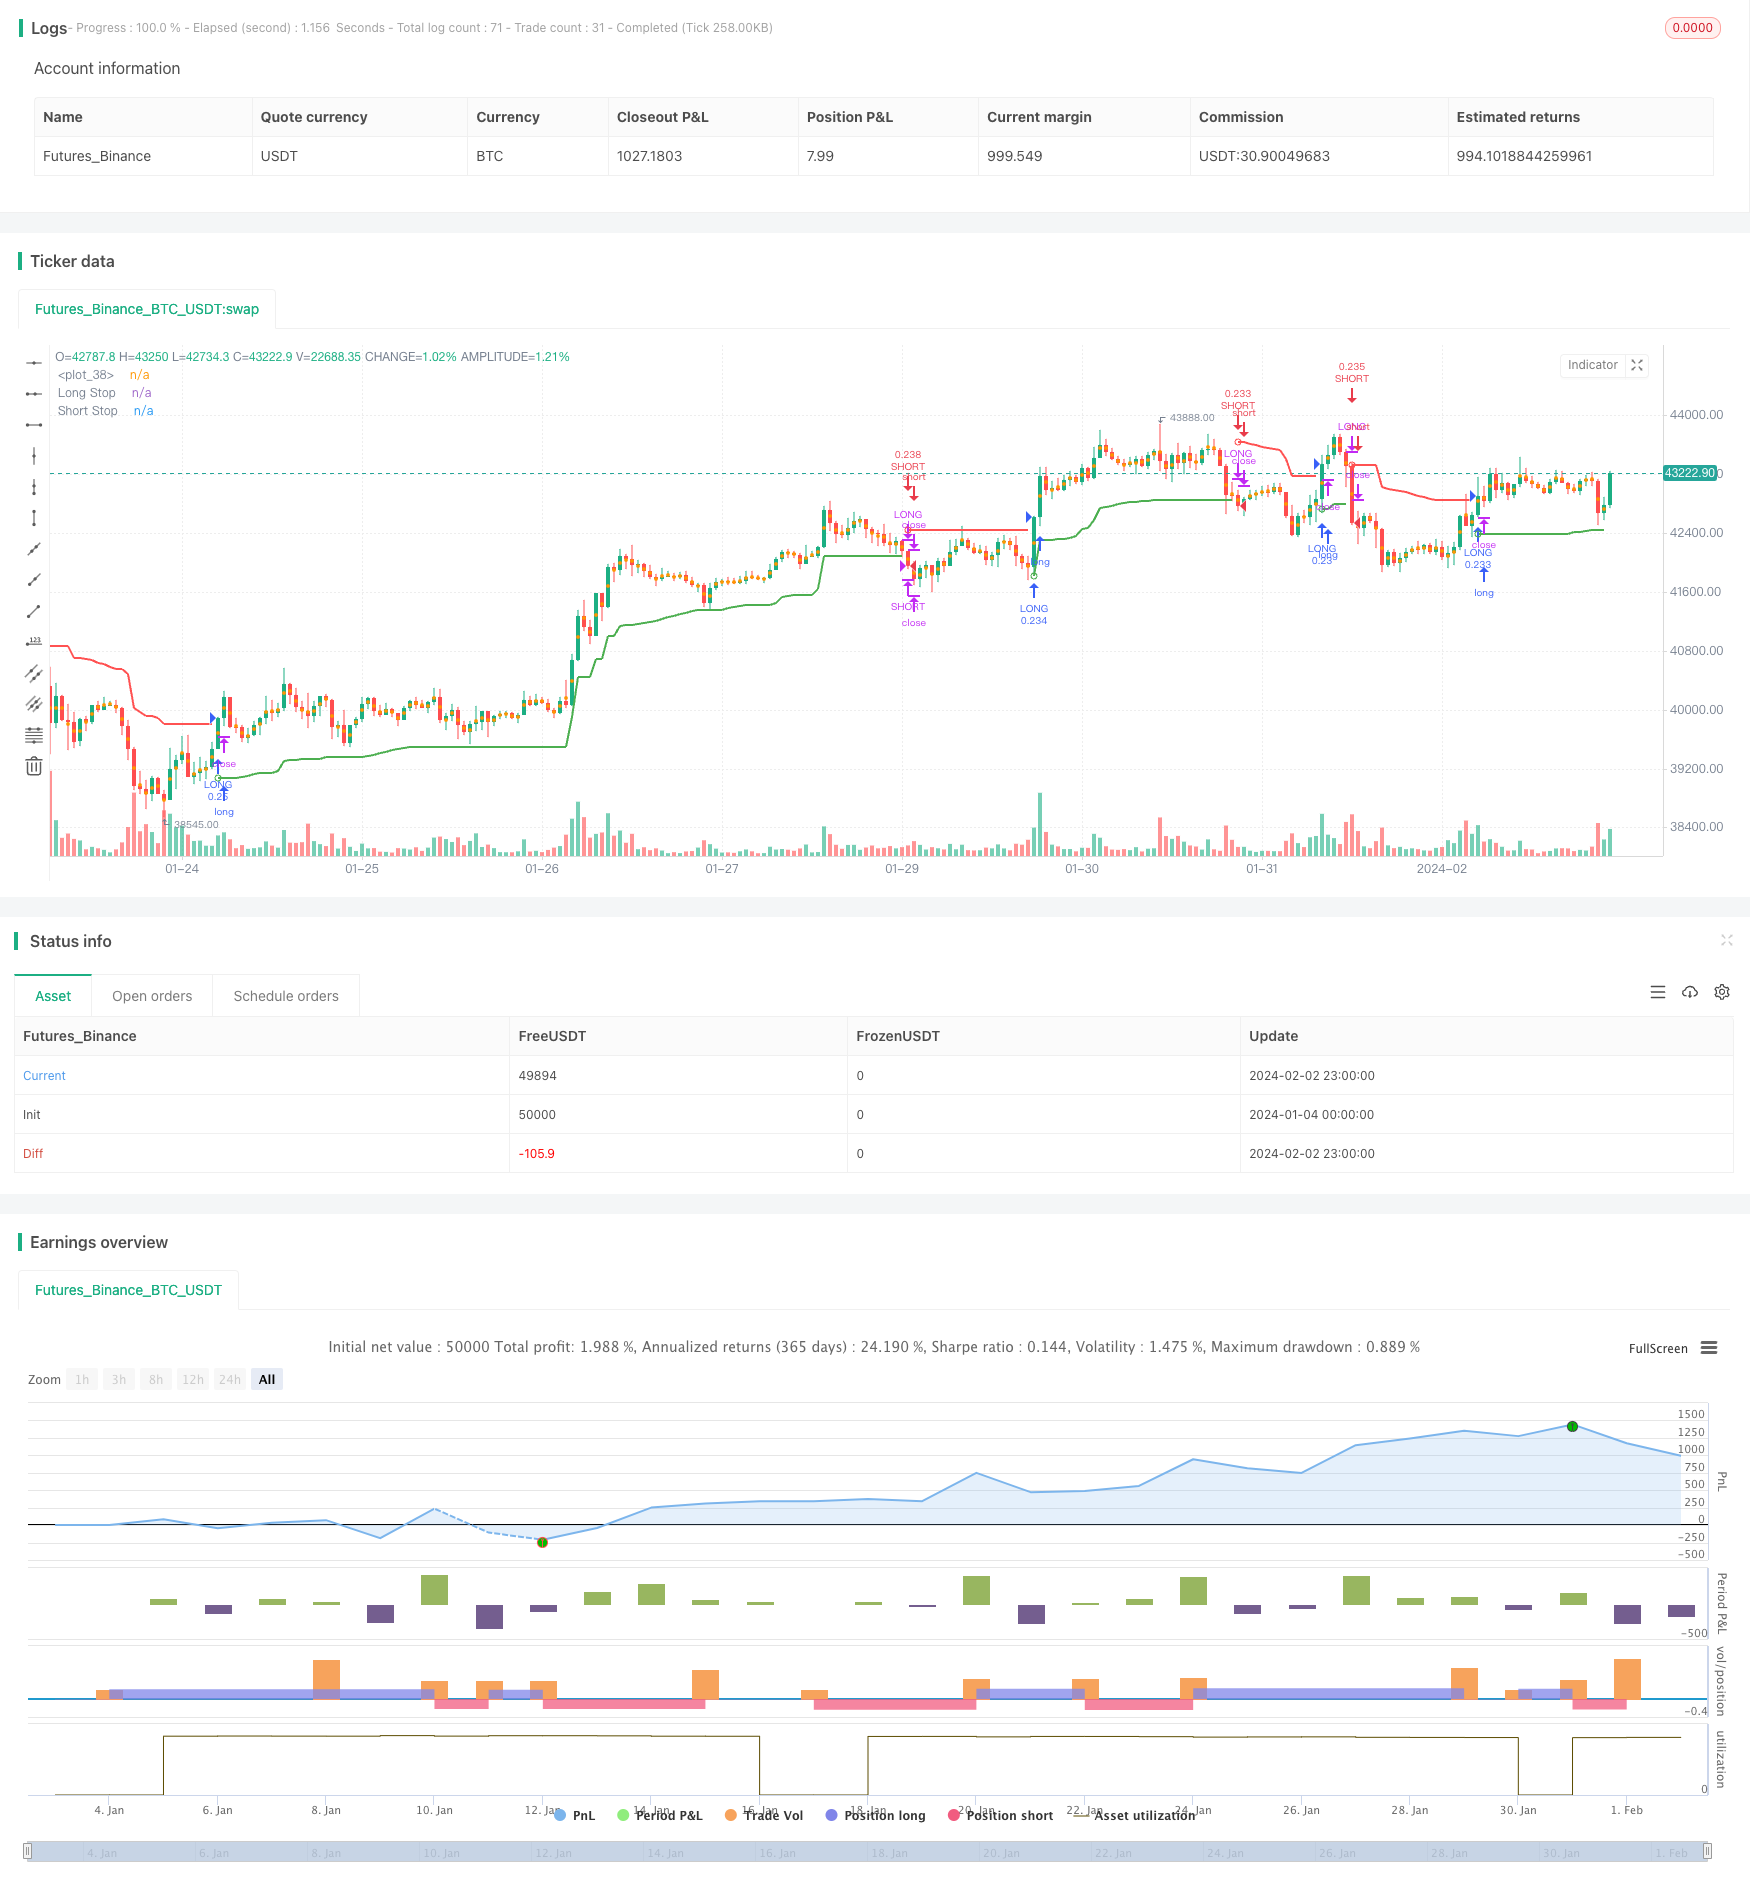
The main idea of this strategy is to calculate the long and short stop-loss lines based on the ATR indicator. It generates trading signals when the price breaks through these stop-loss lines. It has both trend…
Overview
The main idea of this strategy is to calculate the long and short stop-loss lines based on the ATR indicator. It generates trading signals when the price breaks through these stop-loss lines. It has both trend tracking and oscillation capturing capabilities.
Strategy Principle
The strategy uses the N-period ATR multiplied by a coefficient to calculate the long and short stop-loss lines. The specific calculation formulas are as follows:
Long Stop = Highest Price - ATR * Coefficient
Short Stop = Lowest Price + ATR * Coefficient
It goes long when the price rises and breaks through the long stop-loss line, and goes short when the price falls and breaks through the short stop-loss line. After going long or short, it will track price fluctuations in real time to move the stop-loss lines.
By using the ATR band as the stop-loss level, this method can fully capture the price trend while ensuring the stop-loss risk. It generates signals when there is a significant breakthrough in price, which can effectively filter out false breakouts.
Advantage Analysis
The biggest advantage of this strategy is that it can automatically adjust the stop-loss level to capture price trends while controlling risks. The specific advantages are as follows:
The floating stop-loss based on the ATR indicator can adjust the stop-loss range according to market volatility to effectively control single loss.
Adopting a breakthrough method to generate signals can filter out some noise and avoid chasing peaks and bottoms.
Real-time adjustment of stop-loss lines to track price fluctuations prevents the stop-loss from being too loose and locks in more profits.
Risk Analysis
The strategy also has some risks, mainly concentrated in the setting of stop-loss level and signal generation. The specific risk points are:
Improper ATR cycle and coefficients may lead to excessively wide or narrow stop-loss.
The breakthrough signal method may miss early trend opportunities.
There may be some lag in stop-loss tracking during trend ending, unable to perfectly exit.
The countermeasures are mainly to adjust the parameters to make the stop-loss more reasonable, or assist with other indicators to determine the trend and signals.
Optimization Directions
The strategy can be further optimized in the following aspects:
Set up a second-layer stop-loss to further control risks.
Combine other indicators to determine the trend and improve signal quality.
Add moving stop-profit strategies to increase profit when the trend further continues.
Optimize ATR cycle and coefficient parameters to make stop-loss closer to actual price fluctuations.
Summary
Overall, this strategy is very practical. It can effectively control risks by automatically adjusting the stop-loss level, while obtaining good profits through trend tracking. We can further optimize and improve the strategy by combining other analytical methods on the existing basis to make it more stable and intelligent.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 22 | ATR Period |
| v_input_2 | 3 | ATR Multiplier |
| v_input_3 | false | Show Buy/Sell Labels ? |
| v_input_4 | true | Use Close Price for Extremums ? |
| v_input_5 | true | Highlight State ? |
| v_input_6 | true | (?Strategy Settings)Long-Short |
| v_input_7 | timestamp(2019-01-01) | Date |
| v_input_8 | timestamp(2025-01-01) | Date |
| v_input_9 | 5 | Manuel Stop Loss Ratio |
| v_input_10 | 20 | Take Profit Ratio |
| v_input_11 | 10 | Trailing Stop Start Ratio |
| v_input_12 | 5 | Trailing Stop Ratio |
Source Pine Script
/*backtest
start: 2024-01-04 00:00:00
end: 2024-02-03 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © melihtuna
//@version=4
strategy("Chandelier Exit - Strategy",shorttitle="CE-STG" , overlay=true, default_qty_type=strategy.cash, default_qty_value=10000, initial_capital=10000, currency=currency.USD, commission_value=0.03, commission_type=strategy.commission.percent)

length = input(title="ATR Period", type=input.integer, defval=22)
mult = input(title="ATR Multiplier", type=input.float, step=0.1, defval=3.0)
showLabels = input(title="Show Buy/Sell Labels ?", type=input.bool, defval=false)
useClose = input(title="Use Close Price for Extremums ?", type=input.bool, defval=true)
highlightState = input(title="Highlight State ?", type=input.bool, defval=true)

atr = mult * atr(length)

longStop = (useClose ? highest(close, length) : highest(length)) - atr
longStopPrev = nz(longStop[1], longStop)
longStop := close[1] > longStopPrev ? max(longStop, longStopPrev) : longStop

shortStop = (useClose ? lowest(close, length) : lowest(length)) + atr
shortStopPrev = nz(shortStop[1], shortStop)
shortStop := close[1] < shortStopPrev ? min(shortStop, shortStopPrev) : shortStop

var int dir = 1
dir := close > shortStopPrev ? 1 : close < longStopPrev ? -1 : dir

var color longColor = color.green
var color shortColor = color.red

longStopPlot = plot(dir == 1 ? longStop : na, title="Long Stop", style=plot.style_linebr, linewidth=2, color=longColor)
buySignal = dir == 1 and dir[1] == -1
plotshape(buySignal ? longStop : na, title="Long Stop Start", location=location.absolute, style=shape.circle, size=size.tiny, color=longColor, transp=0)
plotshape(buySignal and showLabels ? longStop : na, title="Buy Label", text="Buy", location=location.absolute, style=shape.labelup, size=size.tiny, color=longColor, textcolor=color.white, transp=0)

shortStopPlot = plot(dir == 1 ? na : shortStop, title="Short Stop", style=plot.style_linebr, linewidth=2, color=shortColor)
sellSignal = dir == -1 and dir[1] == 1
plotshape(sellSignal ? shortStop : na, title="Short Stop Start", location=location.absolute, style=shape.circle, size=size.tiny, color=shortColor, transp=0)
plotshape(sellSignal and showLabels ? shortStop : na, title="Sell Label", text="Sell", location=location.absolute, style=shape.labeldown, size=size.tiny, color=shortColor, textcolor=color.white, transp=0)

midPricePlot = plot(ohlc4, title="", style=plot.style_circles, linewidth=0, display=display.none, editable=false)

longFillColor = highlightState ? (dir == 1 ? longColor : na) : na
shortFillColor = highlightState ? (dir == -1 ? shortColor : na) : na
fill(midPricePlot, longStopPlot, title="Long State Filling", color=longFillColor)
fill(midPricePlot, shortStopPlot, title="Short State Filling", color=shortFillColor)


long_short = input(true, "Long-Short",type=input.bool, group="Strategy Settings")

start     = input(timestamp("2019-01-01"), "Date", type=input.time, group="Strategy Settings")
finish    = input(timestamp("2025-01-01"), "Date", type=input.time, group="Strategy Settings")
window()  => true

slRatio=input(5, "Manuel Stop Loss Ratio", type=input.float, minval=0, group="Strategy Settings")
tpRatio=input(20, "Take Profit Ratio", type=input.float, minval=0, group="Strategy Settings")
tsStartRatio=input(10, "Trailing Stop Start Ratio", type=input.float, minval=0, group="Strategy Settings")
tsRatio=input(5, "Trailing Stop Ratio", type=input.float, minval=1, group="Strategy Settings")

lastBuyPrice = strategy.position_avg_price

diffHiPriceRatio = (high-lastBuyPrice)/lastBuyPrice*100
diffLoPriceRatio = (close-lastBuyPrice)/lastBuyPrice*100
posHiRatio=0.0
posHiRatio:= strategy.position_size > 0 ? diffHiPriceRatio > posHiRatio[1] ? diffHiPriceRatio : posHiRatio[1] : 0

s_diffHiPriceRatio = (low-lastBuyPrice)/lastBuyPrice*100
s_diffLoPriceRatio = (close-lastBuyPrice)/lastBuyPrice*100
s_posHiRatio=0.0
s_posHiRatio:= strategy.position_size < 0 ? s_diffLoPriceRatio < s_posHiRatio[1] ? s_diffLoPriceRatio : s_posHiRatio[1] : 0

strategy.entry("LONG", strategy.long, when = window() and buySignal)
strategy.close("LONG", when = window() and sellSignal)
strategy.close("LONG", when = diffLoPriceRatio<(slRatio*(-1)), comment="STOP-LONG")
strategy.close("LONG", when = diffHiPriceRatio>tpRatio, comment="TAKE-PROFIT-LONG")
strategy.close("LONG", when = ((posHiRatio[1]>tsStartRatio) and (posHiRatio[1]-diffHiPriceRatio)>tsRatio), comment="TRAILING-STOP-LONG")

if long_short
    strategy.entry("SHORT", strategy.short, when = window() and sellSignal)
    strategy.close("SHORT", when = window() and buySignal)
    strategy.close("SHORT", when = s_diffLoPriceRatio>(slRatio), comment="STOP-SHORT")
    strategy.close("SHORT", when = s_diffHiPriceRatio<(tpRatio*(-1)), comment="TAKE-PROFIT-SHORT")
strategy.close("SHORT", when = ((s_posHiRatio[1]*(-1)>tsStartRatio) and ((s_posHiRatio[1]-s_diffLoPriceRatio))*(-1)>tsRatio), comment="TRAILING-STOP-SHORT")Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Isolation-Band-Oscillation-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d