Strategy vault / Trend following
K Consecutive Candles Bull Bear Strategy
This strategy determines bull or bear markets based on the number of consecutive up or down candles and makes trades accordingly. When the closing price is consecutively higher than the previous candle's close for a…
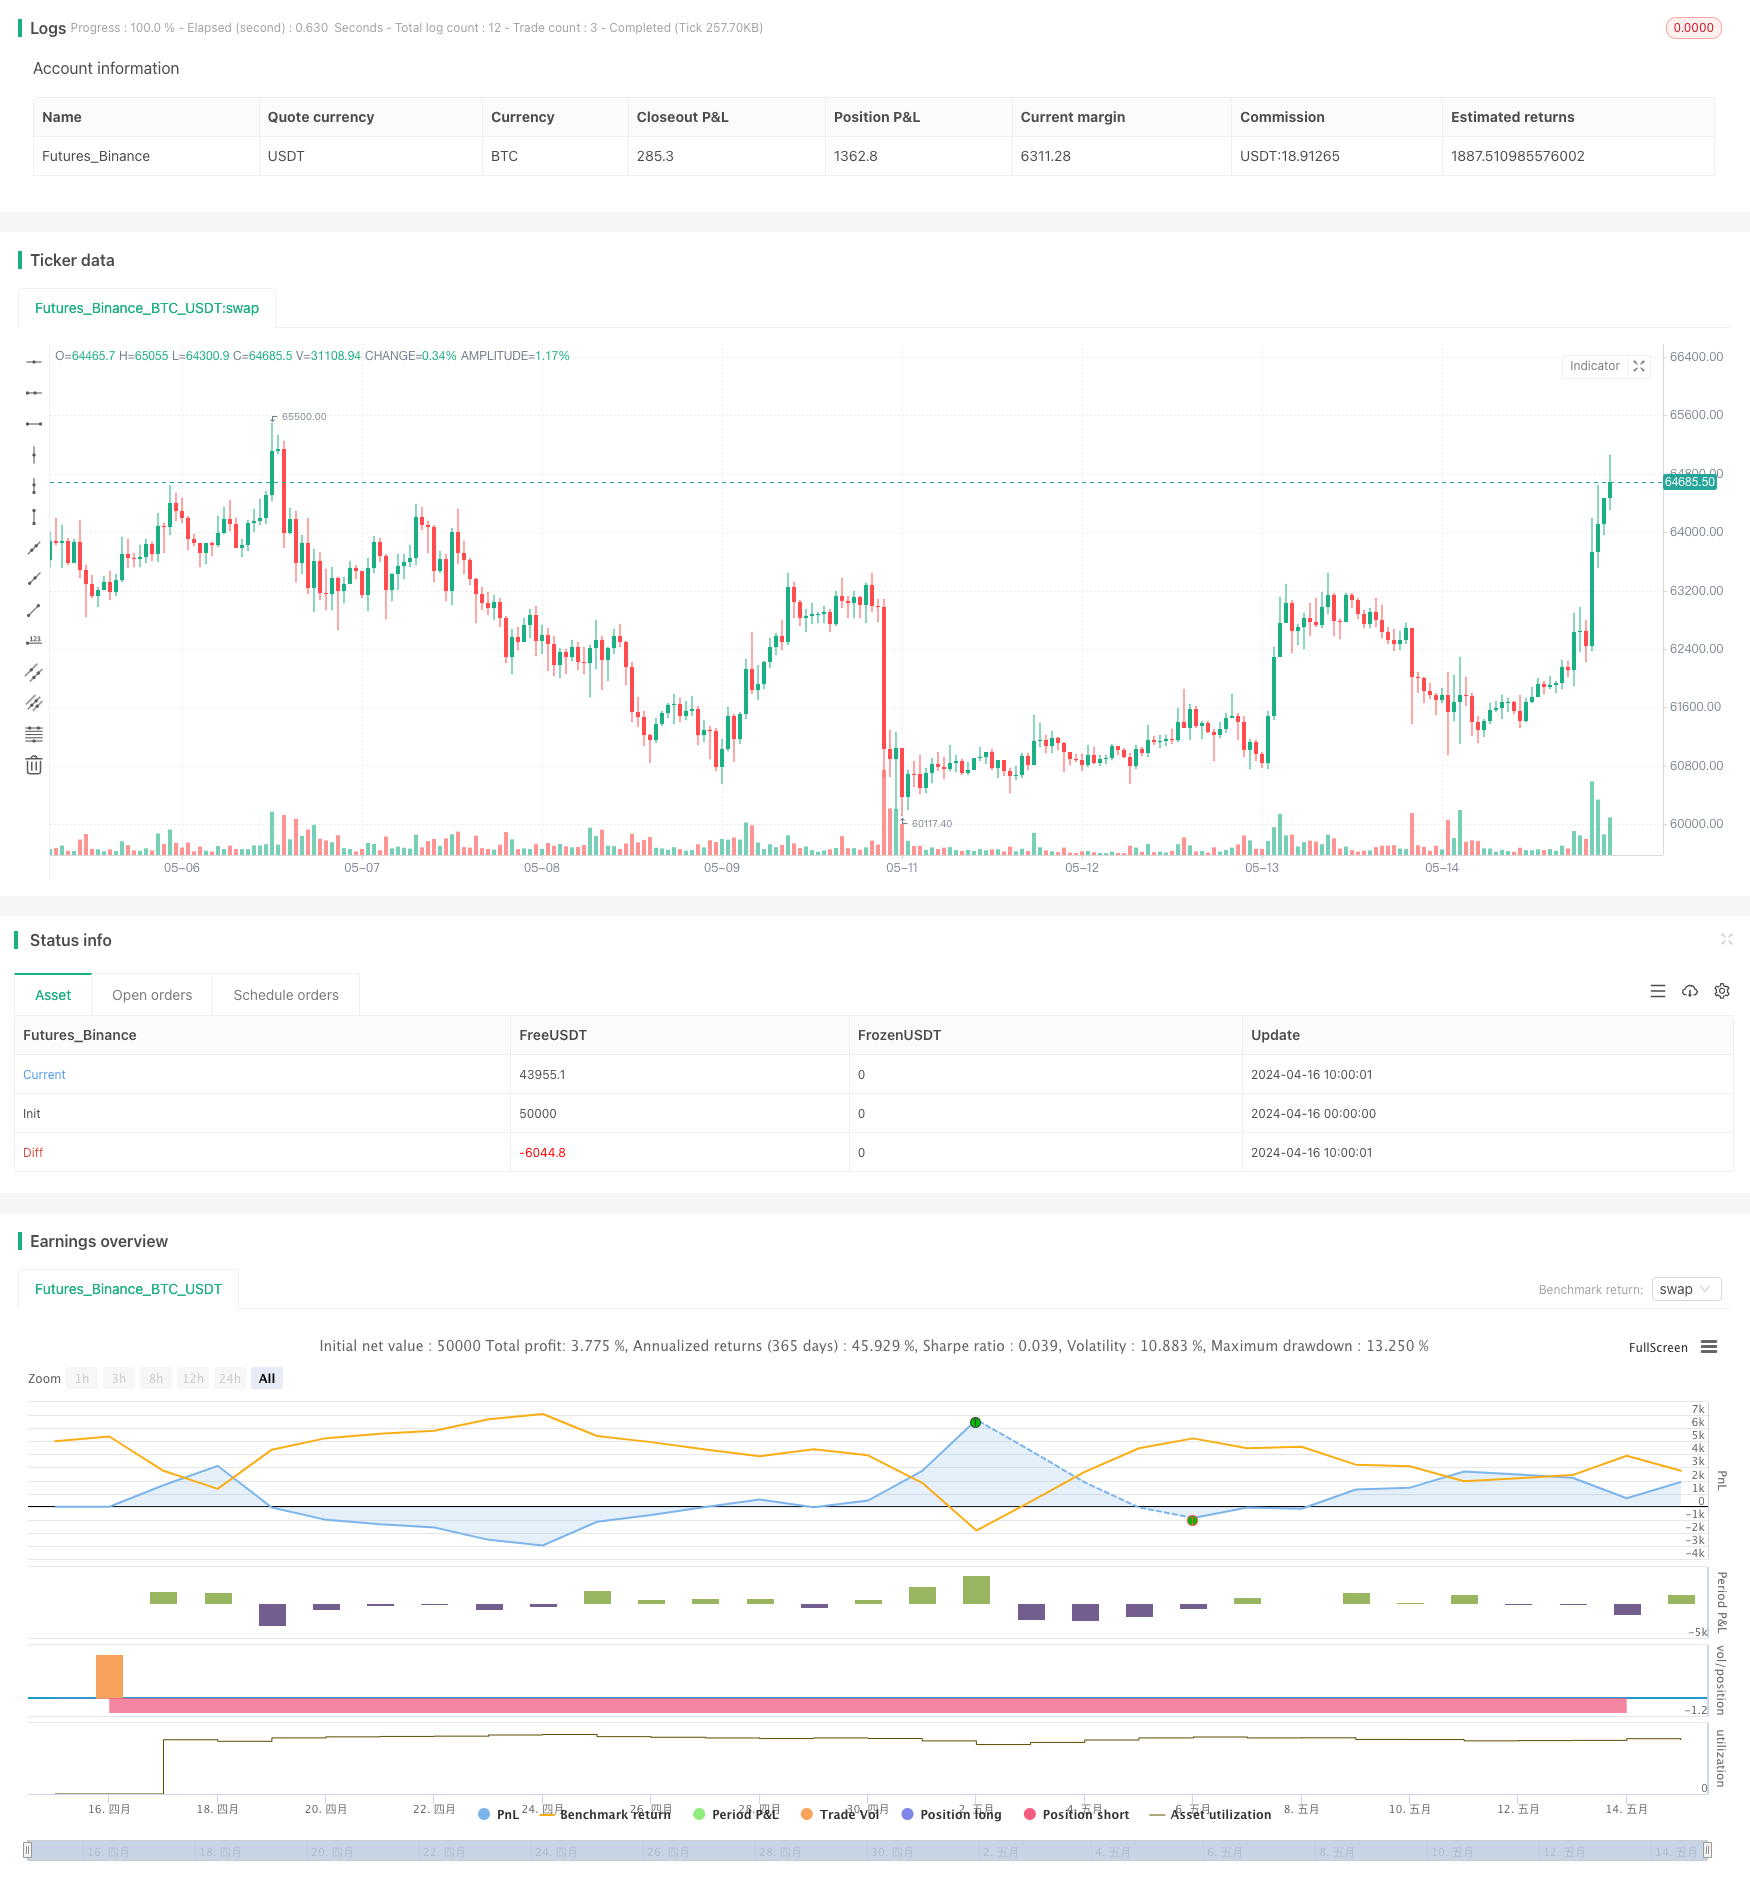
Overview
This strategy determines bull or bear markets based on the number of consecutive up or down candles and makes trades accordingly. When the closing price is consecutively higher than the previous candle's close for a specified number of times, it enters a long position; when the closing price is consecutively lower than the previous candle's close for a specified number of times, it enters a short position. Stop loss and take profit are set, and a trailing stop mechanism is introduced to protect profits.
Strategy Principle
- Record the number of times the consecutive bullish and bearish conditions are met. If the close is higher than the previous candle, the bullish count increases by 1 and the bearish count resets to 0; if the close is lower, the bearish count increases by 1 and the bullish count resets to 0; otherwise, both counts reset to 0.
- When the bullish count reaches the specified number k, enter a long position with stop loss and take profit.
- For long positions, record the highest price after entry. When the highest price exceeds the entry price by iTGT minimum price variation units and the close pulls back below the highest price by iPcnt%, close the position.
- When the bearish count reaches the specified number k2, enter a short position with stop loss and take profit.
- For short positions, record the lowest price after entry. When the lowest price is lower than the entry price by iTGT minimum price variation units and the close rebounds above the lowest price by iPcnt%, close the position.
Strategy Advantages
- Simple and easy to understand, making trading decisions based on the continuity of candles with clear logic.
- Introduces a trailing stop mechanism to actively protect profits after the price moves a certain distance in the favorable direction.
- Setting stop loss and take profit can effectively control risks and lock in profits.
- Adjustable parameters to suit different markets and trading styles.
Strategy Risks
- In choppy markets, frequent opening and closing of positions may lead to large slippage costs.
- The judgment of consecutive candle numbers is affected by market noise, which may result in frequent signals.
- Fixed stop loss and take profit levels may not adapt to changes in market volatility.
Strategy Optimization Directions
- Introduce more technical indicators, such as moving averages and volatility, to assist in judging the strength and direction of trends.
- Optimize the trigger conditions for the trailing stop, such as adjusting the pullback percentage based on ATR.
- Adopt more dynamic stop loss and take profit methods, such as trailing stops and stepped take profits.
- Optimize parameters to find the optimal combination for different markets and instruments.
Summary
This strategy captures bull and bear trends through the continuity of candles while setting stop loss and take profit to control risks. The introduction of a trailing stop can better protect profits. However, it may generate frequent signals in choppy markets, requiring further optimization of signal reliability. In addition, the setting of stop loss and take profit can be more flexible to adapt to dynamic market changes. Overall, the strategy has a simple and clear idea, suitable for trending markets, but there is still room for optimization.
Source Pine Script
/*backtest
start: 2024-04-16 00:00:00
end: 2024-05-16 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("K Consecutive Candles Counting Treasure (or traditional counting song)V2", max_bars_back=300, overlay=true)

// Define user input
k = input.int(3, title="Number of Consecutive Candles for Long", minval=1)
k2 = input.int(3, title="Number of Consecutive Candles for Short", minval=1)
stopLossTicks = input.int(500, title="Stop Loss (Ticks)")
takeProfitTicks = input.int(500, title="Take Profit (Ticks)")
iTGT = input.int(200,"iTGT")  // Move Take Profit Point
iPcnt = input.int(50,"iPcnt")  // Trailing Take Profit%

var float TrailValue = 0
var float TrailExit = 0
var float  vMP = 0

BarsSinceEntry = ta.barssince(strategy.position_size == 0)

vMP := strategy.position_size

// Create a dictionary with key-value pairs
addArrayData(type, value) =>
    alert_array = array.new_string()
    array.push(alert_array, '"timenow": ' + str.tostring(timenow))
    array.push(alert_array, '"seqNum": ' + str.tostring(value))
    array.push(alert_array, '"type": "' + type + '"')
    alertstring = '{' + array.join(alert_array,', ') + '}'


// Define conditional variables
var int countLong = 0  // Record the number of times the continuous long condition is true
var int countShort = 0 // Record the number of times the continuous short condition is true

// Calculate the number of consecutive closing prices greater or less than the previous one
if close > close[1]
    countLong += 1
    countShort := 0 // Reset short count
else if close < close[1]
    countShort += 1
    countLong := 0 // Reset long count
else
    countLong := 0
    countShort := 0

// Conditions for opening a long position
if countLong >= k
    strategy.entry("Long Entry", strategy.long)
    strategy.exit("Exit Long", "Long Entry", loss=stopLossTicks, profit=takeProfitTicks)


if vMP>0
    TrailValue := ta.highest(high,BarsSinceEntry)
    TrailExit := TrailValue - iPcnt*0.01*(TrailValue - strategy.position_avg_price)
    if TrailValue > strategy.position_avg_price + iTGT * syminfo.minmove/syminfo.pricescale and close < TrailExit

        strategy.close("Long Entry", comment = "Trl_LX"+ str.tostring(close[0]))
// Conditions for opening a short position
if countShort >= k2
    strategy.entry("Short Entry", strategy.short)
    strategy.exit("Exit Short", "Short Entry", loss=stopLossTicks, profit=takeProfitTicks)

if vMP<0
    TrailValue := ta.lowest(low,BarsSinceEntry)
    TrailExit := TrailValue - iPcnt*0.01*(TrailValue - strategy.position_avg_price)
    if TrailValue < strategy.position_avg_price - iTGT * syminfo.minmove/syminfo.pricescale and close > TrailExit

        strategy.close("short60", comment = "Trl_SX"+ str.tostring(close[0]))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-05-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/K-Consecutive-Candles-Bull-Bear-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h