Strategy vault / Machine learning
KNN Based Adaptive Parametric Trend Following Strategy
This strategy is an adaptive parametric trend following system based on the K-Nearest Neighbors (KNN) machine learning algorithm. The strategy dynamically adjusts trend following parameters through the KNN algorithm…
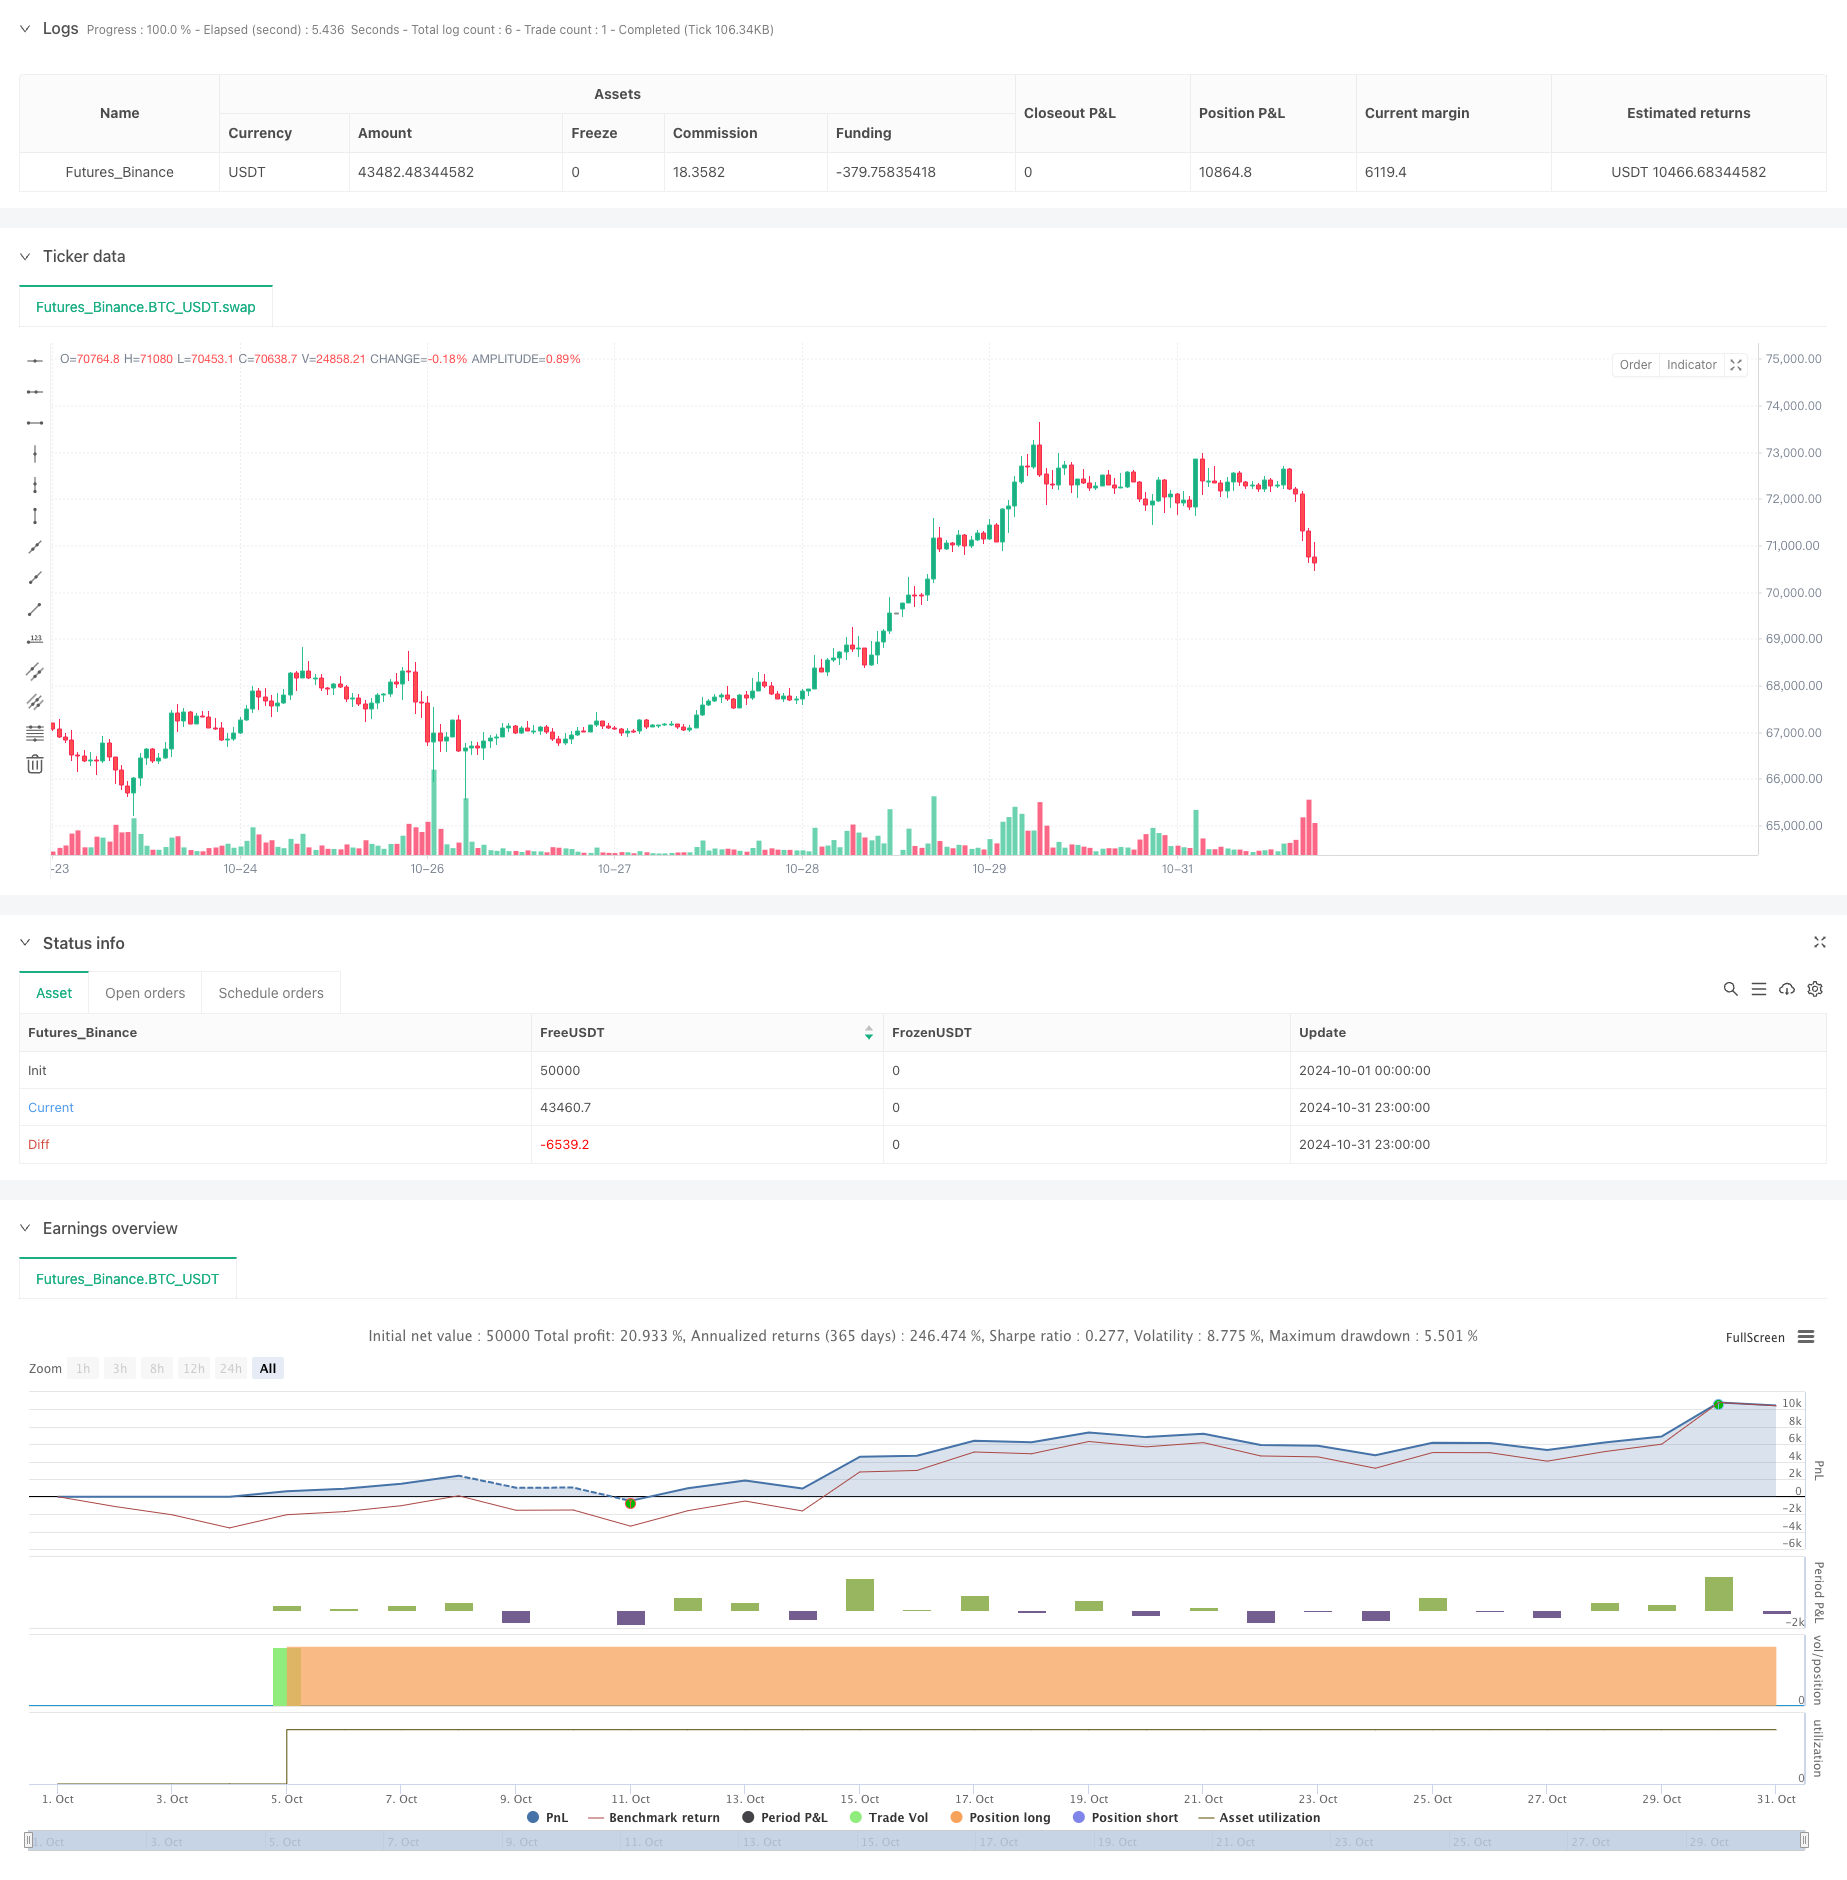
Overview
This strategy is an adaptive parametric trend following system based on the K-Nearest Neighbors (KNN) machine learning algorithm. The strategy dynamically adjusts trend following parameters through the KNN algorithm and generates trading signals in combination with moving averages. The system can automatically adjust strategy parameters based on changes in market conditions, improving strategy adaptability and stability. This strategy combines machine learning methods to optimize traditional trend following strategies, representing a fusion of technology and innovation in quantitative investment.
Strategy Principle
The core principle of the strategy is to analyze historical price data using the KNN algorithm and predict price trends by calculating the similarity between current market conditions and historical data. The specific implementation steps are:
- Set observation window size and K value, collect historical price data to form feature vectors
- Calculate Euclidean distance between current price sequence and historical data
- Select K most similar historical price sequences as neighbor samples
- Analyze subsequent price movements of these K neighbor samples
- Generate trading signals based on average price changes of neighbor samples combined with moving averages When the average price change of K neighbor samples is positive and current price is above the moving average, the system generates long signals; otherwise, it generates short signals.
Strategy Advantages
- Strong adaptability: KNN algorithm can automatically adjust parameters based on market environment changes
- Multi-dimensional analysis: Combines machine learning algorithms and technical indicators for more comprehensive market analysis
- Reasonable risk control: Uses moving averages as auxiliary confirmation to reduce impact of false signals
- Clear computational logic: Strategy execution process is transparent and easy to understand and optimize
- Flexible parameters: K value and window size can be adjusted according to different market environments
Strategy Risks
- High computational complexity: KNN algorithm requires calculating large amounts of historical data
- Parameter sensitivity: Choice of K value and window size significantly impacts strategy performance
- Market environment dependence: Reference value of historical similarity may decrease in volatile markets
- Overfitting risk: Over-reliance on historical data may lead to strategy overfitting
- Delay risk: Signal lag may exist due to need for sufficient historical data collection
Strategy Optimization Directions
- Feature Engineering Optimization:
- Add more technical indicators as features
- Introduce market sentiment indicators
- Optimize feature standardization methods
- Algorithm Efficiency Improvement:
- Optimize nearest neighbor search using KD-trees
- Implement parallel computing
- Optimize data storage and access methods
- Risk Control Enhancement:
- Add stop-loss and take-profit mechanisms
- Introduce volatility filters
- Design dynamic position management system
- Parameter Optimization Solutions:
- Implement adaptive K value selection
- Dynamically adjust observation window size
- Optimize moving average periods
- Signal Generation Mechanism Improvement:
- Introduce signal strength scoring system
- Design signal confirmation mechanism
- Optimize entry and exit timing
Summary
This strategy innovatively applies the KNN algorithm to trend following trading, optimizing traditional technical analysis strategies through machine learning methods. The strategy possesses strong adaptability and flexibility, capable of dynamically adjusting parameters based on market conditions. Although risks such as high computational complexity and parameter sensitivity exist, the strategy still has good application value through reasonable optimization and risk control measures. It is recommended that investors adjust parameters according to market characteristics and combine other analysis methods for trading decisions in practical applications.
Source Pine Script
/*backtest
start: 2024-10-01 00:00:00
end: 2024-10-31 23:59:59
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("Trend Following Strategy with KNN", overlay=true,commission_value=0.03,currency='USD', commission_type=strategy.commission.percent,default_qty_type=strategy.cash)


// Input parameters
k = input.int(5, title="K (Number of Neighbors)", minval=1)  // Number of neighbors for KNN algorithm
window_size = input.int(20, title="Window Size", minval=1)  // Window size for feature vector calculation
ma_length = input.int(50, title="MA Length", minval=1)  // Length of the moving average

// Calculate moving average
ma = ta.sma(close, ma_length)

// Initialize variables
var float[] features = na
var float[] distances = na
var int[] nearest_neighbors = na

if bar_index >= window_size - 1  // Ensure there is enough historical data
    features := array.new_float(0)  // Keep only the current window data
    for i = 0 to window_size - 1
        array.push(features, close[i])

    // Calculate distances
    distances := array.new_float(0)  // Clear the array for each calculation
    for i = 0 to window_size - 1  // Calculate the distance between the current price and all prices in the window
        var float distance = 0.0
        for j = 0 to window_size - 1
            distance += math.pow(close[j] - array.get(features, j), 2)
        distance := math.sqrt(distance)
        array.push(distances, distance)

    // Find the nearest neighbors
    if array.size(distances) > 0 and array.size(distances) >= k
        nearest_neighbors := array.new_int(0)
        for i = 0 to k - 1
            var int min_index = -1
            var float min_distance = na
            for j = 0 to array.size(distances) - 1
                if na(min_distance) or array.get(distances, j) < min_distance
                    min_index := j
                    min_distance := array.get(distances, j)
            if min_index != -1
                array.push(nearest_neighbors, min_index)
                array.remove(distances, min_index)  // Remove the processed neighbor

    // Calculate the average price change of the neighbors
    var float average_change = 0.0
    if array.size(nearest_neighbors) > 0
        for i = 0 to array.size(nearest_neighbors) - 1
            var int index = array.get(nearest_neighbors, i)
            // Ensure index + 1 is within range
            if index + 1 < bar_index
                average_change += (close[index] - close[index + 1])
        average_change := average_change / array.size(nearest_neighbors)

    // Generate trading signals
    if average_change > 0 and close > ma
        strategy.entry("Long", strategy.long)
    else if average_change < 0 and close < ma
        strategy.entry("Short", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/KNN-Based-Adaptive-Parametric-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h