Strategy vault / Machine learning
Leveraged Position Sizing with Margin Call Risk Management Strategy
This strategy manages risk by setting high leverage and margin call conditions to close positions during significant market fluctuations.
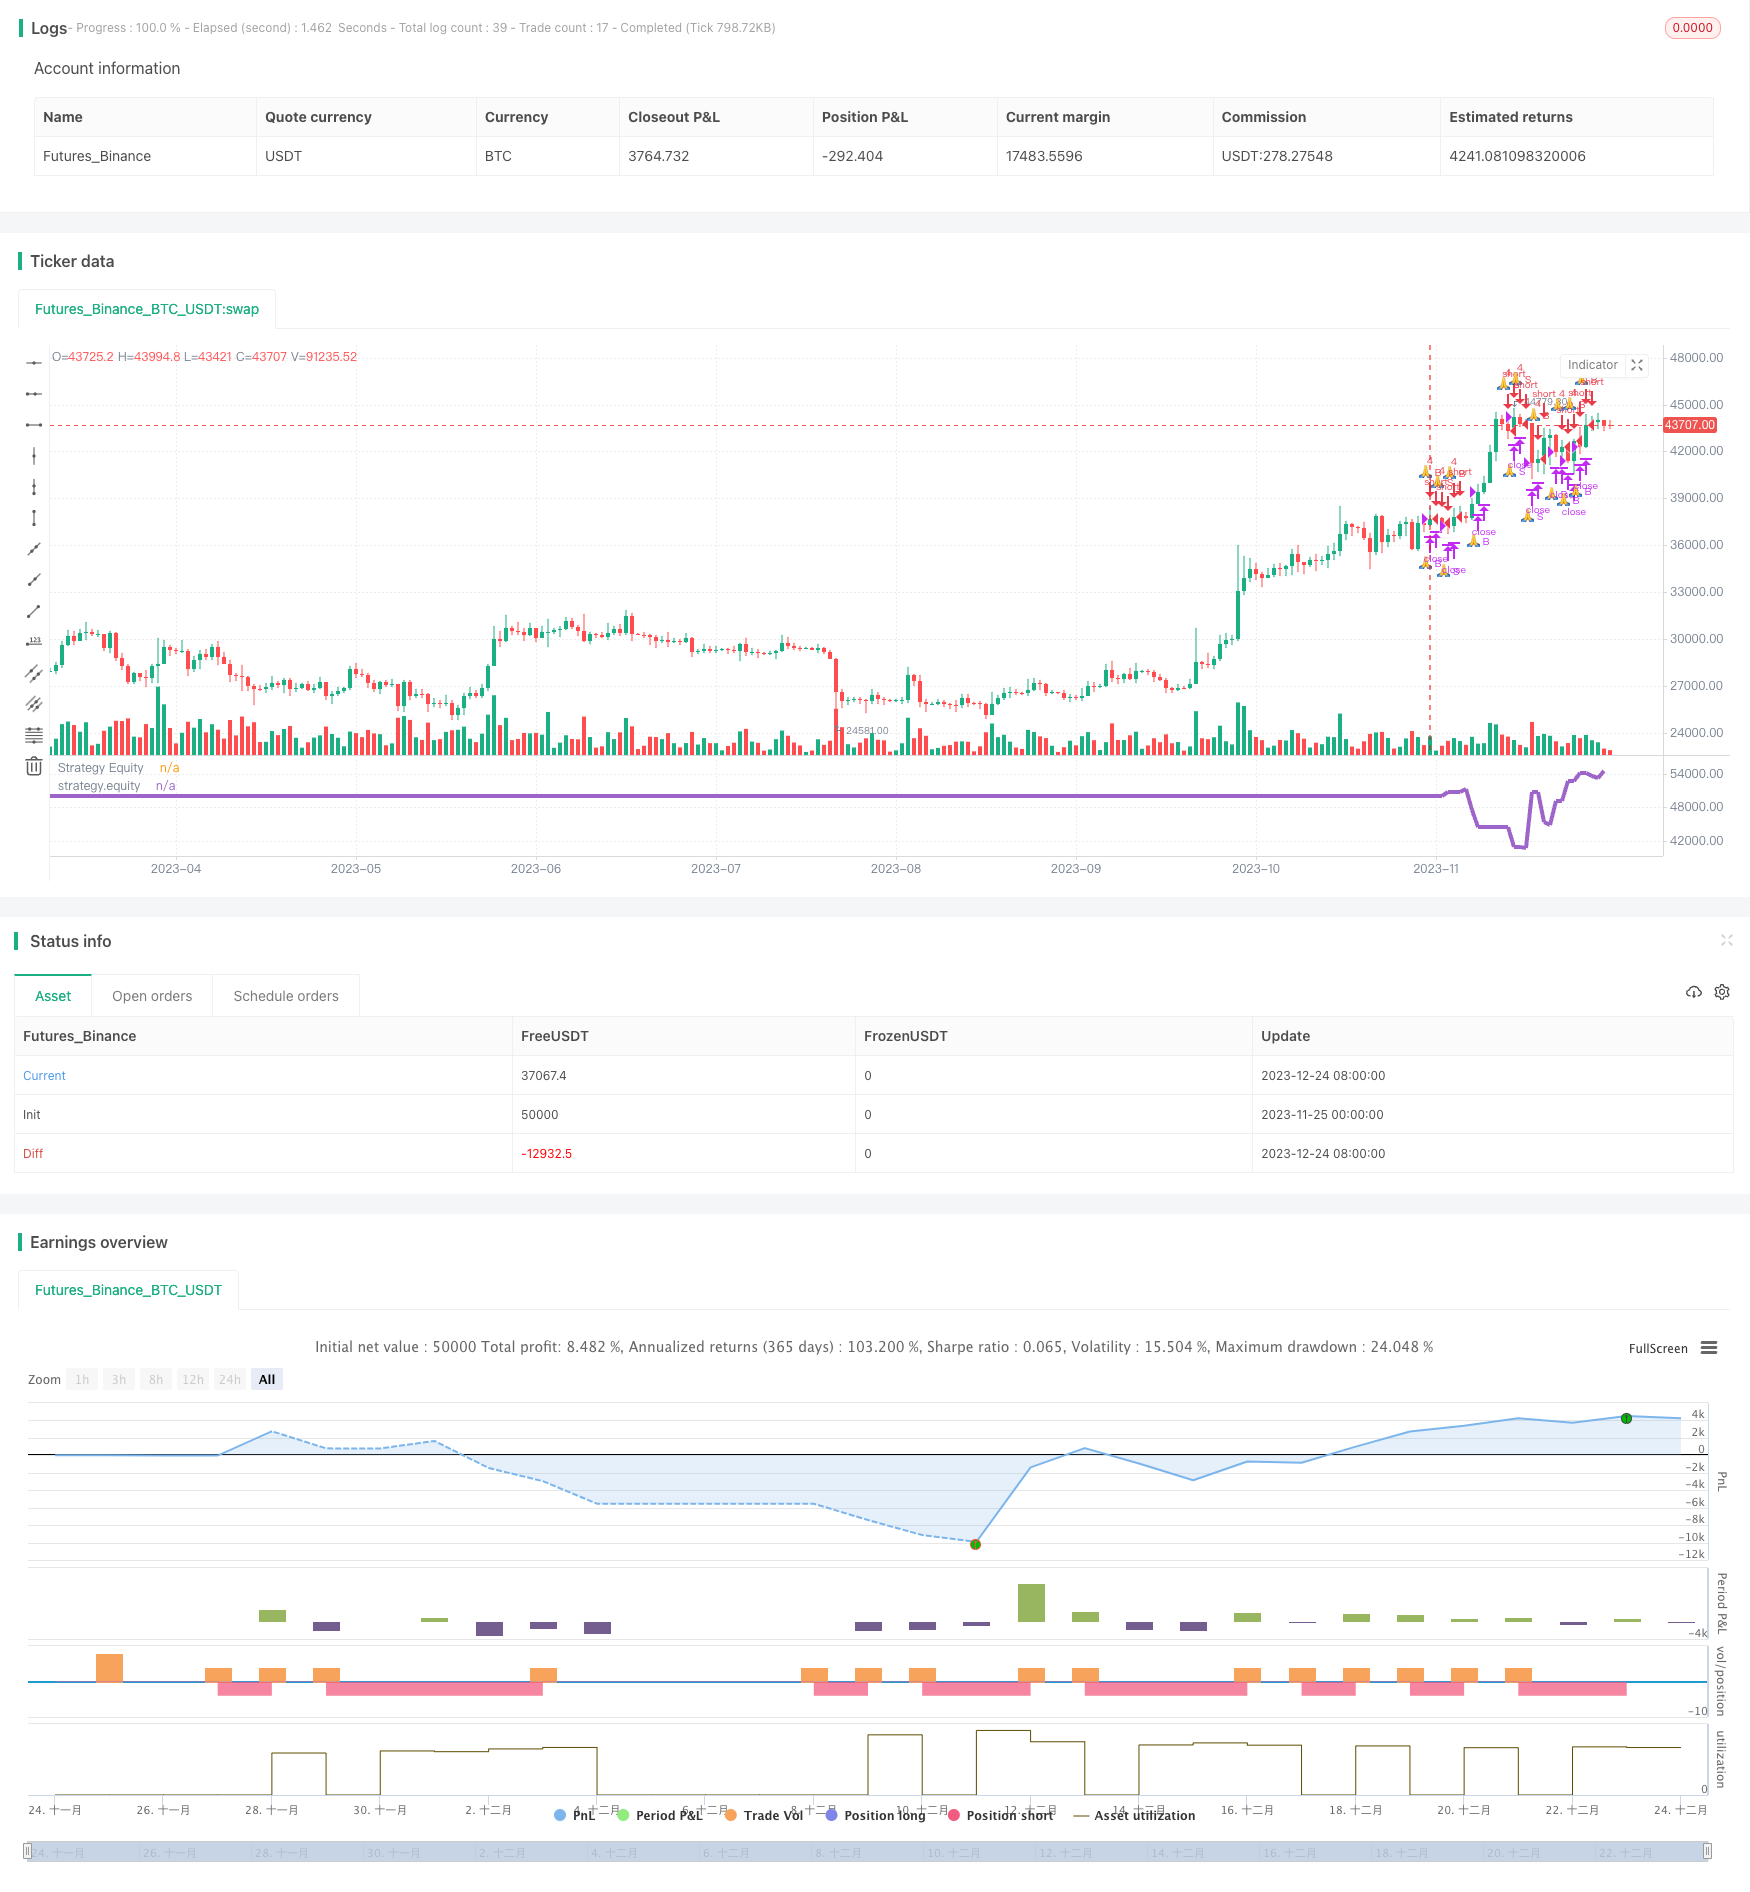
Overview
This strategy manages risk by setting high leverage and margin call conditions to close positions during significant market fluctuations.
Strategy Logic
- Set high leverage, e.g. 4x
- Define margin call level, e.g. $25,000
- Stop opening new trades when equity falls below margin call level
- Close all positions when margin call triggered as equity continues dropping
By doing so, the strategy can cut losses in time during drastic market moves to prevent margin call risks.
Advantages Analysis
- Flexible leverage customization based on personal risk tolerance
- Margin call mechanism prevents account blowups
- Timely stop loss with high leverage to mitigate risks
Risk Analysis
- Leverage amplifies both profits and risks
- Margin call level needs alignment with stop loss
- Stop loss subject to slippage risks
Risks can be reduced by adjusting leverage, aligning margin call and stop loss, optimizing stop loss, etc.
Optimization Directions
- Add trend filter to avoid counter-trend trades
- Optimize stop loss to prevent slippages
- Set trading hour filters to avoid trades in certain sessions
- Incorporate machine learning models to dynamically tune parameters
Summary
The strategy manages risk with leverage and margin call settings to prevent account blowups. However, high leverage also increases risks. Additional efforts like trend validation, stop loss optimization and trading hour control can help further reduce risks. Complex techniques like machine learning can also be leveraged to dynamically optimize parameters and strike a balance between profitability and risk management.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Use Margin Call? |
| v_input_2 | 25000 | Margin Value |
| v_input_3 | true | Use Leverage |
| v_input_4 | 4 | Leverage mult (1 for no leverage) |
| v_input_5 | true | Use Risk Management? |
| v_input_6 | 5 | Stop Loss in ticks value |
| v_input_7 | 500 | Take Profit in ticks value |
| v_input_8 | true | [LABEL] DATE |
| v_input_9 | 2019 | From Year |
| v_input_10 | 12 | From Month |
| v_input_11 | true | From Day |
| v_input_12 | 2019 | To Year |
| v_input_13 | 12 | To Month |
| v_input_14 | 9 | To Day |
Source Pine Script
/*backtest
start: 2023-11-25 00:00:00
end: 2023-12-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
//@version=4
//@author=Daveatt

// Breakout on 2H high/low break Strategy

SystemName = "Leverage Strategy"
TradeId = "?"

InitCapital             = 100000
InitPosition            = 1
UseMarginCall           = input(true, title="Use Margin Call?")
MarginValue             = input(25000, title="Margin Value", type=input.float)
// use 1 for no leverage
// use 0.1 for be underleveraged and bet 1/10th of a pip value
// use any value > 1 for full-degen mode
UseLeverage             = input(true, title="Use Leverage")
LeverageValue           = input(4, title="Leverage mult (1 for no leverage)", minval=0.1, type=input.float)
// Risk Management
UseRiskManagement       = input(true, title="Use Risk Management?")
// ticks = 1/10th of a pip value
StopLoss                = input(5, title="Stop Loss in ticks value", type=input.float)
TakeProfit              = input(500, title="Take Profit in ticks value", type=input.float)

InitCommission = 0.075
InitPyramidMax = 1
CalcOnorderFills = false
CalcOnTick = true
DefaultQtyType = strategy.cash
DefaultQtyValue = strategy.cash
Currency = currency.USD
Precision = 2
Overlay=false
MaxBarsBack=3000

strategy
 (
 title=SystemName,
 shorttitle=SystemName,
 overlay=Overlay
 )

//////////////////////////// UTILITIES ///////////////////////////

f_print(_txt, _condition) =>

    var _lbl = label(na)
    label.delete(_lbl)

    if _condition
        // saving the candle where we got rekt :(
        _index = barssince(_condition)
        _lbl := label.new(bar_index - _index, highest(100), _txt, xloc.bar_index, yloc.price, size = size.normal, style=label.style_labeldown)

//////////////////////////// STRATEGY LOGIC ///////////////////////////

// Date filterigng
_Date       = input(true, title="[LABEL] DATE")
FromYear = input(2019, "From Year", minval=1900),   FromMonth = input(12, "From Month", minval=1, maxval=12),    FromDay = input(1, "From Day", minval=1, maxval=31)
ToYear = input(2019, "To Year", minval=1900),       ToMonth = input(12, "To Month", minval=1, maxval=12),        ToDay = input(9, "To Day", minval=1, maxval=31)
FromDate = timestamp(FromYear, FromMonth, FromDay, 00, 00)
ToDate = timestamp(ToYear, ToMonth, ToDay, 23, 59)
TradeDateIsAllowed = true

// non-repainting security version
four_hours_H     = security(syminfo.tickerid, '240', high[1], lookahead=true)
four_hours_L     = security(syminfo.tickerid, '240', low[1], lookahead=true)
buy_trigger     = crossover(close, four_hours_H)
sell_trigger    = crossunder(close, four_hours_L)

// trend states
since_buy  = barssince(buy_trigger)
since_sell = barssince(sell_trigger)
buy_trend  = since_sell > since_buy
sell_trend = since_sell < since_buy

change_trend = (buy_trend and sell_trend[1]) or (sell_trend and buy_trend[1])

// plot(four_hours_H, title="4H High",  linewidth=2, color=#3c91c2, style=plot.style_linebr, transp=0,
//  show_last=1, trackprice=true)
// plot(four_hours_L, title="4H Low",  linewidth=2, color=#3c91c2, style=plot.style_linebr, transp=0,
//  show_last=1, trackprice=true)

plot(strategy.equity, color=color.blue, linewidth=3, title="Strategy Equity")

// get the entry price
entry_price = valuewhen(buy_trigger or sell_trigger, close, 0)

// SL and TP

SL_price    = buy_trend ? entry_price - StopLoss    : entry_price + StopLoss
is_SL_hit   = buy_trend ? crossunder(low, SL_price) : crossover(high, SL_price)

TP_price    = buy_trend ? entry_price + TakeProfit  : entry_price - TakeProfit
is_TP_hit   = buy_trend ? crossover(high, TP_price) : crossunder(low, TP_price)

//  Account Margin Management:
f_account_margin_call_cross(_amount)=>
    _return = crossunder(strategy.equity, _amount)

f_account_margin_call(_amount)=>
    _return = strategy.equity <= _amount

is_margin_call_cross    = f_account_margin_call_cross(MarginValue)
is_margin_call          = f_account_margin_call(MarginValue)

plot(strategy.equity, title='strategy.equity', transp=0, linewidth=4)
//plot(barssince(is_margin_call ), title='barssince(is_margin_call)', transp=100)

can_trade = iff(UseMarginCall, not is_margin_call, true)
trade_size  = InitPosition * (not UseLeverage ? 1 : LeverageValue)

// We can take the trade if not liquidated/margined called/rekt

buy_final   = can_trade and buy_trigger and TradeDateIsAllowed
sell_final  = can_trade and sell_trigger and TradeDateIsAllowed

close_long  = buy_trend  and
 (UseRiskManagement and (is_SL_hit or is_TP_hit)) or sell_trigger

close_short = sell_trend and
 (UseRiskManagement and (is_SL_hit or is_TP_hit)) or buy_trigger

strategy.entry(TradeId + ' B', long=true, qty=trade_size, when=buy_final)
strategy.entry(TradeId + ' S', long=false, qty=trade_size, when=sell_final)
strategy.close(TradeId + ' B', when=close_long)
strategy.close(TradeId + ' S', when=close_short)

// FULL DEGEN MODE ACTIVATED
// Margin called - Broker closing your account
strategy.close_all(when=is_margin_call)

if UseMarginCall and is_margin_call_cross
    f_print("☠️REKT☠️", is_margin_call_cross)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Leveraged-Position-Sizing-with-Margin-Call-Risk-Management-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- Double Decker RSI Trading StrategyPine Script · Machine learning · 1h
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d