MACD Controlled Risk Trading Strategy
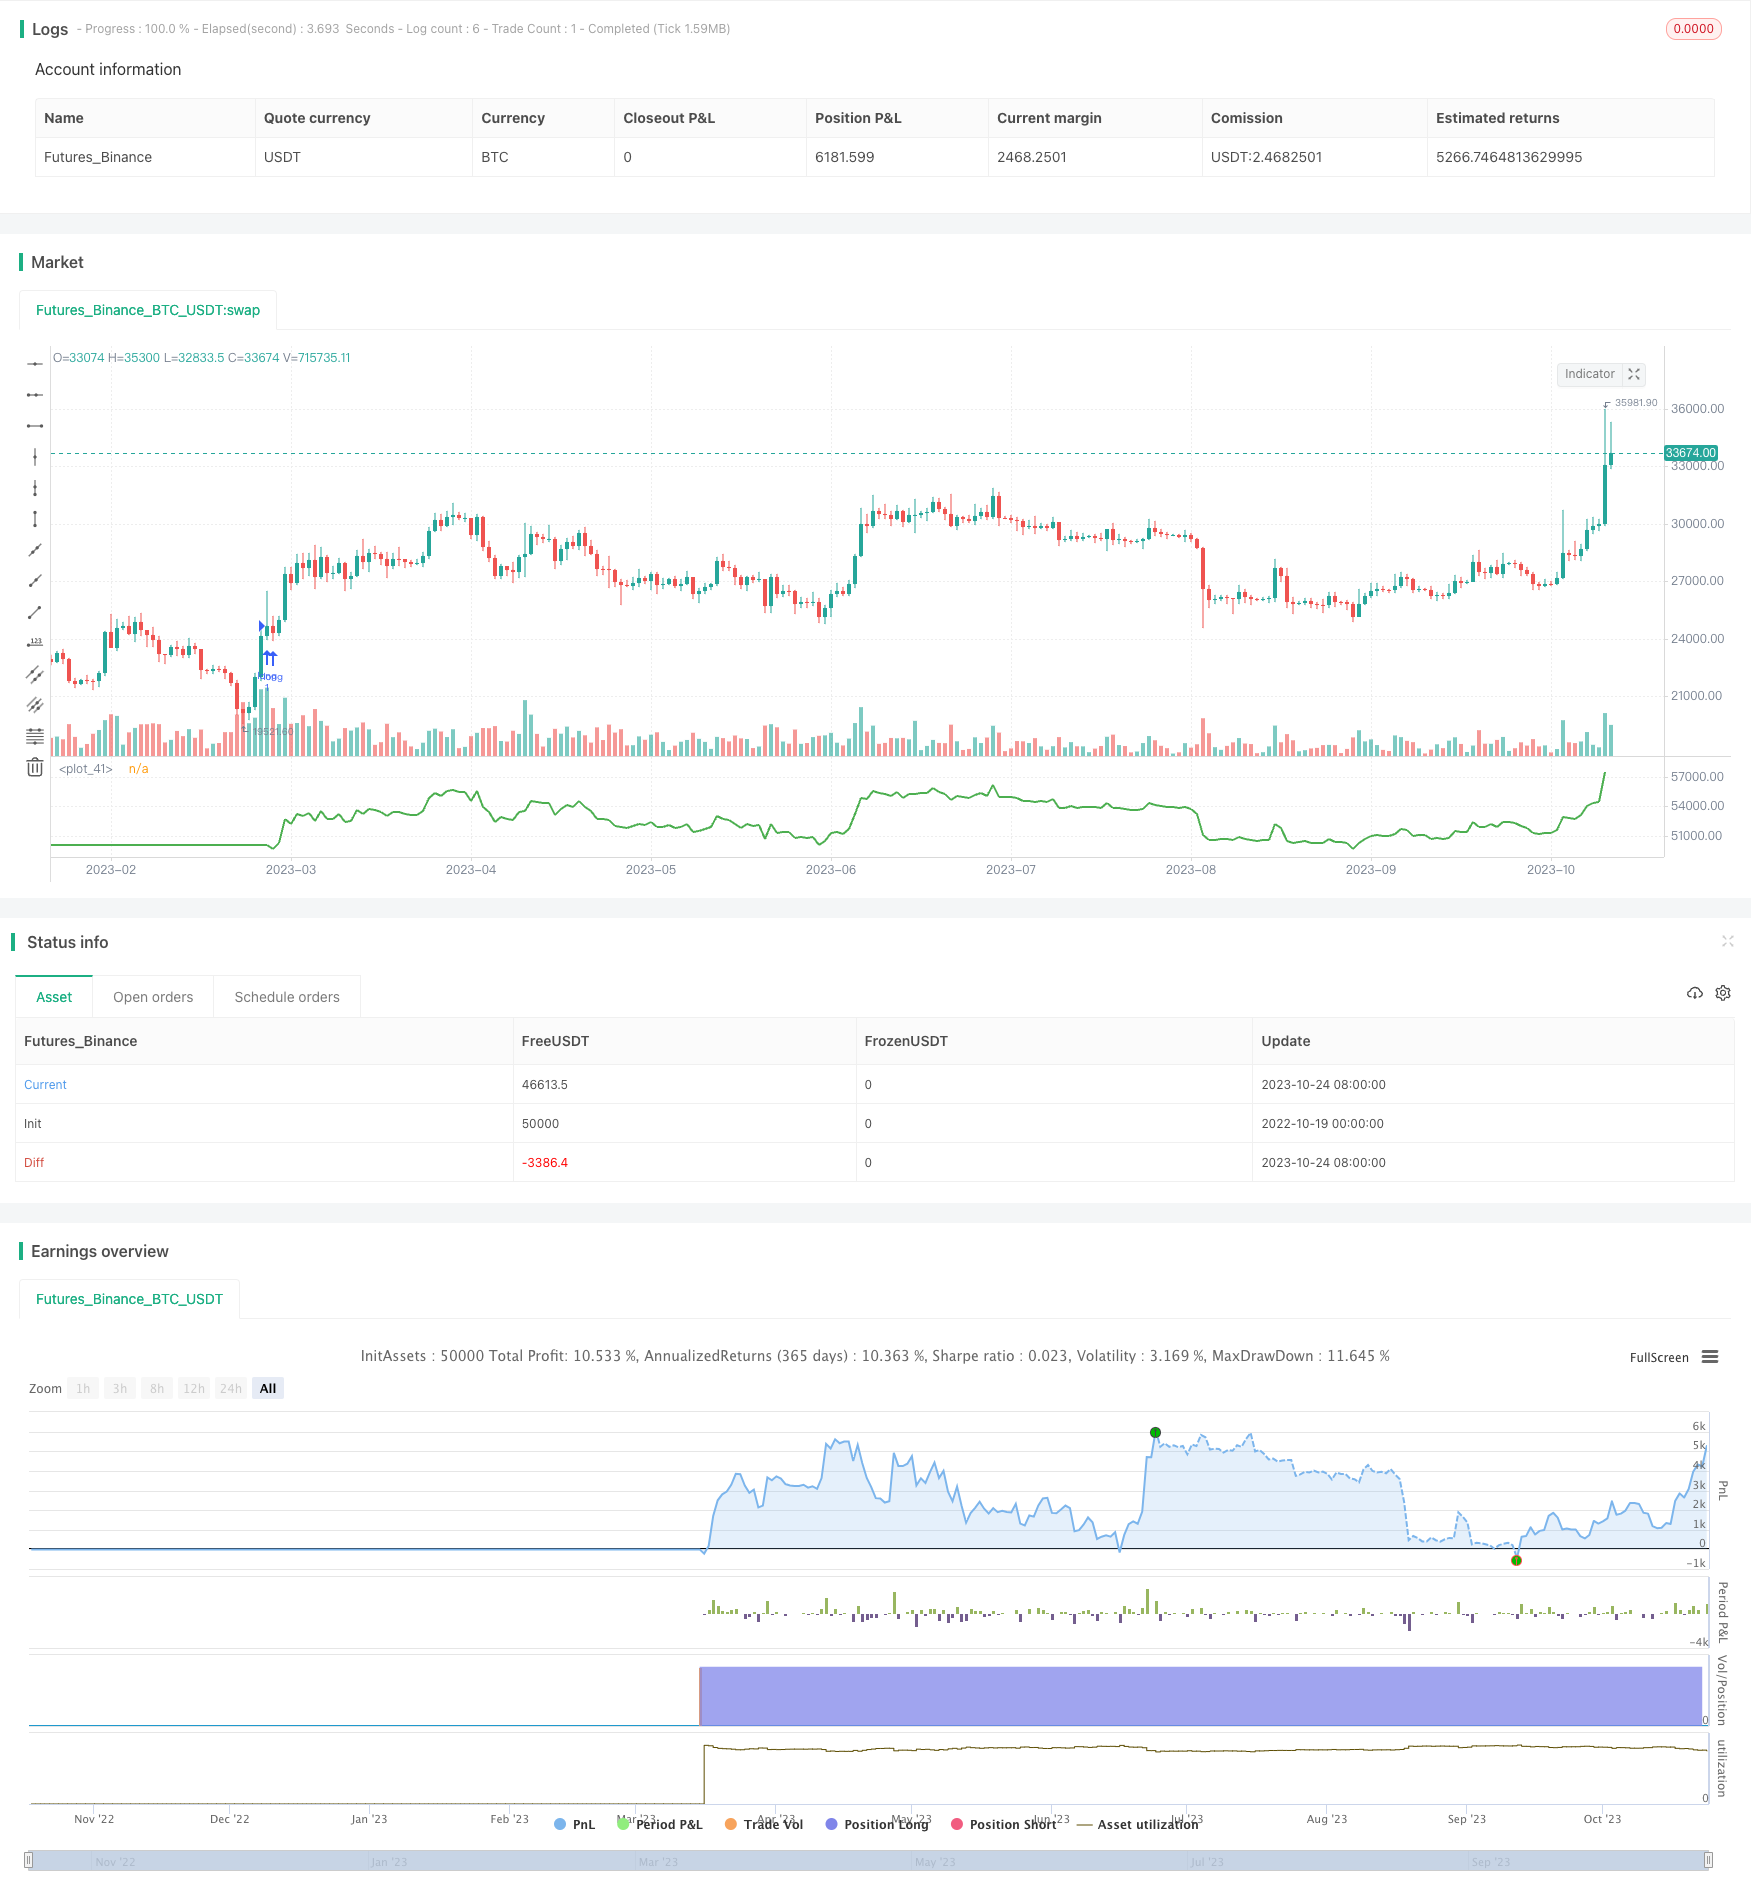
This strategy designs a long-term trading strategy that controls the risk of each trade based on the MACD indicator. Compared with traditional long-short flipping strategies, this strategy focuses more on controlling…
Overview
This strategy designs a long-term trading strategy that controls the risk of each trade based on the MACD indicator. Compared with traditional long-short flipping strategies, this strategy focuses more on controlling the risk of each trade. By calculating reasonable stop loss and take profit levels and setting appropriate position sizes, it limits the maximum loss for each trade. This can effectively control drawdowns and achieve steady profits in the long run.
Principles
The strategy first calculates the MACD line and signal line of the MACD indicator. When the MACD line crosses above the signal line, it is determined as a buy signal. To filter out false breakouts, the strategy requires barssince(crossover(macd_line, signal_line)) <= 5, meaning the breakout happened within the most recent 5 bars. It also requires both the MACD and signal lines to be below 0, indicating an oversold condition, and the close to be above the WMA line, indicating an upwards trend. When the above conditions are met, a long position is opened.
For each trade, the strategy calculates reasonable stop loss and take profit levels. The stop loss is set to the lowest low of the most recent 3 bars. The take profit is set to the entry price plus 4 times the distance between the stop loss and entry price.
The key is that the strategy calculates the specific position size based on the maximum affordable risk. The parameter capital_risk sets the percentage of total capital that can be lost for each trade. The position size in USD is then calculated based on the stop loss range. It is then converted to contracts for execution.
The risk of each trade is controlled within 1% of total capital, which can effectively control drawdowns. At the same time, the large profit target allows for higher returns.
Advantages
- Risk control takes precedence, risk per trade is controllable
- Position sizing optimized to maximize capital usage
- Stop loss strategy effectively controls drawdowns
- Reasonable take profit allows high profit potential
Risks and Improvements
- MACD has lag, may miss fast trend changes
- Improper stop loss or take profit settings may reduce profits or increase risk
- High trading frequency may increase transaction costs
Possible improvements:
- Incorporate other indicators to determine trend, avoid MACD lag
- Optimize stop loss and take profit algorithms to be more flexible
- Relax trading frequency to reduce transaction costs
Summary
This strategy determines trend direction using the MACD, and takes risk control as the priority to trade with optimized position sizing. The keys are risk control and position sizing, which can achieve steady profits long-term. But MACD has some flaws, and the stop loss/take profit mechanisms need further optimization. Further optimizing indicator usage, stop loss/take profit settings, and reducing trading frequency can make the strategy even more powerful.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | % capital risk per trade |
| v_input_2 | 4 | Take Profit in 'R' |
| v_input_3 | 150 | WMA Bias Length |
Source Pine Script
/*backtest
start: 2022-10-19 00:00:00
end: 2023-10-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy( "McDonalds ", shorttitle="Ur Lovin' It", initial_capital=10000, default_qty_type=strategy.cash, currency=currency.USD )

capital_risk    = input( 1.0, "% capital risk per trade" ) / 100
r_exit          = input( 4.0, "Take Profit in 'R'" )
wma_length      = input( 150, 'WMA Bias Length' )

[macd_line, signal_line, hist ] = macd(close, 12, 26, 9)

w_line = wma( close, wma_length )

golong = barssince(crossover(macd_line, signal_line)) <= 5 and ( macd_line < 0 and signal_line < 0 ) and ( close > w_line ) and strategy.opentrades == 0

float stop = na
float tp = na

// For a stop, use a recent low
stop := golong ? lowest(low, 3)[1] : stop[1]
range = abs(close - stop)
tp := golong ? close + (r_exit * range) : tp[1]


// This is the bit that calculates how much size to use so we only lose 1% of the `strategy.equity`
how_much_willing_to_lose = strategy.equity * capital_risk
// Spread the risk across the stop range
position_size_in_usd = how_much_willing_to_lose / (range / close)
// Sized specified in base contract
position_size_in_contracts = position_size_in_usd / close

// Enter the position
if golong
    strategy.entry("long", strategy.long, qty=position_size_in_contracts)
    strategy.exit("long exit","long", stop=stop, limit=tp)

// experimental exit strategy
// hist_strength = hist >= 0 ? ( hist[1] < hist ? 'strong' : 'weak') : ( hist[1] < hist ? 'weak' : 'strong' )
// if hist < 0 and hist_strength == 'strong' and falling( hist, 8 )
//     strategy.close("long")


plot( strategy.equity,  color=strategy.equity > 10000 ? color.green : color.red, linewidth=2 )
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/MACD-Controlled-Risk-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on ADX IndicatorPine Script · Breakout · 1d
- Average Line Breakthrough StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Bull Flag Breakout StrategyPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h