Momentum Indicator Decision Trading Strategy
The Momentum Indicator Decision Trading Strategy is a trend following strategy. It builds a momentum indicator using double exponential moving average and combines it with price rate of change indicator to generate…
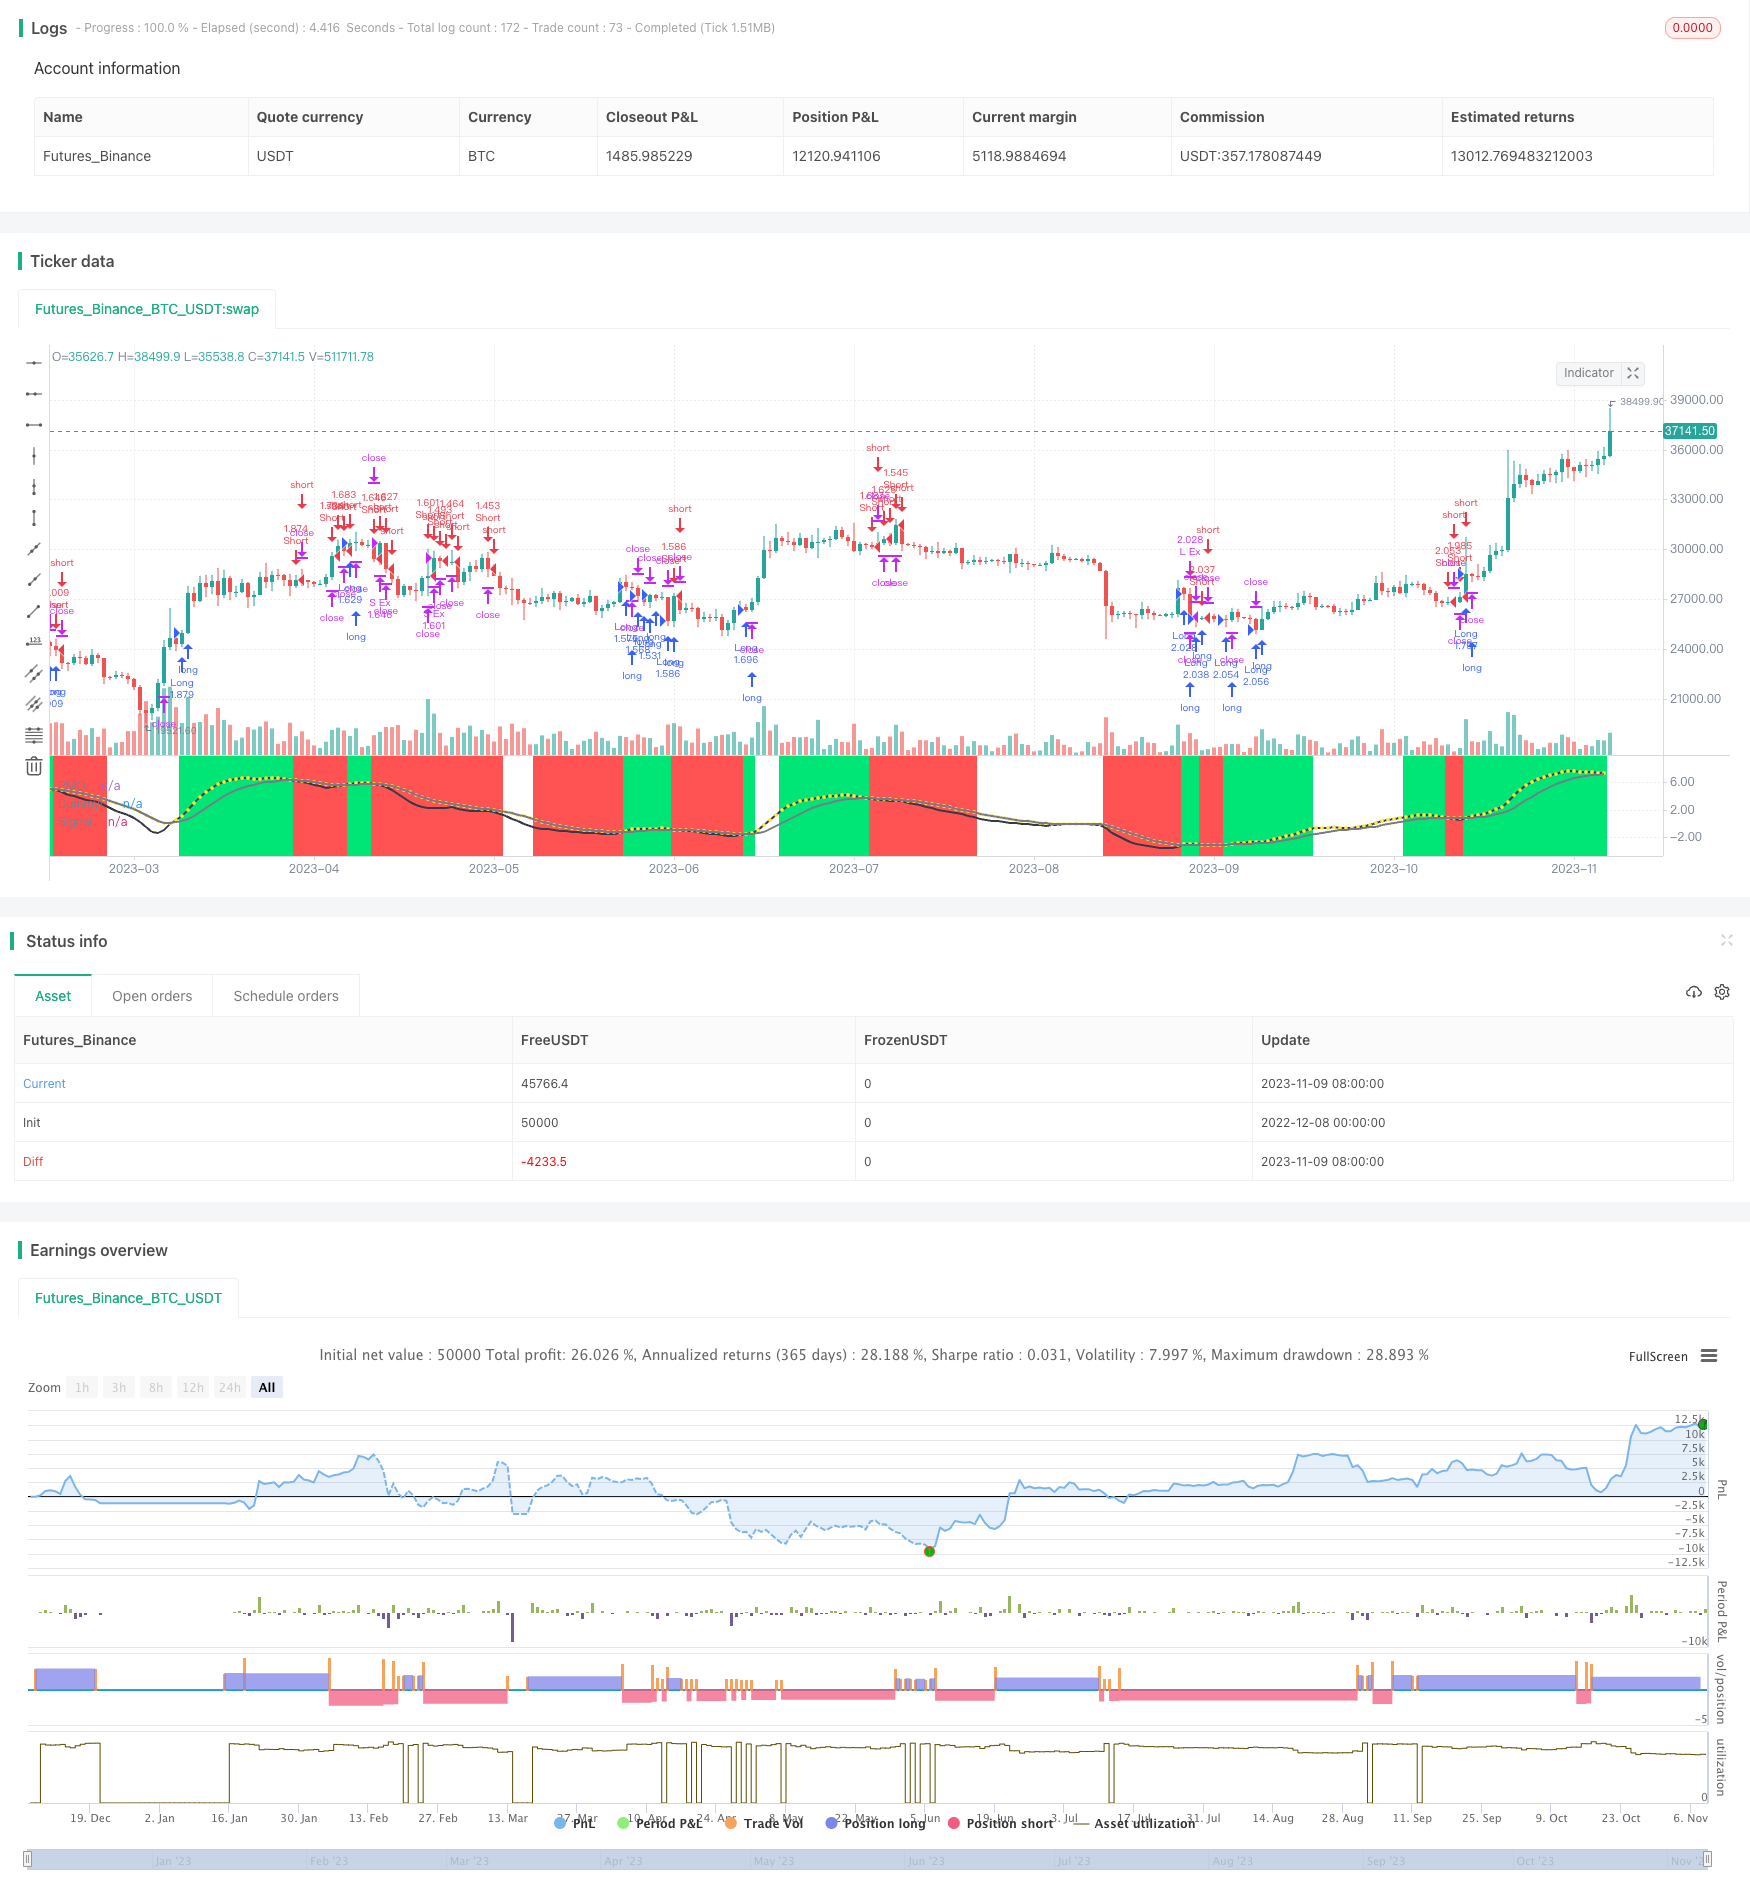
Overview
The Momentum Indicator Decision Trading Strategy is a trend following strategy. It builds a momentum indicator using double exponential moving average and combines it with price rate of change indicator to generate trading signals. When the momentum indicator goes up, it generates long signals. When the momentum indicator goes down, it generates short signals. This strategy suits traders who want to track mid-term trends in the market.
Strategy Principle
The strategy uses Decision Point oscillator based on double exponential moving average to measure momentum. First it calculates the daily price change rate, then uses 31-day and 20-day double exponential moving averages to smooth the price change rate separately. Finally it uses a 9-day smoothed moving average to issue trading signals. When the fast line is above the slow line, it indicates a bull market. When the fast line is below the slow line, it indicates a bear market.
The strategy also introduces a price rate of change indicator to avoid wrong signals in sideways markets. Specifically, it calculates the percentage price change over the past 30 days, and judges whether the market is active through its moving average. Trading signals are only issued when the market is active.
Advantage Analysis
The strategy combines momentum indicator and price rate of change indicator, which can effectively identify mid-term trends and avoid frequent trading in volatile markets. Compared to simple trend following strategies like moving average, it can greatly reduce the probability of wrong trades. In addition, risk is controlled by setting stop loss points to cut losses in time and effectively control per trade loss.
Risk Analysis
The strategy mainly relies on mid-long term trend trading, unable to capture short-term price fluctuations. When there is a sharp market movement, the stop loss point may be broken, leading to greater losses. In addition, inappropriate parameter settings can also affect the strategy. For example, if the double exponential moving average parameters are set too short, the probability of wrong trades will increase.
To prevent risks, stop loss points can be adjusted appropriately to expand stop loss range. When a sharp market movement happens, the strategy can be temporarily turned off to avoid the probability of stop loss being broken. For parameter tuning, detailed backtesting should be performed to select the optimal parameters.
Optimization Directions
The strategy can be optimized in the following aspects:
Add other filtering indicators like volatility indicator to avoid trading during periods of sharp market fluctuations.
Add machine learning models to assist judgment of trend direction and strength, which can improve signal accuracy.
Try different momentum indicators like Relative Strength Index, Stochastic oscillator to optimize entry and exit timing.
In live trading, dynamically adjust parameters combined with recent market conditions to pursue optimal parameter combination.
Conclusion
The Momentum Indicator Decision Trading Strategy is generally a steady mid-long term trend following strategy. It effectively identifies trends and avoids wrong trades by combining double exponential moving average momentum indicator and price rate of change indicator. Meanwhile, it controls risk by setting stop loss points. If parameters are tuned properly and backtest results are good, it suits mid-long term investors who pursue excess returns. Of course, traders still need to be aware of the risk brought by sharp market fluctuations to the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2019 | Backtest Stop Year |
| v_input_5 | 12 | Backtest Stop Month |
| v_input_6 | 31 | Backtest Stop Day |
| v_input_7_ohlc4 | 0 | Source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_8 | 31 | First Smoothing |
| v_input_9 | 20 | Second Smoothing |
| v_input_10 | 9 | Signal Smoothing |
| v_input_11 | true | Fill Region |
| v_input_12 | 30 | roclength |
| v_input_13 | 7 | pcntChange |
| v_input_14 | 2 | Stop Loss % |
| v_input_15 | 5000 | Take Profit % |
Source Pine Script
/*backtest
start: 2022-12-08 00:00:00
end: 2023-11-10 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Decision BF", overlay=false, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.075)

/////////////// Time Frame ///////////////
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay, 0, 0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(31, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay, 0, 0)

testPeriod() => true

/////////////// Decision ///////////////
src = input(ohlc4, title="Source")
length1 = input(31, title="First Smoothing")
length2 = input(20, title="Second Smoothing")
siglength = input(9, title="Signal Smoothing")
fr = input(true, title="Fill Region")

calc_csf(src, length) =>
	sm = 2.0 / length
	csf = 0.0
	csf := (src - nz(csf[1])) * sm + nz(csf[1])
	csf
i = (src / nz(src[1], src)) * 100
pmol2 = calc_csf(i - 100, length1)
pmol = calc_csf(10 * pmol2, length2)
pmols = ema(pmol, siglength)
d = pmol - pmols
duml = plot(fr ? (d > 0 ? pmol : pmols) : na, style=plot.style_circles, color=color.yellow, linewidth=0, title="DummyL")

hc = d > 0 ? d > d[1] ? color.lime : color.green : d < d[1] ? color.red : color.orange

///////////// Rate Of Change /////////////
source = close
roclength = input(30, minval=1)
pcntChange = input(7, minval=1)
roc = 100 * (source - source[roclength]) / source[roclength]
emaroc = ema(roc, roclength / 2)
isMoving() => emaroc > (pcntChange / 2) or emaroc < (0 - (pcntChange / 2))

/////////////// Strategy ///////////////
long = d > 0 and isMoving()
short = d < 0 and isMoving()

last_long = 0.0
last_short = 0.0
last_long := long ? time : nz(last_long[1])
last_short := short ? time : nz(last_short[1])

long_signal = crossover(last_long, last_short)
short_signal = crossover(last_short, last_long)

last_open_long_signal = 0.0
last_open_short_signal = 0.0
last_open_long_signal := long_signal ? open : nz(last_open_long_signal[1])
last_open_short_signal := short_signal ? open : nz(last_open_short_signal[1])

last_long_signal = 0.0
last_short_signal = 0.0
last_long_signal := long_signal ? time : nz(last_long_signal[1])
last_short_signal := short_signal ? time : nz(last_short_signal[1])

in_long_signal = last_long_signal > last_short_signal
in_short_signal = last_short_signal > last_long_signal

last_high = 0.0
last_low = 0.0
last_high := not in_long_signal ? na : in_long_signal and (na(last_high[1]) or high > nz(last_high[1])) ? high : nz(last_high[1])
last_low := not in_short_signal ? na : in_short_signal and (na(last_low[1]) or low < nz(last_low[1])) ? low : nz(last_low[1])

sl_inp = input(2.0, title='Stop Loss %') / 100
tp_inp = input(5000.0, title='Take Profit %') / 100

take_level_l = strategy.position_avg_price * (1 + tp_inp)
take_level_s = strategy.position_avg_price * (1 - tp_inp)

since_longEntry = barssince(last_open_long_signal != last_open_long_signal[1])
since_shortEntry = barssince(last_open_short_signal != last_open_short_signal[1])

slLong = in_long_signal ? strategy.position_avg_price * (1 - sl_inp) : na
slShort = strategy.position_avg_price * (1 + sl_inp)
long_sl = in_long_signal ? slLong : na
short_sl = in_short_signal ? slShort : na

/////////////// Execution ///////////////
if testPeriod()
    strategy.entry("Long",  strategy.long, when=long)
    strategy.entry("Short", strategy.short, when=short)
    strategy.exit("L Ex", "Long", stop=long_sl, limit=take_level_l, when=since_longEntry > 0)
    strategy.exit("S Ex", "Short", stop=short_sl, limit=take_level_s, when=since_shortEntry > 0)

/////////////// Plotting ///////////////
sigl = plot(false ? na : pmols, title="PMO Signal", color=color.gray, linewidth=2, title="Signal")
mdl = plot(false ? na : pmol, title="PMO", color=color.black, linewidth=2, title="PMO")
fill(duml, sigl, color.green, transp=20, title="PosFill")
fill(duml, mdl, color.red, transp=20, title="NegFill")
bgcolor(isMoving() ? long ? color.lime : short ? color.red : na : color.white, transp=70)
bgcolor(long_signal ? color.lime : short_signal ? color.red : na, transp=50)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Indicator-Decision-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Cross Period Momentum EMA Strategy with RSI and Dynamic ATR Stop LossPine Script · Momentum · 1d
- Dual EMA Crossover with RSI Momentum Enhanced Trading StrategyPine Script · Momentum · 1d
- Dual EMA Momentum Trend Trading Strategy with Full Body Candle Signal SystemPine Script · Momentum · 2h