Momentum Pullback Strategy 440057
The Momentum Pullback Strategy is a medium-term trading strategy that combines moving averages and candlestick patterns to identify trading opportunities by detecting breakouts and pullbacks. It is suitable for…
Overview
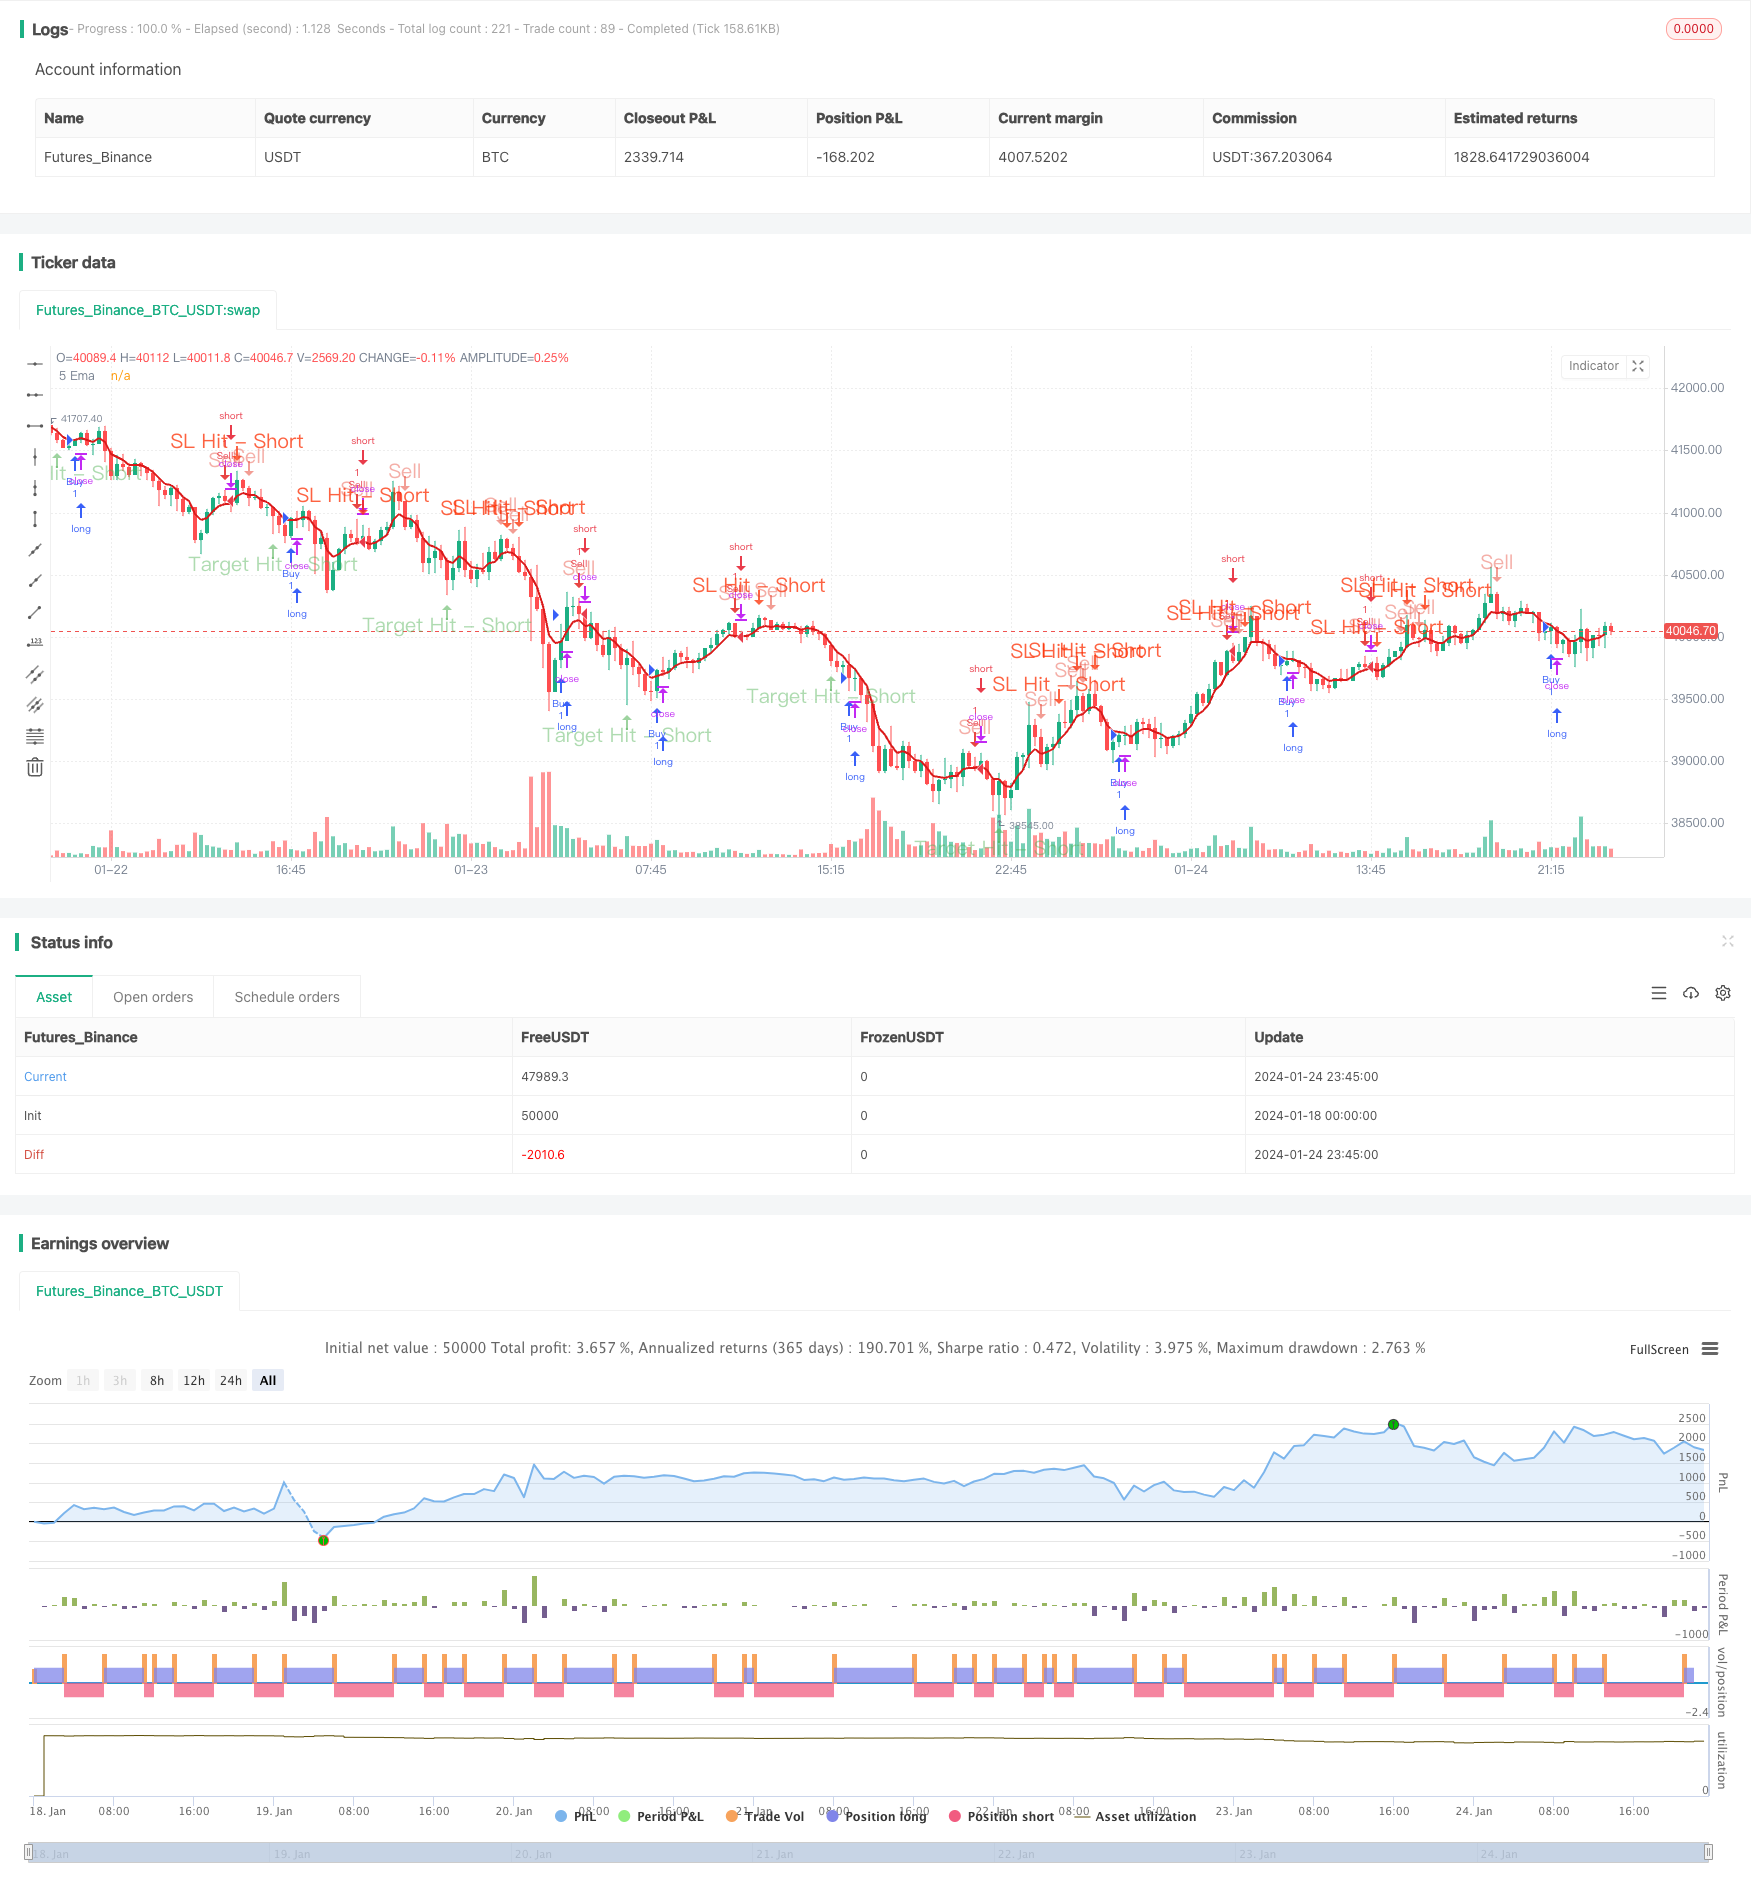
The Momentum Pullback Strategy is a medium-term trading strategy that combines moving averages and candlestick patterns to identify trading opportunities by detecting breakouts and pullbacks. It is suitable for trading highly leveraged financial products like options and futures.
Strategy Logic
The core logic of this strategy is based on the 5-day simple moving average. When the price is about to break through this average line, it will form a gap high or low candlestick, which signals a potential long or short opportunity. The entry signal is triggered when the second candle closing beyond the moving average does not break the previous gap candle's low or high. Stop loss and profit target levels are then set based on the risk-reward ratio.
When the price breaks above the 5-day MA and closes, the previous gap candle's high is the stop loss level. The profit target is set by subtracting a certain retracement range from the low, multiplied by the desired risk-reward ratio. Similarly for a downside breakout, the previous gap candle's low is the stop loss, while the take profit level is above the high plus a retracement range factored by the risk-reward ratio.
An optional filter is provided where the current candle's close should be slightly lower or higher than the gap candle's close for additional confirmation, avoiding false signals.
Advantage Analysis
- Clear and simple strategy logic, easy to understand and implement
- Identifies trends and pullbacks using moving averages
- More precise trade timing combining candlestick patterns
- Matches risk and reward, aligns with prudent trading
- Adjustable parameters for different products and timeframes
- Optional filter avoids some false signals
Risk Analysis
- Common technical analysis risks like being caught in trends, stop run-throughs
- Lagging nature of moving averages may miss quick reversals
- More false signals likely in range-bound markets
- Excessive trading from poor parameter tuning
Risks can be reduced via sensible stop losses, position sizing, less frequent trading etc. Combining other indicators to filter signals is also an option.
Optimization Directions
- Test different parameter sets for best performance
- Add other indicators or chart patterns to filter signals
- Explore dynamic, trailing stop loss enhancements
- Apply machine learning to auto-optimize parameters
- Develop auto stop loss / take profit plugins
- Robustness checks across products and timeframes
Conclusion
Overall this is an easy to understand and implement medium-term trading strategy. It capitalizes on trend reversals identified by moving averages and gap candles, with a rational risk control framework. While further improvements are possible, the core logic is versatile for wider application via parameter tuning, signal filtering etc.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_bool_1 | false | Enable the Extra SL shown below |
| v_input_int_1 | 5 | Value to set SL number of points below-low or above-high |
| v_input_int_2 | 3 | Risk to Reward Ratio |
| v_input_bool_2 | true | Show Sell Signals |
| v_input_bool_3 | false | Show Buy Signals |
| v_input_bool_4 | false | Buy/Sell with Extra Condition - candle close |
Source Pine Script
/*backtest
start: 2024-01-18 00:00:00
end: 2024-01-25 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © TradingInsights2

//@version=5
strategy("Ultimate 5EMA Strategy By PowerOfStocks", overlay=true)

Eusl = input.bool(false, title="Enable the Extra SL shown below")
usl = input.int(defval=5, title='Value to set SL number of points below-low or above-high', minval=1, maxval=100)
RiRe = input.int(defval=3, title='Risk to Reward Ratio', minval=1, maxval=25)
ShowSell = input.bool(true, 'Show Sell Signals')
ShowBuy = input.bool(false, 'Show Buy Signals')
BSWCon = input.bool(defval=false, title='Buy/Sell with Extra Condition - candle close')

// Moving Average

ema5 = ta.ema(close, 5)
pema5 = plot(ema5, '5 Ema', color=color.new(#da1a1a, 0), linewidth=2)

var bool Short = na
var bool Long = na
var shortC = 0
var sslhitC = 0
var starhitC = 0
var float ssl = na
var float starl = na
var float star = na
var float sellat = na
var float alert_shorthigh = na
var float alert_shortlow = na
var line lssl = na
var line lstar = na
var line lsell = na
var label lssllbl = na
var label lstarlbl = na
var label lselllbl = na
var longC = 0
var lslhitC = 0
var ltarhitC = 0
var float lsl = na
var float ltarl = na
var float ltar = na
var float buyat = na
var float alert_longhigh = na
var float alert_longlow = na
var line llsl = na
var line lltar = na
var line lbuy = na
var label llsllbl = na
var label lltarlbl = na
var label lbuylbl = na

ShortWC = low[1] > ema5[1] and low[1] > low and shortC == 0 and close < close[1]
ShortWOC = low[1] > ema5[1] and low[1] > low and shortC == 0
Short := BSWCon ? ShortWC : ShortWOC
sslhit = high > ssl and shortC > 0 and sslhitC == 0
starhit = low < star and shortC > 0 and starhitC == 0
LongWC = high[1] < ema5[1] and high[1] < high and longC == 0 and close > close[1]
LongWOC = high[1] < ema5[1] and high[1] < high and longC == 0
Long := BSWCon ? LongWC : LongWOC
lslhit = low < lsl and longC > 0 and lslhitC == 0
ltarhit = high > ltar and longC > 0 and ltarhitC == 0

if Short and ShowSell
    shortC := shortC + 1
    sslhitC := 0
    starhitC := 0
    alert_shorthigh := high[1]
    if Eusl
        ssl := high[1] + usl
        starl := BSWCon ? ((high[1] - close) + usl) * RiRe : ((high[1] - low[1]) + usl) * RiRe
    else
        ssl := high[1]
        starl := BSWCon ? (high[1] - close) * RiRe : (high[1] - low[1]) * RiRe
    star := BSWCon ? close - starl : low[1] - starl
    sellat := BSWCon ? close : low[1]
    // lssl := line.new(bar_index, ssl, bar_index, ssl, color=color.new(#fc2d01, 45), style=line.style_dashed)
    // lstar := line.new(bar_index, star, bar_index, star, color=color.new(color.green, 45), style=line.style_dashed)
    // lsell := line.new(bar_index, sellat, bar_index, sellat, color=color.new(color.orange, 45), style=line.style_dashed)
    // lssllbl := label.new(bar_index, ssl, style=label.style_none, text='Stop Loss - Short' + ' (' + str.tostring(ssl) + ')', textcolor=color.new(#fc2d01, 35), color=color.new(#fc2d01, 35))
    // lstarlbl := label.new(bar_index, star, style=label.style_none, text='Target - Short' + ' (' + str.tostring(star) + ')', textcolor=color.new(color.green, 35), color=color.new(color.green, 35))
    // lselllbl := label.new(bar_index, sellat, style=label.style_none, text='Sell at' + ' (' + str.tostring(sellat) + ')', textcolor=color.new(color.orange, 35), color=color.new(color.orange, 35))

if sslhit == false and starhit == false and shortC > 0
    // line.set_x2(lssl, bar_index)
    // line.set_x2(lstar, bar_index)
    // line.set_x2(lsell, bar_index)
    sslhitC := 0
    starhitC := 0
else
    if sslhit
        shortC := 0
        sslhitC := sslhitC + 1
    else
        if starhit
            shortC := 0
            starhitC := starhitC + 1

if Long and ShowBuy
    longC := longC + 1
    lslhitC := 0
    ltarhitC := 0
    alert_longlow := low[1]
    if Eusl
        lsl := low[1] - usl
        ltarl := BSWCon ? ((close - low[1]) + usl) * RiRe : ((high[1] - low[1]) + usl) * RiRe
    else
        lsl := low[1]
        ltarl := BSWCon ? (close - low[1]) * RiRe : (high[1] - low[1]) * RiRe
    ltar := BSWCon ? close + ltarl : high[1] + ltarl
    buyat := BSWCon ? close : high[1]
    llsl := line.new(bar_index, lsl, bar_index, lsl, color=color.new(#fc2d01, 45), style=line.style_dotted)
    lltar := line.new(bar_index, ltar, bar_index, ltar, color=color.new(color.green, 45), style=line.style_dotted)
    lbuy := line.new(bar_index, buyat, bar_index, buyat, color=color.new(color.orange, 45), style=line.style_dotted)
    llsllbl := label.new(bar_index, lsl, style=label.style_none, text='Stop Loss - Long' + ' (' + str.tostring(lsl) + ')', textcolor=color.new(#fc2d01, 35), color=color.new(#fc2d01, 35))
    lltarlbl := label.new(bar_index, ltar, style=label.style_none, text='Target - Long' + ' (' + str.tostring(ltar) + ')', textcolor=color.new(color.green, 35), color=color.new(color.green, 35))
    lbuylbl := label.new(bar_index, buyat, style=label.style_none, text='Buy at' + ' (' + str.tostring(buyat) + ')', textcolor=color.new(color.orange, 35), color=color.new(color.orange, 35))

if lslhit == false and ltarhit == false and longC > 0
    // line.set_x2(llsl, bar_index)
    // line.set_x2(lltar, bar_index)
    // line.set_x2(lbuy, bar_index)
    lslhitC := 0
    ltarhitC := 0
else
    if lslhit
        longC := 0
        lslhitC := lslhitC + 1
    else
        if ltarhit
            longC := 0
            ltarhitC := ltarhitC + 1

strategy.entry("Buy", strategy.long, when=Long)
strategy.entry("Sell", strategy.short, when=Short)
strategy.close("ExitBuy", when=sslhit or starhit)
strategy.close("ExitSell", when=lslhit or ltarhit)

plotshape(ShowSell and Short, title='Sell', location=location.abovebar, offset=0, color=color.new(#e74c3c, 45), style=shape.arrowdown, size=size.normal, text='Sell', textcolor=color.new(#e74c3c, 55))
plotshape(ShowSell and sslhit, title='SL Hit - Short', location=location.abovebar, offset=0, color=color.new(#fc2d01, 25), style=shape.arrowdown, size=size.normal, text='SL Hit - Short', textcolor=color.new(#fc2d01, 25))
plotshape(ShowSell and starhit, title='Target Hit - Short', location=location.belowbar, offset=0, color=color.new(color.green, 45), style=shape.arrowup, size=size.normal, text='Target Hit - Short', textcolor=color.new(color.green, 55))
plotshape(ShowBuy and Long, title='Buy', location=location.belowbar, offset=0, color=color.new(#2ecc71, 45), style=shape.arrowup, size=size.normal, text='Buy', textcolor=color.new(#2ecc71, 55))
plotshape(ShowBuy and lslhit, title='SL Hit - Long', location=location.belowbar, offset=0, color=color.new(#fc2d01, 25), style=shape.arrowdown, size=size.normal, text='SL Hit - Long', textcolor=color.new(#fc2d01, 25))
plotshape(ShowBuy and ltarhit, title='Target Hit - Long', location=location.abovebar, offset=0, color=color.new(color.green, 45), style=shape.arrowup, size=size.normal, text='Target Hit - Long', textcolor=color.new(color.green, 55))

if ShowSell and Short
    alert("Go Short@ " + str.tostring(sellat) + " : SL@ " + str.tostring(ssl) + " : Target@ " + str.tostring(star) + " ", alert.freq_once_per_bar )

if ShowBuy and Long
    alert("Go Long@ " + str.tostring(buyat) + " : SL@ " + str.tostring(lsl) + " : Target@ " + str.tostring(ltar) + " ", alert.freq_once_per_bar )

///// End of codePublished by ChaoZhang on the FMZ strategy square · last modified 2024-01-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Pullback-Strategy-440057.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- MACD Momentum Indicator Backtest StrategyPine Script · Momentum · 1h
- MACD of Relative Strength StrategyPine Script · Momentum · 1d
- Momentum Strategy Based on DEMA and EMA Crossover with ATR Volatility FilterPine Script · Momentum · 1h