Momentum Tracking Strategy Based on Ichimoku Cloud
This strategy combines moving averages, relative strength index (RSI) and ichimoku cloud to identify price trends and make trades accordingly. The core idea is to generate buy signals when the short term moving…
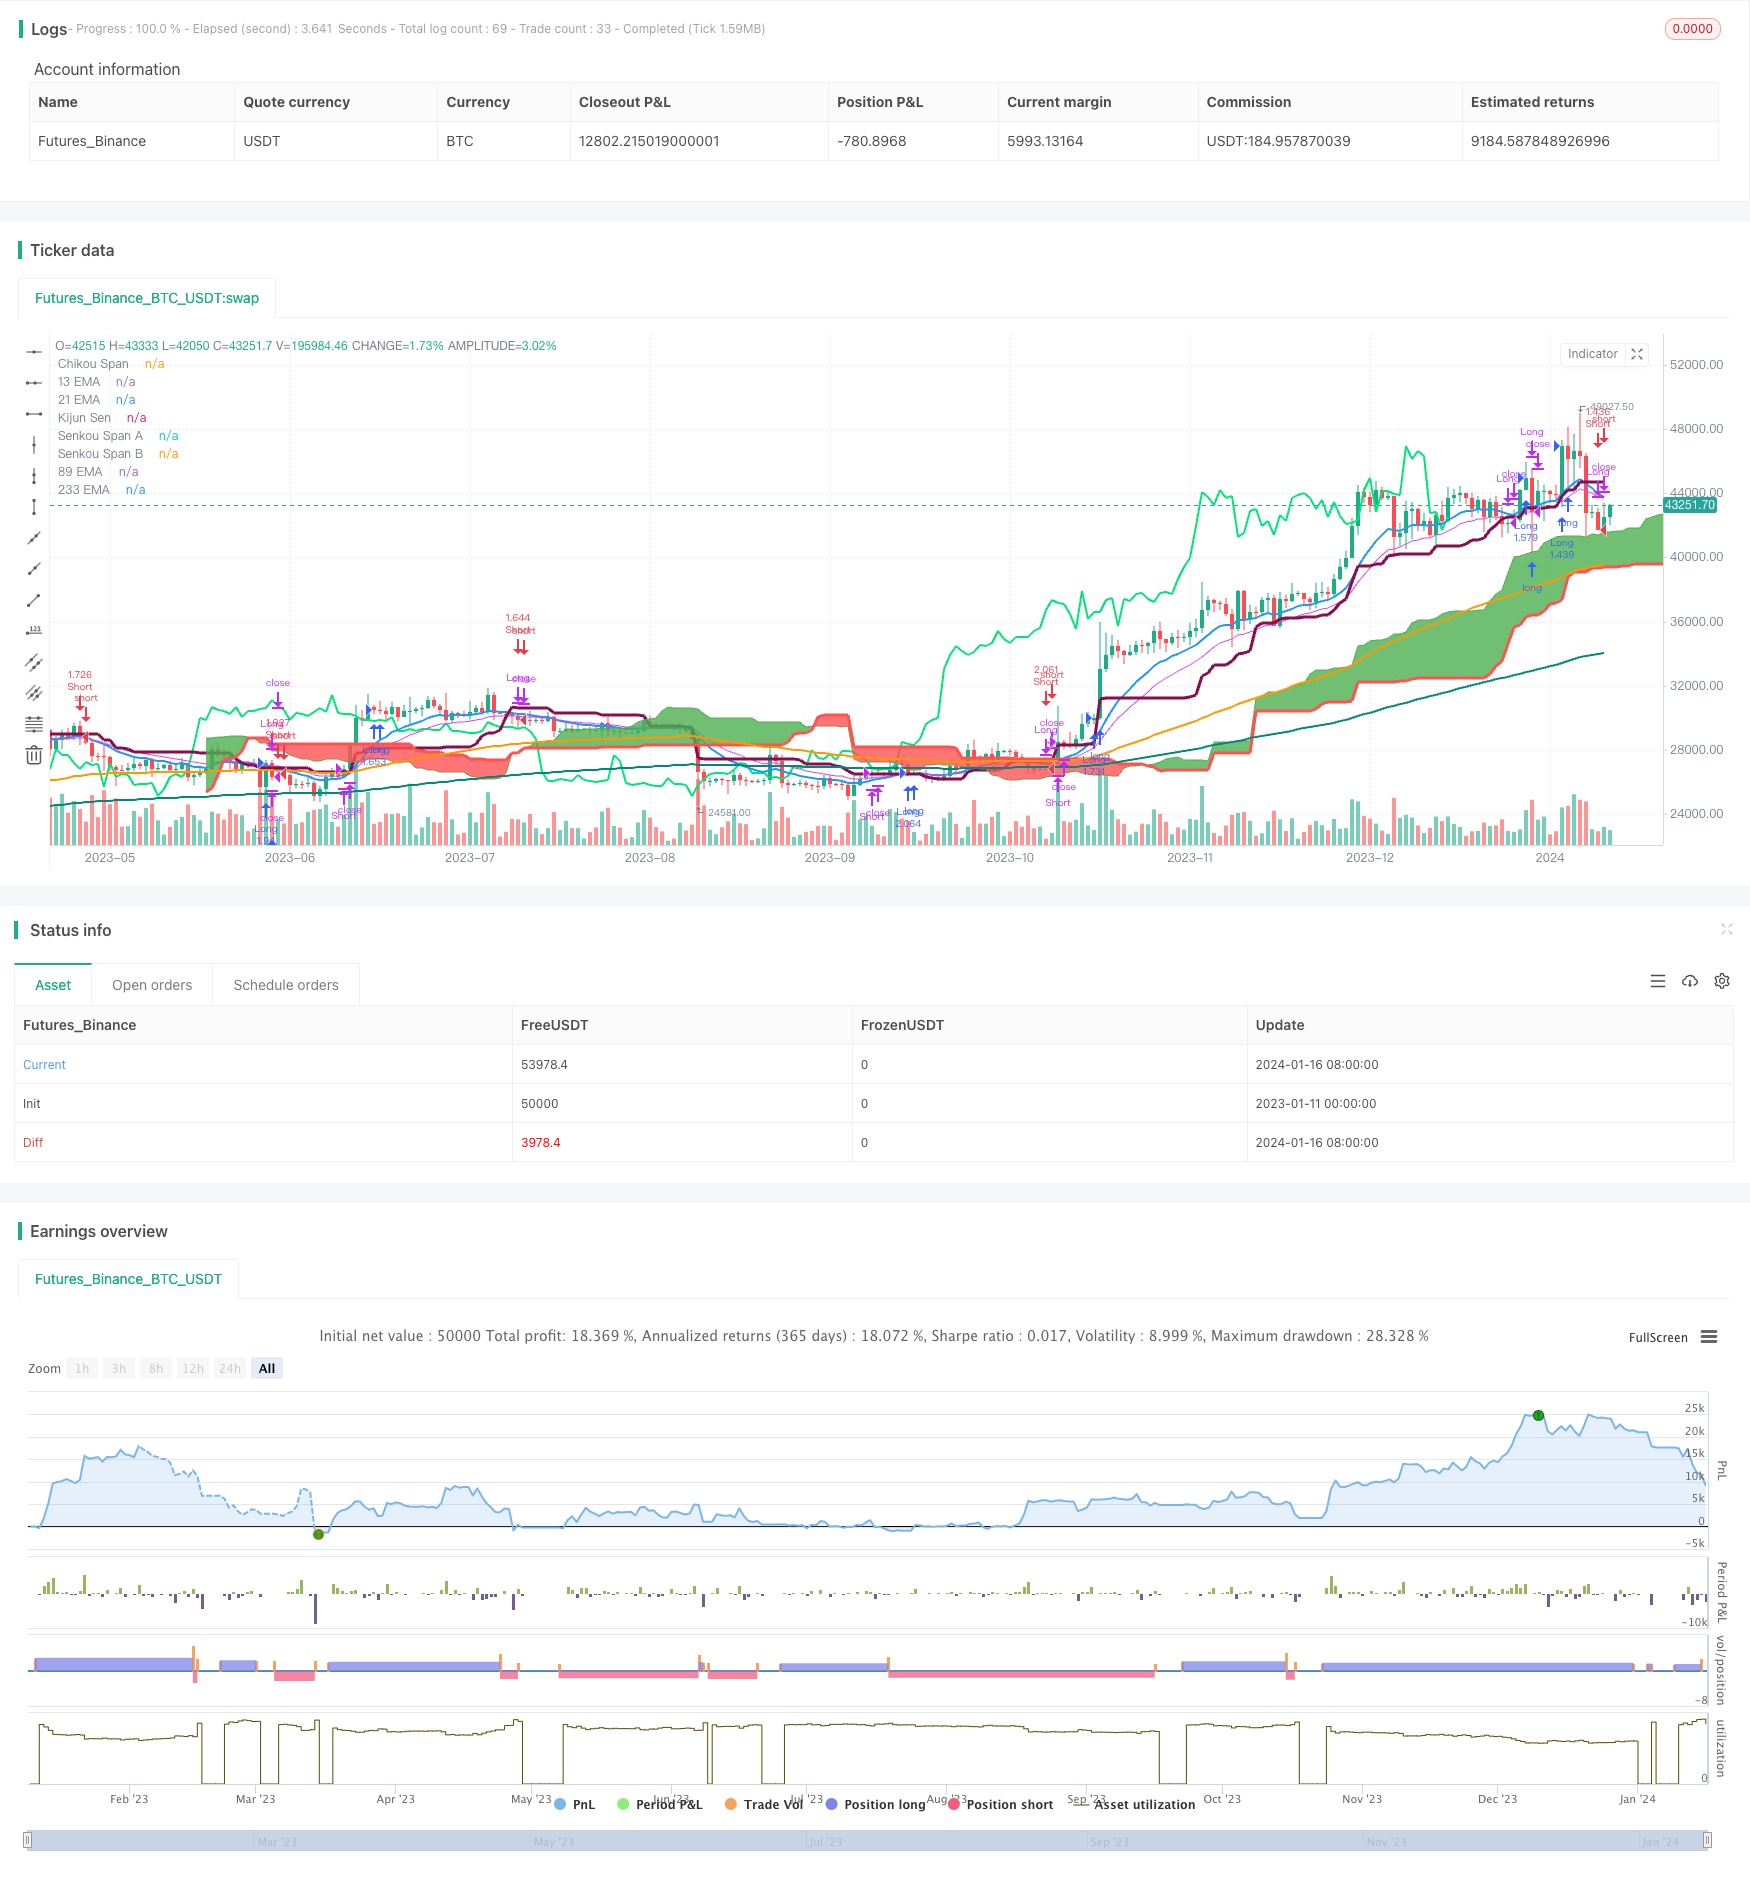
Overview
This strategy combines moving averages, relative strength index (RSI) and ichimoku cloud to identify price trends and make trades accordingly. The core idea is to generate buy signals when the short term moving average crosses above the medium term average and penetrates above the cloud, and to generate sell signals when the reverse happens.
Strategy Logic
The strategy employs four moving averages - 13, 21, 89 and 233 days. The 13 day MA represents short term trend while the 233 day line shows long term trend. The 21 and 89 day MAs are in between. When the short term MA crosses above the medium term ones, it indicates an upside breakout and generates buy signals. The opposite cross leads to sell signals.
In addition, the conversion line (9 day MA), base line (26 day MA) and leading span (average of conversion and base lines) of the Ichimoku cloud are used. Penetrating above the leading span gives buy signals while breaking below it shows sells.
Furthermore, 12 and 24 day RSIs are applied. The 12 day RSI represents short term overbought/oversold levels while the 24 day line shows medium term situations. Crossovers between the two can help confirm trading signals.
Advantages
- Identify trend direction with MAs
- Ichimoku cloud for entry and exit timing
- Avoid false breakouts using RSI
This strategy excels at capturing the prevailing trend of security prices. Entry and exit based on MAs and ichimoku improves precision. Moreover, RSI crossover helps avoid false signals. In summary, this combines strengths of multiple indicators to effectively trade along the trend.
Risks
Trend reversal risk
Traders should watch out for prices touching moving averages and get ready to close positions.Parameter optimization
There are rooms to improve MA periods, Ichimoku parameters etc. Traders can experiment to find the optimal set for different products.High trading frequency
The strategy may trade quite frequently, thus commission costs need to be considered. Fine tuning parameters can help reduce unnecessary trades.
Improvements
Add stop loss/profit target
Introducing such risk management mechanisms would reduce drawdowns.Parameter tuning
Optimize MA periods, Ichimoku inputs, RSI days etc for better stability across different products.Incorporate more indicators
Other derived indicators around volatility and volume could provide additional insight.
Conclusion
This is a typical trend following strategy harnessing strengths of MAs, RSI and Ichimoku cloud. It reliably locks onto prevailing trends. Through refinements like stop loss, parameter optimization etc, performance can be further improved. Overall this is a stable, profitable momentum strategy suitable for investors with adequate risk appetite seeking persistent gains.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 9 | Tenkan Sen Periods |
| v_input_2 | 26 | Kijun Sen Periods |
| v_input_3 | 52 | Senkou Span B Periods |
| v_input_4 | 26 | Displacement |
Source Pine Script
/*backtest
start: 2023-01-11 00:00:00
end: 2024-01-17 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3

strategy("EMA + Ichimoku Kinko Hyo Strategy", shorttitle="EMI", overlay=true, default_qty_type=strategy.percent_of_equity, max_bars_back=1000, default_qty_value=100, calc_on_order_fills= true, calc_on_every_tick=true, pyramiding=0)

TenkanSenPeriods = input(9, minval=1, title="Tenkan Sen Periods")
KijunSenPeriods = input(26, minval=1, title="Kijun Sen Periods")
SenkouSpanBPeriods = input(52, minval=1, title="Senkou Span B Periods")
displacement = input(26, minval=1, title="Displacement")
donchian(len) => avg(lowest(len), highest(len))
TenkanSen = donchian(TenkanSenPeriods)
KijunSen = donchian(KijunSenPeriods)
SenkouSpanA = avg(TenkanSen, KijunSen)
SenkouSpanB = donchian(SenkouSpanBPeriods)
SenkouSpanH = max(SenkouSpanA[displacement - 1], SenkouSpanB[displacement - 1])
SenkouSpanL = min(SenkouSpanA[displacement - 1], SenkouSpanB[displacement - 1])
ChikouSpan = close[displacement-1]

Sema = ema(close, 13)
Mema = ema(close, 21)
Lema = ema(close, 89)
XLema = ema(close, 233)

plot(Sema, color=blue, title="13 EMA", linewidth = 2)
plot(Mema, color=fuchsia, title="21 EMA", linewidth = 1)
plot(Lema, color=orange, title="89 EMA", linewidth = 2)
plot(XLema, color=teal, title="233 EMA", linewidth = 2)
plot(KijunSen, color=maroon, title="Kijun Sen", linewidth = 3)
plot(close, offset = -displacement, color=lime, title="Chikou Span", linewidth = 2)
sa=plot (SenkouSpanA, offset = displacement, color=green,  title="Senkou Span A", linewidth = 1)
sb=plot (SenkouSpanB, offset = displacement, color=red,  title="Senkou Span B", linewidth = 3)
fill(sa, sb, color = SenkouSpanA > SenkouSpanB ? green : red)

longCondition = (rsi(close, 12)>rsi(close, 24)) and close>ChikouSpan and Sema>KijunSen
strategy.entry("Long",strategy.long,when = longCondition)

strategy.close("Long", when = (rsi(close, 12)<rsi(close, 24) and (close<KijunSen and close<ChikouSpan)))

shortCondition = (rsi(close, 12)<rsi(close, 24)) and close<ChikouSpan and Sema<KijunSen
strategy.entry("Short",strategy.short, when = shortCondition)

strategy.close("Short", when = (rsi(close, 12)>rsi(close, 24) and (close>KijunSen and close>ChikouSpan)))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Tracking-Strategy-Based-on-Ichimoku-Cloud.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fukuiz Octa EMA IchimokuPine Script · Momentum · 10m
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Dynamic Momentum Oscillator Trading Strategy 435470Pine Script · Momentum · 1d
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Composite Moving Average and Market Momentum Trend Capture StrategyPine Script · Momentum
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h