Momentum Trading Strategy Based on Multi factor Model
This strategy is a momentum trading strategy based on multiple technical indicators. The strategy adopts Bollinger Bands, RSI, ATR and other technical indicators to implement a multi-factor model to quickly judge…
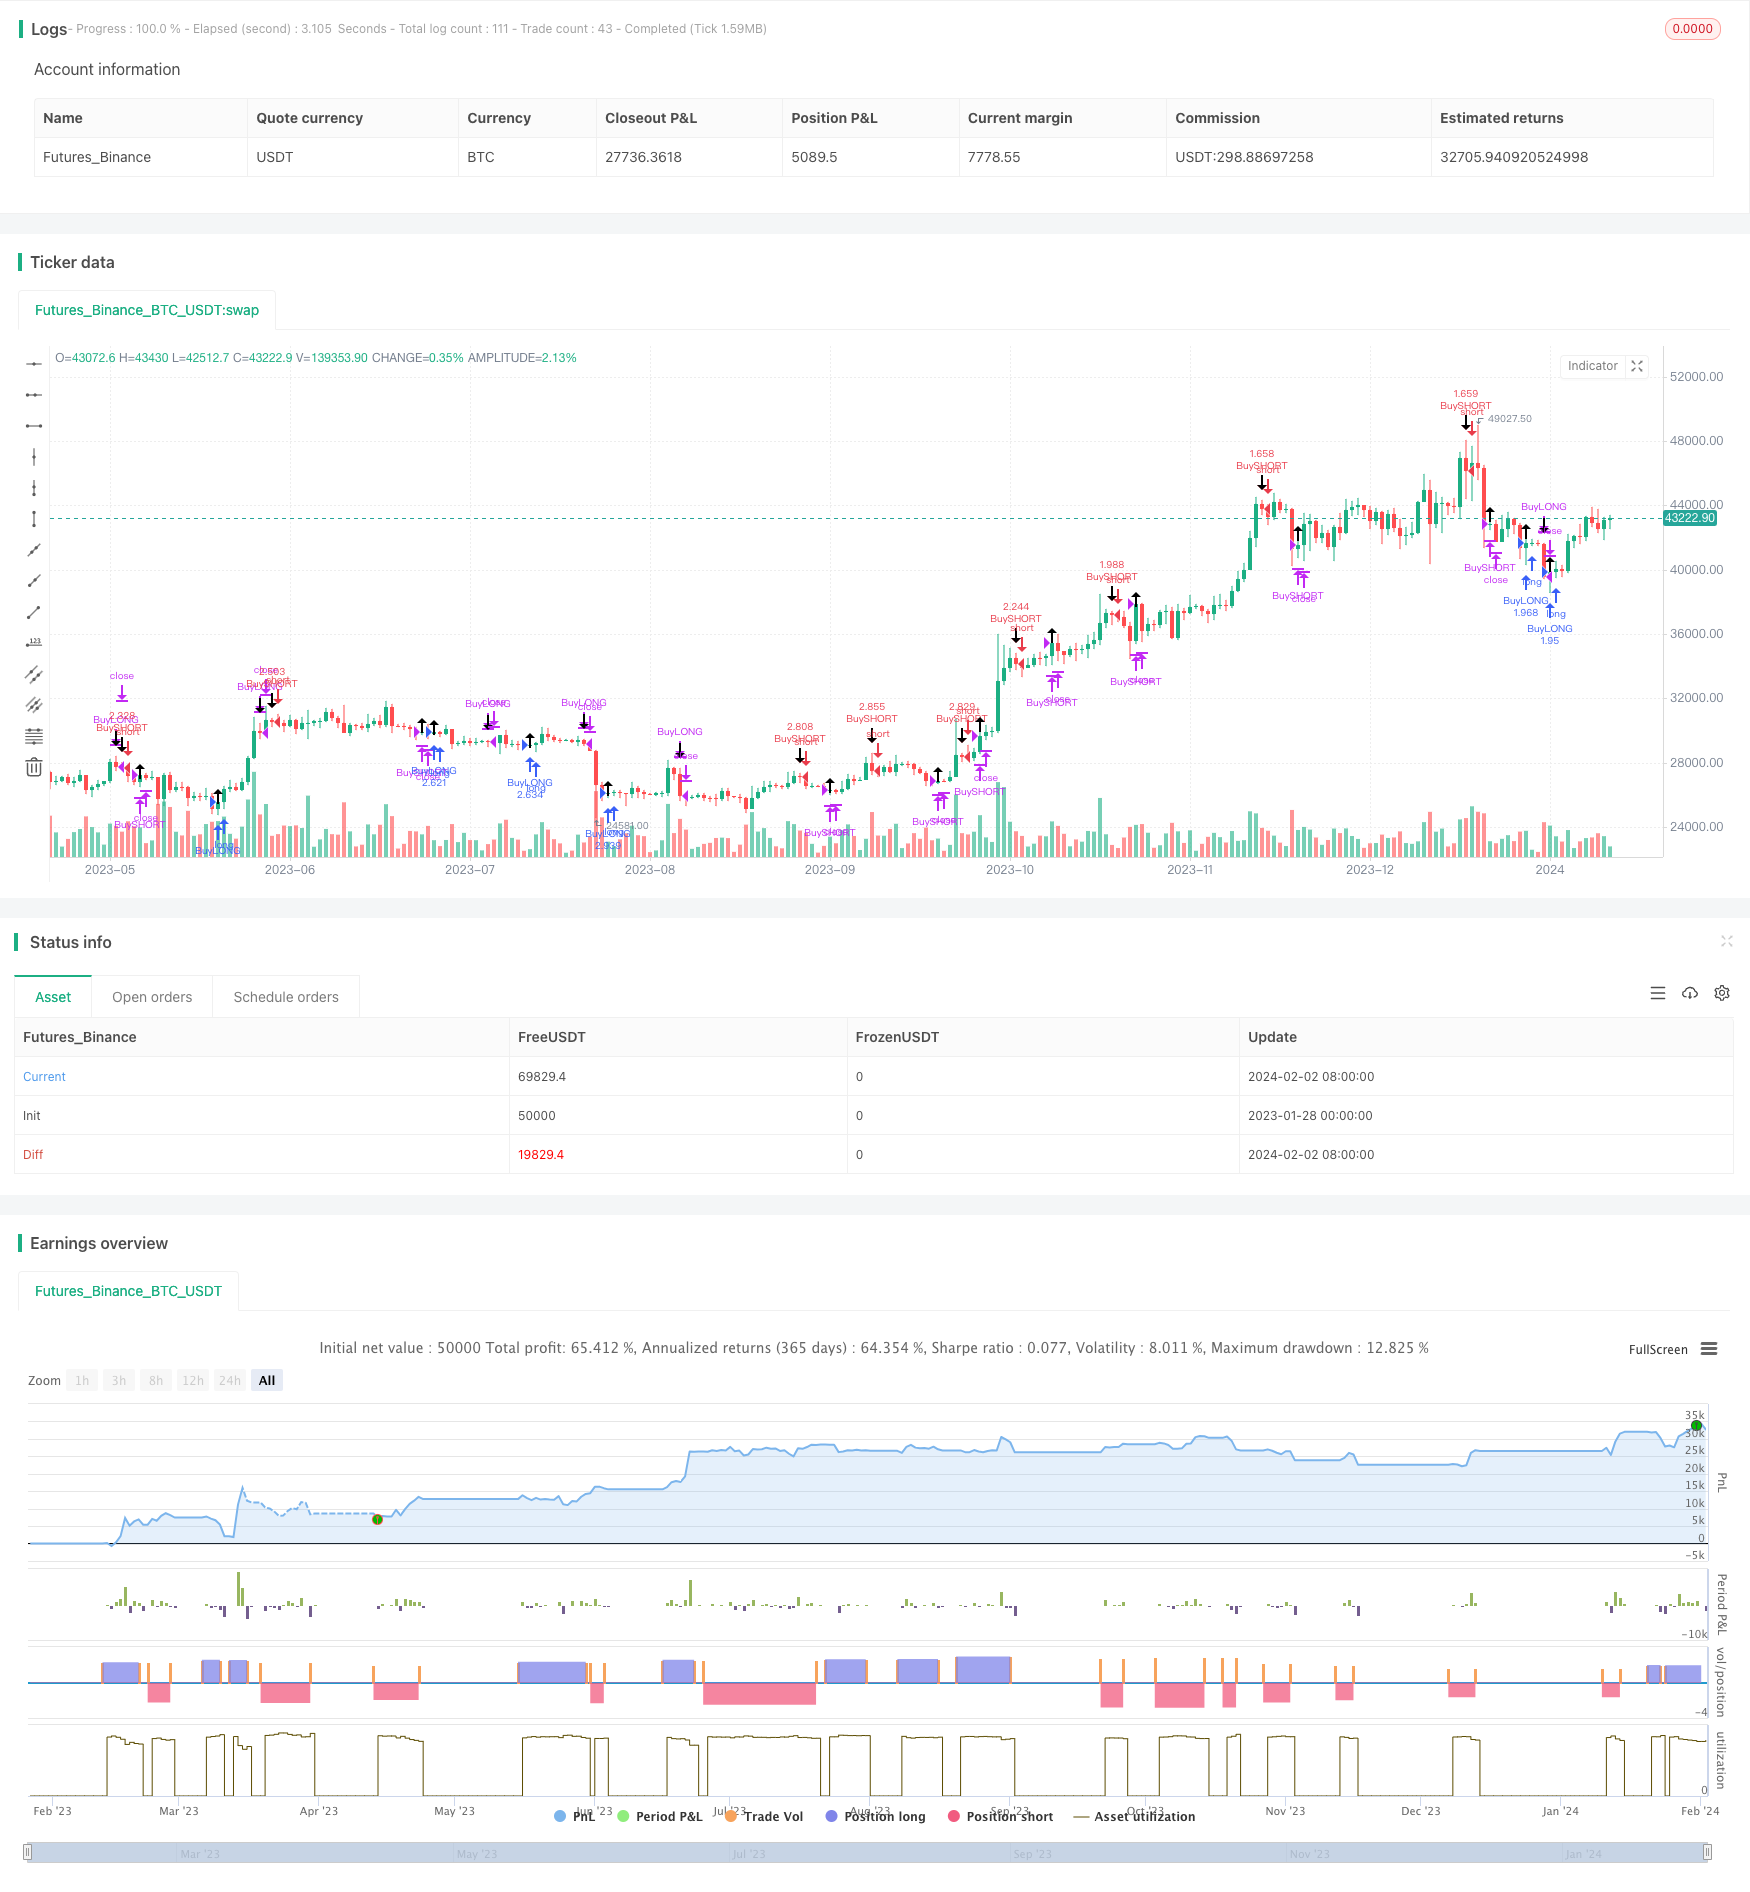
Overview
This strategy is a momentum trading strategy based on multiple technical indicators. The strategy adopts Bollinger Bands, RSI, ATR and other technical indicators to implement a multi-factor model to quickly judge entry when a trend appears. At the same time, the strategy also adopts stop loss, advanced stop profit and other risk control means to effectively control risks.
Strategy Principle
The trading signals of this strategy mainly come from Bollinger Bands. When the price approaches the lower rail of the Bollinger Bands, it is bullish, and when the price approaches the upper rail, it is bearish. In order to filter false breakouts, the strategy additionally incorporates RSI indicator rules. Only when the RSI indicator also confirms that it is currently in the overbought or oversold area will a trading signal be generated.
In addition, the ATR indicator is used in the strategy to implement stop loss and take profit. Specifically, when opening a position, a purchase price will be recorded. Afterwards, trailing stops will be used based on the ATR indicator value to lock in profits and effectively control risks.
Advantage Analysis
The biggest advantage of this strategy is that by using a multi-factor model to synthesize the market, it can effectively judge the structural opportunities in the market. This avoids false signals from a single indicator. At the same time, the built-in stop loss and advanced stop profit mechanism of the strategy can also effectively control risks and avoid excessive losses.
Risk Analysis
The biggest risk of this strategy is that if there is a violent market reversal, the probability that multiple indicators will generate wrong signals at the same time will be relatively large. This will lead to significant losses for the strategy. In addition, when technical indicators issue signals, it may also be the general consensus of the market, prone to herding effects, and thus being trapped.
In order to reduce these risks, we can appropriately adjust the parameters and choose clearer signals. At the same time, more filtering conditions can be added to avoid making wrong trades near market tops and bottoms.
Optimization Directions
The strategy can be optimized in the following directions:
Add more technical indicators to form a more three-dimensional multi-factor model to improve judgment accuracy
Optimize the stop loss logic and choose different stop loss strategies according to different market stages
Use machine learning and other technologies to dynamically optimize parameters and evaluate signal reliability
Incorporate industry, concepts and other information to form an embedded multi-factor model
Summary
By reasonably applying the idea of a multi-factor model, this strategy captures the direction of the trend very well. At the same time, scientific risk control measures also enable the strategy to profit in a controllable manner. Through continuous optimization, it is expected to further improve the stability and profitability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | main strat profit |
| v_input_2 | true | Shorts on/off |
| v_input_3 | false | Flipping on/off -> Go directly from long -> short or short -> long without closing |
| v_input_4 | false | Stoploss on/off |
| v_input_5 | 30 | Stoploss % |
| v_input_6 | true | Trailing on/off |
| v_input_7 | true | Trailing use ATR on/off |
| v_input_8 | true | Multiplier for ATR |
| v_input_9 | 10 | Trailing % |
| v_input_10 | false | backtest date on/off |
| v_input_11 | 2018 | Backtest Start Year |
| v_input_12 | true | Backtest Start Month |
| v_input_13 | true | Backtest Start Day |
| v_input_14 | 2019 | Backtest Stop Year |
| v_input_15 | true | Backtest Stop Month |
| v_input_16 | true | Backtest Stop Day |
| v_input_17 | true | Color Background? |
| v_input_18 | 20 | ATR Length |
| v_input_19 | false | 1 for added ATR when selling |
| v_input_20 | 20 | OC2 Length |
| v_input_21 | false | 1 for added OC2 when selling |
| v_input_22 | true | OC2 multiplayer |
| v_input_23 | 10 | DI Length |
| v_input_24 | 10 | ADX Smoothing |
| v_input_25 | 3 | smoothKRSI |
| v_input_26 | 3 | smoothDRSI |
| v_input_27 | 14 | lengthRSI |
| v_input_28 | 14 | lengthStochRSI |
| v_input_29_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_30 | 30 | RSI Buy Value |
| v_input_31 | 70 | RSI Sell Value |
| v_input_32 | 20 | lengthbb |
| v_input_33_close | 0 | Sourcebb: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_34 | 2 | multbb |
| v_input_35 | 0.5 | BB Buy Value |
| v_input_36 | 0.5 | BB Sell Value |
Source Pine Script
/*backtest
start: 2023-01-28 00:00:00
end: 2024-02-03 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
// THIS SCRIPT IS MEANT TO ACCOMPANY COMMAND EXECUTION BOTS
// THE INCLUDED STRATEGY IS NOT MEANT FOR LIVE TRADING
// THIS STRATEGY IS PURELY AN EXAMLE TO START EXPERIMENTATING WITH YOUR OWN IDEAS
/////////////////////////////////////////////////////////////////////////////////

// comment out the next line to use this script as an alert script
strategy(title="Dragon Bot - Default Script", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)
// remove the // in the next line to use this script as an alert script
// study(title="Dragon Bot - Default Script", overlay=true)

// Dragon-Bot default script version 2.0
// This can also be used with bot that reacts to tradingview alerts.
// Use the script as "strategy" for backtesting
// Comment out line 8 and de-comment line 10 to be able to set tradingview alerts.
// You should also comment out (place // before it) the lines 360, 364, 368 and 372 (strategy.entry and strategy.close) to be able to set the alerts.
/////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
// In this first part of the script we setup variables and make sure the script keeps all information it used in the past. //
/////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////////
longs = 0
longs := nz(longs[1])

shorts = 0
shorts := nz(shorts[1])

buyprice = 0.0
buyprice := buyprice[1]

sellprice = 0.0
sellprice := sellprice[1]

scaler = 0.0
scaler := scaler[1]

sellprofit = input(1.0, minval=0.0, step=0.1, title="main strat profit")
sellproffinal = sellprofit/100

enable_shorts = input(1, minval=0, maxval=1, title="Shorts on/off")

enable_flipping = input(0, minval=0, maxval=1, title="Flipping on/off -> Go directly from long -> short or short -> long without closing ")

enable_stoploss = input(0, minval=0, maxval=1, title="Stoploss on/off")
sellstoploss = input(30.0, minval=0.0, step=1.0, title="Stoploss %")
sellstoplossfinal = sellstoploss/100

enable_trailing = input(1, minval=0, maxval=1, title="Trailing on/off")
enable_trailing_ATR = input(1, minval=0, maxval=1, title="Trailing use ATR on/off")
ATR_Multi = input(1.0, minval=0.0, step=0.1, title="Multiplier for ATR")
selltrailing = input(10.0, minval=0.0, step=1.0, title="Trailing %")
selltrailingfinal = selltrailing/100

Backtestdate = input(0, minval=0, maxval=1, title="backtest date on/off")

// Component Code by pbergden - Start backtest dates
// The following code snippet is taken from an example by pbergen
// All rights to this snippet remain with pbergden
testStartYear = input(2018, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(1, "Backtest Stop Month")
testStopDay = input(1, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

// A switch to control background coloring of the test period
testPeriodBackground = input(title="Color Background?", type=bool, defval=true)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FF00 : na
bgcolor(testPeriodBackgroundColor, transp=97)

testPeriod() => true

/////////////////////////////////////////////////////////////////////////////////////////////////////
// In this second part of the script we setup indicators that we can use for our actual algorithm. //
/////////////////////////////////////////////////////////////////////////////////////////////////////


//ATR
lengthtr = input(20, minval=1, title="ATR Length")
ATRsell = input(0, minval=0, title="1 for added ATR when selling")
ATR=rma(tr(true), lengthtr)
Trail_ATR=rma(tr(true), 10) * ATR_Multi
atr = 0.0
if ATRsell == 1
    atr := ATR

//OC2
lengthoc2 = input(20, minval=1, title="OC2 Length")
OC2sell = input(0, minval=0, title="1 for added OC2 when selling")
OC2mult = input(1, minval=1, title="OC2 multiplayer")
OC= abs(open[1]-close)
OC2=rma(OC, lengthoc2)
oc2 = 0.0
if OC2sell == 1
    oc2 := OC2*OC2mult

//ADX
lenadx = input(10, minval=1, title="DI Length")
lensig = input(10, title="ADX Smoothing", minval=1, maxval=50)

up = change(high)
down = -change(low)
plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
trur = rma(tr, lenadx)
plus = fixnan(100 * rma(plusDM, lenadx) / trur)
minus = fixnan(100 * rma(minusDM, lenadx) / trur)
sum = plus + minus
sigadx = 100 * rma(abs(plus - minus) / (sum == 0 ? 1 : sum), lensig)

//StochRSI
smoothKRSI = input(3, minval=1)
smoothDRSI = input(3, minval=1)
lengthRSI = input(14, minval=1)
lengthStochRSI = input(14, minval=1)
srcRSI = input(close, title="RSI Source")
buyRSI = input(30, minval=1, title="RSI Buy Value")
sellRSI = input(70, minval=1, title="RSI Sell Value")
rsi1 = rsi(srcRSI, lengthRSI)
krsi = sma(stoch(rsi1, rsi1, rsi1, lengthStochRSI), smoothKRSI)
drsi = sma(krsi, smoothDRSI)

// Bollinger bands
lengthbb = input(20, minval=1)
srcbb = input(close, title="Sourcebb")
multbb = input(2.0, minval=0.001, maxval=50)
bb_buy_value = input(0.5, step=0.1, title="BB Buy Value")
bb_sell_value = input(0.5, step=0.1, title="BB Sell Value")
basisbb = sma(srcbb, lengthbb)
devbb = multbb * stdev(srcbb, lengthbb)
upperbb = basisbb + devbb
lowerbb = basisbb - devbb
bbr = (srcbb - lowerbb)/(upperbb - lowerbb)
bbbuy = basisbb - (devbb*bb_buy_value)
bbsell = basisbb + (devbb*bb_sell_value)

//ema very short
shorter = ema(close, 2)
shorterlong = ema(close, 5)

//ema short
short = ema(close, 10)
long = ema(close, 30)

//ema long
shortday = ema(close, 110)
longday = ema(close, 360)

//ema even longer
shortlongerday = ema(close, 240)
longlongerday = ema(close, 720)

//declaring extra timeframe value
profit = request.security(syminfo.tickerid, timeframe.period, close)


////////////////////////////////////////////////////////////////////////
// In the 3rd part of the script we define all the entries and exits //
///////// This third part is basically the acual algorithm ////////////
///////////////////////////////////////////////////////////////////////

//Declaring function with the long entries
OPENLONG_funct() =>
    // You can add more buy entries to the script
    longentry1 = false
    longentry2 = false
    longentry3 = false
    longentry4 = false
    longentry5 = false
    makelong_funct = false
    if  close<bbbuy and krsi<buyRSI // You could for instance add "and shortday > longday"
        longentry1 := close>close[1]
        // longentry2 := ...
    // if another thing we want to buy on happens
        // longentry3 := ...
    //All the buy entries go above, this last variable is what the function puts out
    // if you add more entries, add them in the following list too
    makelong_funct := longentry1 or longentry2 or longentry3 or longentry4 or longentry5

//Declaring function wit the short entries
OPENSHORT_funct() =>
    // You can add more buy entries to the script
    shortentry1 = false
    shortentry2 = false
    shortentry3 = false
    shortentry4 = false
    shortentry5 = false
    makeshort_funct = false
    if  close>bbsell and krsi>sellRSI // You could for instance add "and shortday < longday"
        shortentry1 := close<close[1]
        // shortentry2 := ...
    // if another thing we want to buy on happens
        // shortentry3 := ...
    //All the buy entries go above, this last variable is what the function puts out
    // if you add more entries, add them in the following list too
    makeshort_funct := shortentry1 or shortentry2 or shortentry3 or shortentry4 or shortentry5

//Declaring function with the long exits
CLOSELONG_funct() =>
    // You can add more buy entries to the script
    longexit1 = false
    longexit2 = false
    longexit3 = false
    longexit4 = false
    longexit5 = false
    closelong_funct = false
    if  close>bbsell and krsi>sellRSI
        longexit1 := close<close[1]
        // longexit2 := ...
    // if another thing we want to close on on happens you can add them here...
    // longexit3 := ...
    //All the buy entries go above, this last variable is what the function puts out
    // if you add more exits, add them in the following list too
    closelong_funct := longexit1 or longexit2 or longexit3 or longexit4 or longexit5

//Declaring function wit the short exits
CLOSESHORT_funct() =>
    // You can add more buy entries to the script
    shortexit1 = false
    shortexit2 = false
    shortexit3 = false
    shortexit4 = false
    shortexit5 = false
    closeshort_funct = false
    if  close<bbsell and krsi<sellRSI
        shortexit1 := close>close[1]
        // shortexit2 := ...
    // if another thing we want to close on on happens you can add them here...
        // shortexit3 := ...
    //All the buy entries go above, this last variable is what the function puts out
    // if you add more exits, add them in the following list too
    closeshort_funct := shortexit1 or shortexit2 or shortexit3 or shortexit4 or shortexit5

/////////////////////////////////////////////////////////////////////////////////////
////////////// End of "entries" and "exits" definition code /////////////////////////
/////////////////////////////////////////////////////////////////////////////////////
/// In the fourth part we do the actual work, as defined in the part before this ////
////////////////////// This part does not need to be changed ////////////////////////
/////////////////////////////////////////////////////////////////////////////////////

//OPEN LONG LOGIC
makelong = false
//buy with backtesting on specific dates
if Backtestdate > 0 and testPeriod()
    if (longs < 1 and shorts < 1) or (short > 0 and enable_flipping > 0 and enable_shorts > 0)
        makelong := OPENLONG_funct()

//buy without backtesting on specific dates
if Backtestdate < 1
    if (longs < 1 and shorts < 1) or (short > 0 and enable_flipping > 0 and enable_shorts > 0)
        makelong := OPENLONG_funct()

if makelong
    buyprice := close
    scaler := close
    longs := 1
    shorts := 0

//OPEN SHORT LOGIC
makeshort = false

//buy with backtesting on specific dates
if Backtestdate > 0 and testPeriod()
    if (shorts < 1 and longs < 1 and enable_shorts > 0) or (longs > 0 and enable_flipping > 0 and enable_shorts > 0)
        makeshort := OPENSHORT_funct()

//buy without backtesting on specific dates
if Backtestdate < 1
    if (shorts < 1 and longs < 1 and enable_shorts > 0) or (longs > 0 and enable_flipping > 0 and enable_shorts > 0)
        makeshort := OPENSHORT_funct()


if makeshort
    buyprice := close
    scaler := close
    shorts := 1
    longs := 0

//Calculating values for traling stop
if longs > 0 and enable_flipping < 1
    if close > scaler+Trail_ATR and enable_trailing_ATR > 0
        scaler := close
    if close > scaler * (1.0 + selltrailingfinal) and enable_trailing_ATR < 1
        scaler := close
if shorts > 0 and enable_flipping < 1
    if close < scaler-Trail_ATR and enable_trailing_ATR > 0
        scaler := close
    if close < scaler * (1.0 - selltrailingfinal) and enable_trailing_ATR < 1
        scaler := close

long_exit = false
long_security1 = false
long_security2 = false
long_security3 = false

//CLOSE LONG LOGIC
if longs > 0 and enable_flipping < 1
    if ( (buyprice + (buyprice*sellproffinal) + atr + oc2) < close) and ( (buyprice + (buyprice*sellproffinal) ) < profit)
        long_exit := CLOSELONG_funct()
//security
    if enable_stoploss > 0
        long_security1 := close < ( buyprice * (1.0 - sellstoplossfinal) )
    if enable_trailing > 0 and enable_trailing_ATR < 1
        long_security2 := close < ( scaler * (1.0 - selltrailingfinal) )
    if enable_trailing > 0 and enable_trailing_ATR > 0
        long_security2 := close < ( scaler - Trail_ATR)

//CLOSE LONG LOGIC
if longs > 0 and enable_flipping > 0
//security
    if enable_stoploss > 0
        long_security1 := close < ( buyprice * (1.0 - sellstoplossfinal) )
    if enable_trailing > 0 and enable_trailing_ATR < 1
        long_security2 := close < ( scaler * (1.0 - selltrailingfinal) )
    if enable_trailing > 0 and enable_trailing_ATR > 0
        long_security2 := close < ( scaler - Trail_ATR)

closelong = long_exit or long_security1 or long_security2 or long_security3

short_exit = false
short_security1 = false
short_security2 = false
short_security3 = false

if closelong
    longs := 0

//CLOSE SHORT LOGIC
if shorts > 0 and enable_flipping < 1
    if ( (buyprice - (buyprice*(sellproffinal) - atr - oc2) > close) and ( (buyprice - (buyprice*sellproffinal) ) > profit) )
        short_exit := CLOSESHORT_funct()
//security
    if enable_stoploss > 0
        short_security1 := close > ( buyprice * (1.0 + sellstoplossfinal) )
    if enable_trailing > 0 and enable_trailing_ATR < 1
        short_security2 := close > ( scaler * (1.0 + selltrailingfinal) )
    if enable_trailing > 0 and enable_trailing_ATR > 0
        short_security2 := close > ( scaler + Trail_ATR)
if shorts > 0 and enable_flipping > 0
//security
    if enable_stoploss > 0
        short_security1 := close > ( buyprice * (1.0 + sellstoplossfinal) )
    if enable_trailing > 0 and enable_trailing_ATR < 1
        short_security2 := close > ( scaler * (1.0 + selltrailingfinal) )
    if enable_trailing > 0 and enable_trailing_ATR > 0
        short_security2 := close > ( scaler + Trail_ATR)

closeshort = short_exit or short_security1 or short_security2 or short_security3

if closeshort
    shorts := 0

///////////////////////////////////////////////////////////////////////////////////////
///////////// The last section takes care of the alerts //////////////////////////////
//////////////////////////////////////////////////////////////////////////////////////
plotshape(makelong, style=shape.arrowup)
alertcondition(makelong, title="openlong", message="openlong")
strategy.entry("BuyLONG", strategy.long, oca_name="DBCross",  when= makelong, comment="Open Long")

plotshape(makeshort, style=shape.arrowdown)
alertcondition(makeshort, title="openshort", message="openshort")
strategy.entry("BuySHORT", strategy.short, oca_name="DBCross",  when= makeshort, comment="Open Short")

plotshape(closelong, style=shape.arrowdown)
alertcondition(closelong, title="closelong", message="closelong")
strategy.close("BuyLONG", when=closelong)

plotshape(closeshort, style=shape.arrowup)
alertcondition(closeshort, title="closeshort", message="closeshort")
strategy.close("BuySHORT", when=closeshort)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Trading-Strategy-Based-on-Multi-factor-Model.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Multi Indicator Dynamic Stop Loss Momentum Trend Trading StrategyPine Script · Momentum · 1h
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy An Optimized Quantitative Trading System Based on Bollinger Bands Fibonacci and ATRPine Script · Momentum · 1h