Momentum Trend Following Strategy 444336
This strategy combines the Aroon indicator and the Absolute Strength Histogram (ASH) to identify market trends and potential trading opportunities. Aroon helps determine the strength and direction of trends, while…
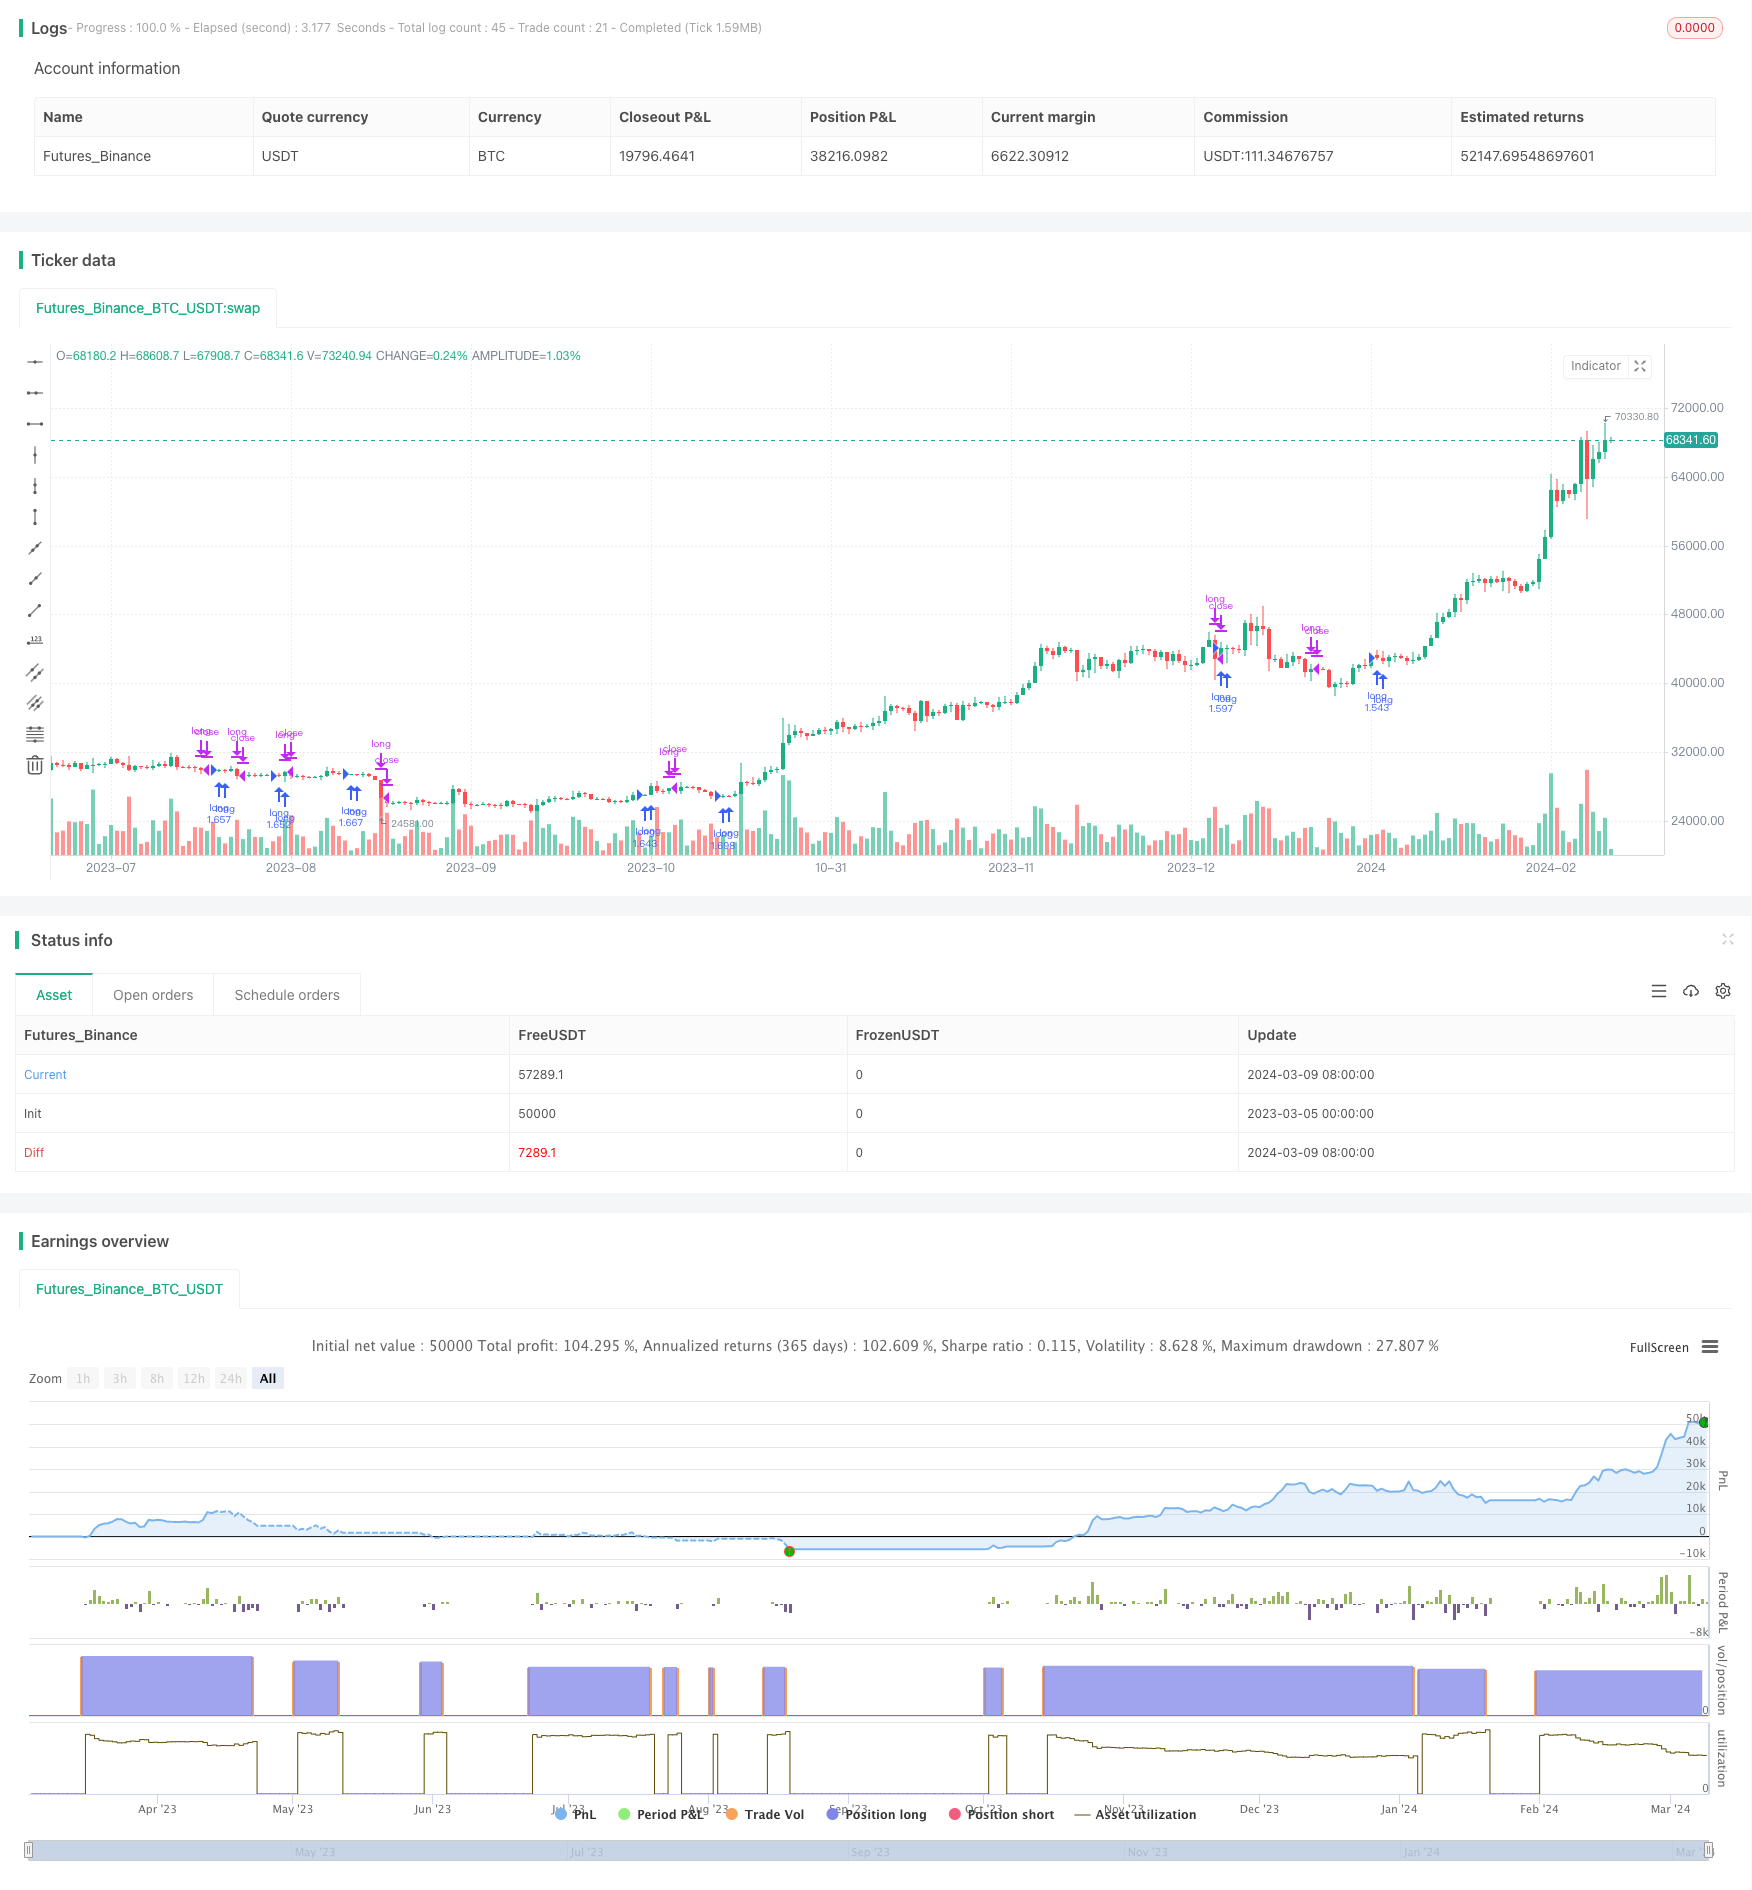
Overview
This strategy combines the Aroon indicator and the Absolute Strength Histogram (ASH) to identify market trends and potential trading opportunities. Aroon helps determine the strength and direction of trends, while ASH provides insights into the momentum strength. By combining these indicators, the strategy aims to capture profitable trades in Ethereum markets.
Strategy Logic
The strategy uses two sets of parameters for the Aroon indicator:
- Long Positions: Aroon periods are 56 (upper) and 20 (lower)
- Short Positions: Aroon periods are 17 (upper) and 55 (lower)
The ASH is calculated with a length of 9 bars using the closing price as the data source.
The strategy incorporates specific entry and exit rules:
- Long Entry: A long position is initiated when the Aroon indicator crosses over the lower threshold, signaling a potential uptrend.
- Long Exit: A long position is closed when the Aroon crosses back under the lower threshold.
- Short Entry: A short position is initiated when the Aroon crosses under the upper threshold, signaling a potential downtrend.
- Short Exit: A short position is closed when the Aroon crosses back over the upper threshold.
Advantage Analysis
The main advantage of this strategy is the synergy from combining the two indicators. Aroon effectively gauges trend direction and strength. ASH provides additional momentum insights to aid with timing entry and exit signals.
Using two Aroon parameters allows flexibility in adapting to changing market conditions.
Risk Analysis
The main limitations stem from the indicators themselves. Aroon struggles during range-bound markets and can generate false signals. ASH is also prone to overreactions in the short term.
Inappropriate parameter settings could also impact performance. The long/short periods of Aroon and length of ASH would need optimization to find the ideal combinations.
Improvement Directions
Additional filters could be added, such as price breakouts or rising volumes, to avoid false signals during choppy conditions.
Different parameter combinations and weights could be tested to find optimal settings. Other indicators like RSI or KD could also complement the strategy.
Conclusion
The strategy effectively combines the strengths of Aroon and ASH for dual-confirmation of trends and turning points. But parameters and indicator limitations still need refinement. The creative concept shows promise for further improvements and testing.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 56 | length_upper_long |
| v_input_int_2 | 20 | length_lower_long |
| v_input_int_3 | 17 | length_upper_short |
| v_input_int_4 | 55 | length_lower_short |
| v_input_1 | 9 | Length |
| v_input_2_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | timestamp(01 Jan 2018 00:00) | Start Date |
| v_input_string_1 | 0 | Trade Direction: Long | Short | Both |
Source Pine Script
/*backtest
start: 2023-03-05 00:00:00
end: 2024-03-10 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// © IkkeOmar

//@version=5
strategy("Aroon and ASH strategy - ETHERIUM [IkkeOmar]", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, pyramiding=1, commission_value=0, slippage=2)


// AROON SETTINGS ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------

// Inputs for longs

length_upper_long = input.int(56, minval=15)
length_lower_long = input.int(20, minval=5)

// Inputs for shorts
//Aroon Short Side Inputs
length_upper_short = input.int(17, minval=10)
length_lower_short = input.int(55)

// ABSOLUTE STRENGTH HISTOGRAM SETTINGS ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
length = input(title='Length', defval=9)
src = input(title='Source', defval=close)


// CALCULATIONS: ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------
// Aroon
upper_long = 100 * (ta.highestbars(high, length_upper_long + 1) + length_upper_long) / length_upper_long
lower_long = 100 * (ta.lowestbars(low, length_lower_long + 1) + length_lower_long) / length_lower_long

upper_short = 100 * (ta.highestbars(high, length_upper_short + 1) + length_upper_short) / length_upper_short
lower_short = 100 * (ta.lowestbars(low, length_lower_short + 1) + length_lower_short) / length_lower_short

// Ahrens Moving Average
ahma = 0.0
ahma := nz(ahma[1]) + (src - (nz(ahma[1]) + nz(ahma[length])) / 2) / length


// CONDITIONS: ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------


// Options that configure the backtest start date
startDate = input(title='Start Date', defval=timestamp('01 Jan 2018 00:00'))


// Option to select trade directions
tradeDirection = input.string(title='Trade Direction', options=['Long', 'Short', 'Both'], defval='Long')

// Translate input into trading conditions
longOK = tradeDirection == 'Long' or tradeDirection == 'Both'
shortOK = tradeDirection == 'Short' or tradeDirection == 'Both'


// Check if the close time of the current bar falls inside the date range
inDateRange = true

longCondition = ta.crossover(upper_long, lower_long) and inDateRange and lower_long >= 5 and longOK
longCloseCondition = ta.crossunder(upper_long, lower_long) and inDateRange

shortCondition = ta.crossunder(upper_short, lower_short) and inDateRange and shortOK
shortCloseCondition = ta.crossover(upper_short, lower_short) and inDateRange

// Start off with the initial states for the longs and shorts
var in_short_trade = false
var in_long_trade = false

var long_signal = false
var short_signal = false

if longCondition
    long_signal := true
if longCloseCondition
    long_signal := false

if shortCondition
    short_signal := true
if shortCloseCondition
    short_signal := false

// While no trades active and short condition is met, OPEN short
if true and in_short_trade == false and in_long_trade == false and shortCondition
    strategy.entry("short", strategy.short, when = shortCondition)
    in_short_trade := true
    in_long_trade := false

// While no trades and long condition is met, OPEN LONG
if true and in_short_trade == false and in_long_trade == false and longCondition
    strategy.entry("long", strategy.long, when = longCondition)
    in_long_trade := true
    in_short_trade := false


// WHILE short trade and long condition is met, CLOSE SHORT and OPEN LONG
if true and in_short_trade == true and in_long_trade == false and longCondition
    // strategy.close("short", when = longCondition)
    strategy.entry("long", strategy.long, when = longCondition)
    in_short_trade := false
    in_long_trade := true


// WHILE long trade and short condition is met, CLOSE LONG and OPEN SHORT
if true and in_short_trade == false and in_long_trade == true and shortCondition
    // strategy.close("long", when = shortCondition)
    strategy.entry("short", strategy.short, when = shortCondition)
    in_short_trade := true
    in_long_trade := false

// WHILE long trade and exit long condition is met, CLOSE LONG
// if short signal is active, OPEN SHORT
if true and in_short_trade == false and in_long_trade == true and longCloseCondition
    if short_signal
        strategy.entry("short", strategy.short, when = short_signal)
        in_long_trade := false
        in_short_trade := true
    else
        strategy.close("long", when = longCloseCondition)
        in_long_trade := false
        in_short_trade := false

// if in short trade only and exit short condition is met, close the short
// if long signal still active, OPEN LONG
if true and in_short_trade == true and in_long_trade == false and shortCloseCondition
    if long_signal
        strategy.entry("long", strategy.long, when = long_signal)
        in_short_trade := false
        in_long_trade := true
    else
        strategy.close("short", when = shortCloseCondition)
        in_short_trade := false
        in_long_trade := false
Published by ChaoZhang on the FMZ strategy square · last modified 2024-03-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Momentum-Trend-Following-Strategy-444336.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Cross Momentum Trend Following Strategy SMA RSI Cross Momentum SystemPine Script · Momentum · 1h
- Cross Period Momentum EMA Strategy with RSI and Dynamic ATR Stop LossPine Script · Momentum · 1d
- Dual EMA Crossover with RSI Momentum Enhanced Trading StrategyPine Script · Momentum · 1d