Moving Average Channel Breakout Trading Strategy
This strategy is based on the golden cross and death cross principles of simple moving averages, making buy and sell decisions based on the crossover of 7-day and 14-day moving averages. It generates a buy signal…
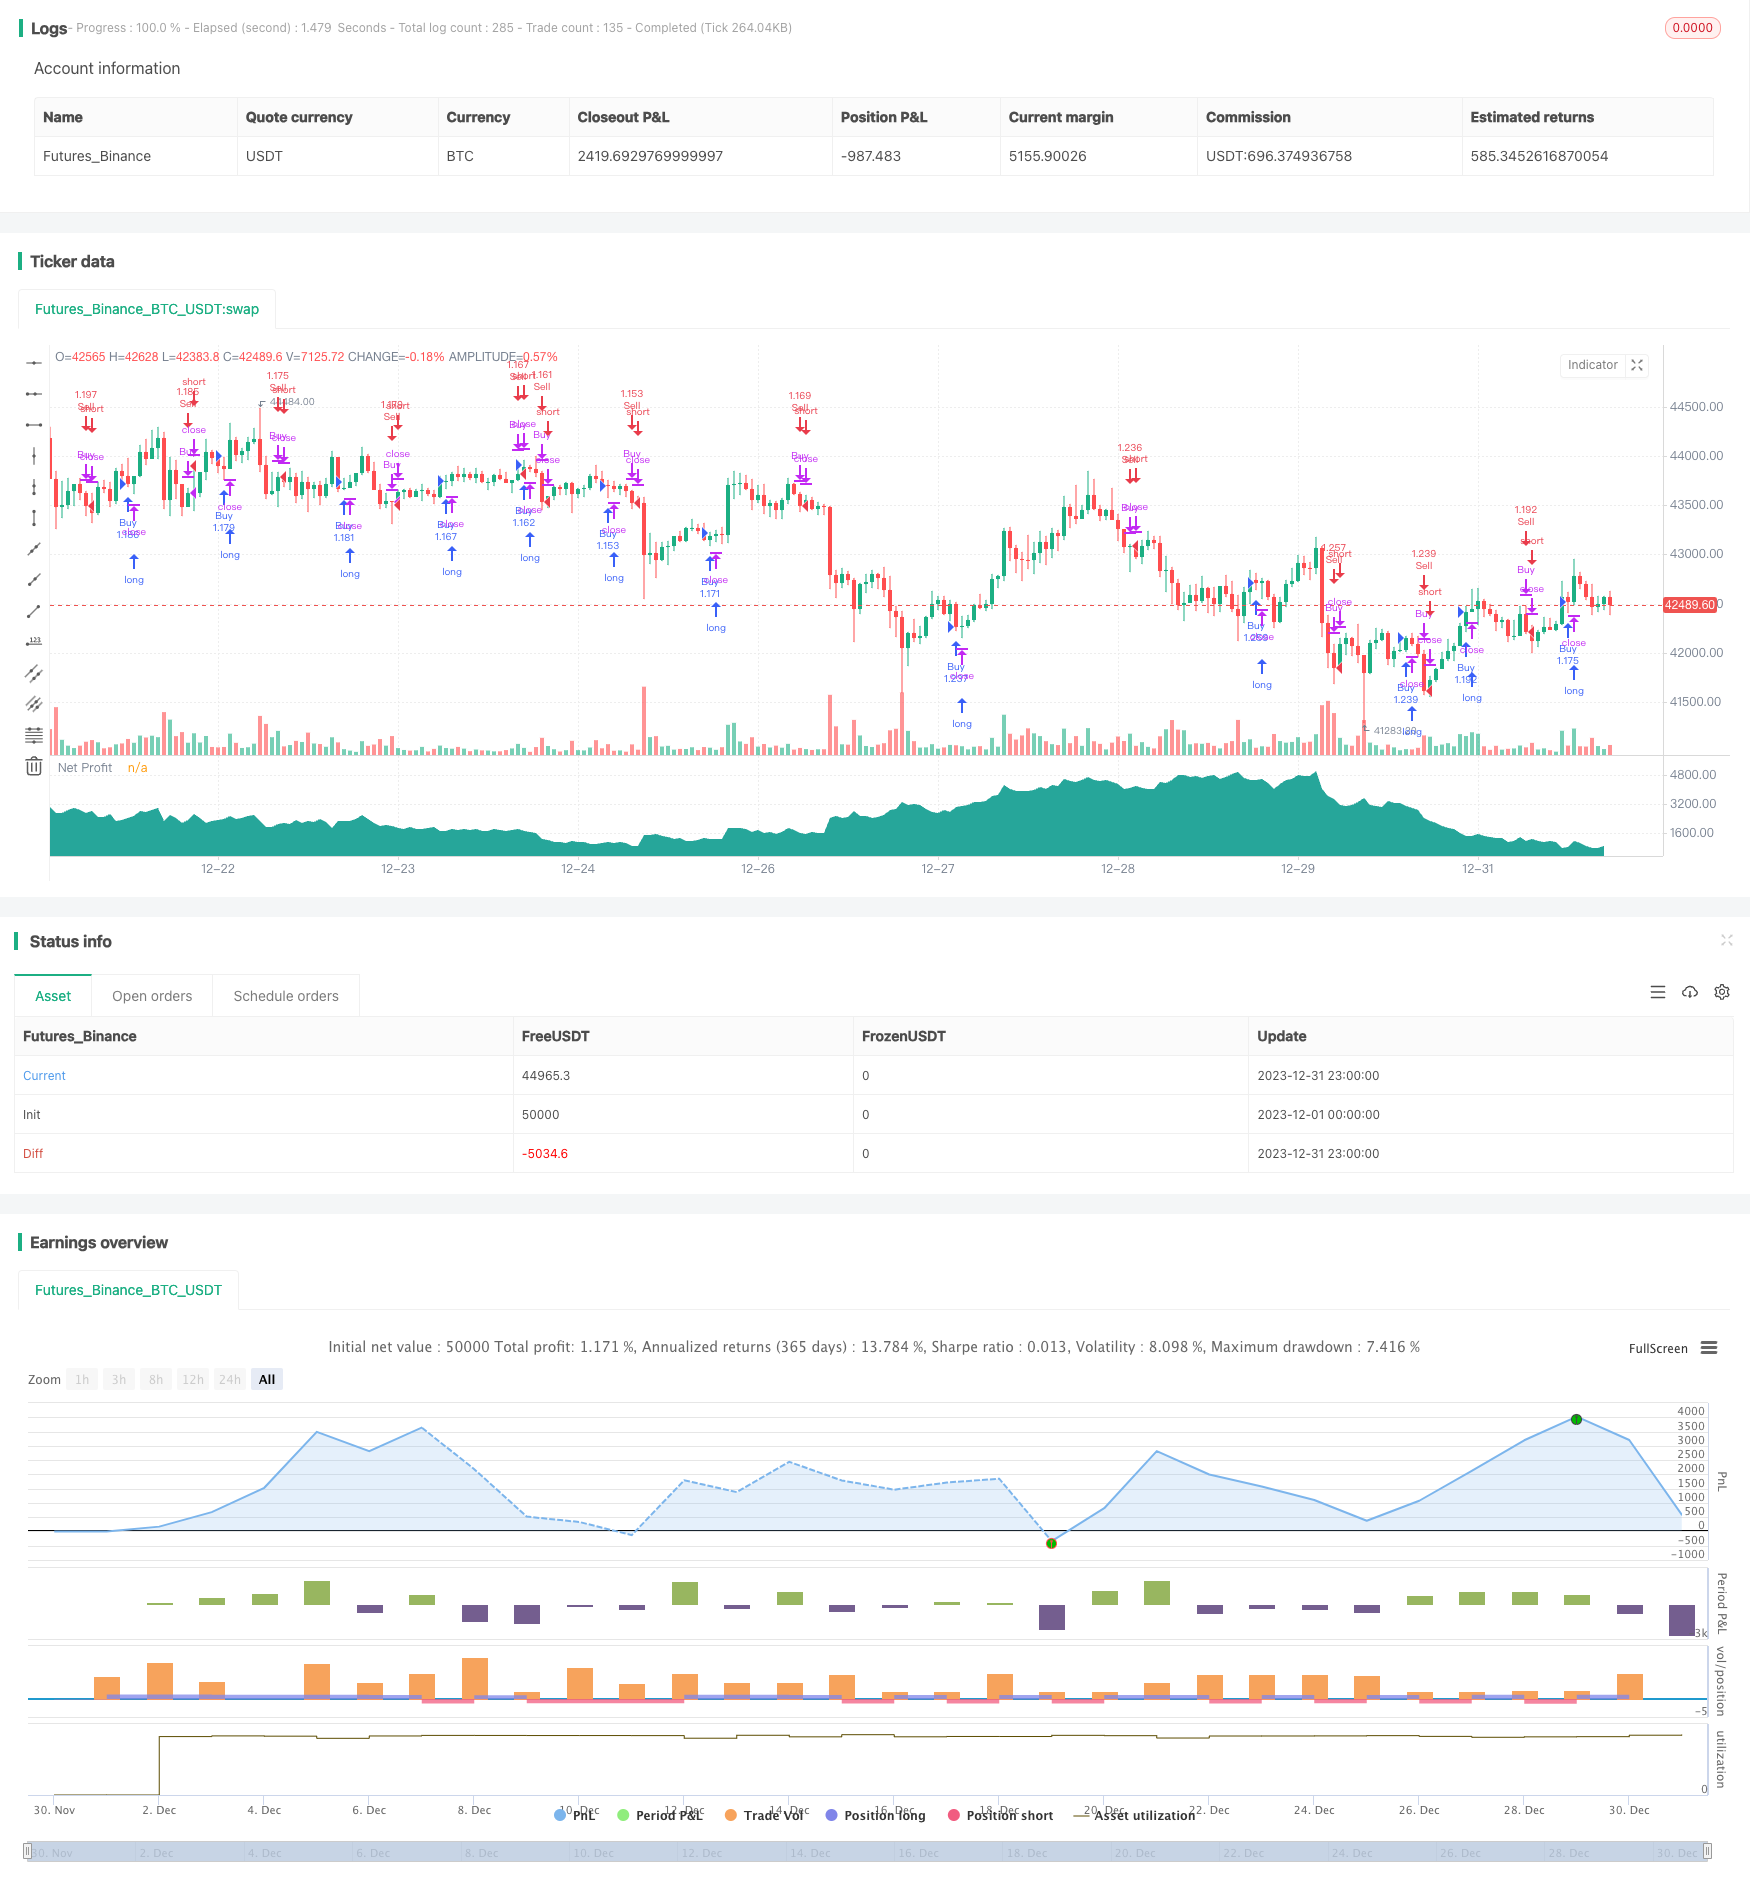
Overview
This strategy is based on the golden cross and death cross principles of simple moving averages, making buy and sell decisions based on the crossover of 7-day and 14-day moving averages. It generates a buy signal when the 7-day MA crosses above the 14-day MA from below, and a sell signal when the 7-day MA crosses below the 14-day MA from above. The strategy also features stop loss, take profit, and trailing stop functions to lock in profits and control risks.
Strategy Logic
The core trading logic of this strategy is based on the crossover principles of the 7-day and 14-day moving averages. The 7-day MA reflects short-term price trends, while the 14-day MA reflects medium-term trends. When the short-term MA crosses above the medium-term MA from below, it signals that the short-term trend is strengthening, making it a good time to go long. Conversely, when the short-term MA crosses below the medium-term MA from above, it signals that the short-term trend is weakening, so one should close positions or go short.
Specifcally, this strategy calculates the 7-day and 14-day simple moving averages using the SMA indicator. After each candlestick forms, it compares the current values of the 7-day line and the 14-day line. If the 7-day line crosses above the 14-day line, a long signal is generated to go long. If the 7-day line crosses below the 14-day line, a short signal is generated to go short.
In addition, the strategy also sets stop loss, take profit, and trailing stop functions to lock in profits and control risks. The parameters can be optimized based on backtest results.
Advantages
This strategy has the following advantages:
- Simple and clear rules, easy to understand and implement, suitable for beginners to learn.
- Moving average crossover principles are time-tested and effective, with relatively high win rates.
- Equipped with stop loss, take profit and trailing stop to effectively control risks.
- Few parameters, convenient for testing and optimization.
Risks and Countermeasures
There are also some risks with this strategy:
- Moving averages may lag in reflecting trend changes, potentially causing large losses when trends reverse.
- Frequent crossover signals duringranging markets generate more false signals, undermining strategy efficacy.
To address these risks, the following countermeasures can be considered:
- Add other indicators like MACD and KDJ to filter crossover signals and avoid wrong signals at trend turning points.
- Expand stop loss range, shorten holding period to reduce single loss impact.
- Optimize moving average parameters based on varying market conditions, using longer periods for ranging markets.
Optimization Directions
This strategy can be optimized in the following aspects:
- Test different MA combinations and parameters to find the optimal setup.
- Add other indicators for signal filtering to improve strategy efficacy.
- Optimize stop loss, take profit parameters to reduce drawdown and increase profit ratio.
- Fine tune parameters based on different products and trading sessions.
Conclusion
In conclusion, this strategy is very suitable for beginners to learn. The logic is simple and easy to understand and implement. It also has relatively good market adaptiveness, with ample room for parameter adjustment and optimization to achieve steady profits. It is worthwhile for quantitative trading beginners to use it for getting started and learning.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2019 | backtest_year |
| v_input_2 | true | backtest_month |
| v_input_3 | true | backtest_day |
| v_input_4 | true | Enable Stop Loss and Take Profit |
| v_input_5 | true | Enable Trail Stop |
| v_input_6 | 0.2 | buy_stop_loss |
| v_input_7 | 0.1 | sell_stop_loss |
| v_input_8 | 0.4 | buy_tp |
| v_input_9 | 0.2 | sell_tp |
| v_input_10 | 1.1 | trail_stop_long |
| v_input_11 | 0.9 | trail_stop_short |
| v_input_12 | 0.05 | trail_stop_long_offset |
| v_input_13 | 0.05 | trail_stop_short_offset |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © bensonsuntw

strategy("Strategy Template[Benson]", pyramiding=1, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

backtest_year = input(2019, type=input.integer, title='backtest_year')
backtest_month = input(01, type=input.integer, title='backtest_month', minval=1, maxval=12)
backtest_day = input(01, type=input.integer, title='backtest_day', minval=1, maxval=31)
start_time = timestamp(backtest_year, backtest_month, backtest_day, 00, 00)
stop_loss_and_tp = input(title="Enable Stop Loss and Take Profit", type=input.bool, defval=true)
trail_stop = input(title="Enable Trail Stop", type=input.bool, defval=true)
buy_stop_loss = input(0.2, type=input.float, title='buy_stop_loss')
sell_stop_loss = input(0.1, type=input.float, title='sell_stop_loss')
buy_tp = input(0.4, type=input.float, title='buy_tp')
sell_tp =input(0.2, type=input.float, title='sell_tp')
trail_stop_long = input(1.1, type=input.float, title='trail_stop_long')
trail_stop_short = input(0.9, type=input.float, title='trail_stop_short')
trail_stop_long_offset = input(0.05, type=input.float, title='trail_stop_long_offset')
trail_stop_short_offset = input(0.05, type=input.float, title='trail_stop_short_offset')


// you can set your own logic here
shortCondition = crossunder(sma(close,7),sma(close,14))
longCondition = crossover(sma(close,7),sma(close,14))

strategy.entry("Buy", strategy.long, when=longCondition  )
strategy.close("Buy", when=shortCondition)
strategy.exit("Close Buy","Buy", limit= stop_loss_and_tp?strategy.position_avg_price * (1+buy_tp):na, stop = stop_loss_and_tp?strategy.position_avg_price * (1-buy_stop_loss):na,trail_price=trail_stop?strategy.position_avg_price *trail_stop_long:na,trail_offset=trail_stop?-strategy.position_avg_price *trail_stop_long_offset:na)

strategy.entry("Sell", strategy.short, when=shortCondition)
strategy.close("Sell", when=longCondition)
strategy.exit("Close Sell","Sell", limit= stop_loss_and_tp?strategy.position_avg_price * (1-sell_tp):na, stop = stop_loss_and_tp?strategy.position_avg_price * (1+sell_stop_loss):na,trail_price=trail_stop?strategy.position_avg_price *trail_stop_short:na,trail_offset=trail_stop?strategy.position_avg_price *trail_stop_short_offset:na)


net_profit = strategy.netprofit + strategy.openprofit

plot(net_profit, title="Net Profit", linewidth=2, style=plot.style_area, transp=50, color=net_profit >= 0 ? #26A69A : color.red)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Channel-Breakout-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on ADX IndicatorPine Script · Breakout · 1d
- Average Line Breakthrough StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Bull Flag Breakout StrategyPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h