Strategy vault / Trend following
Moving Average Crossover System
This is a trend-following strategy based on moving average crossover signals. When the fast moving average crosses above the slow moving average from below, a buy signal is generated. When the fast moving average…
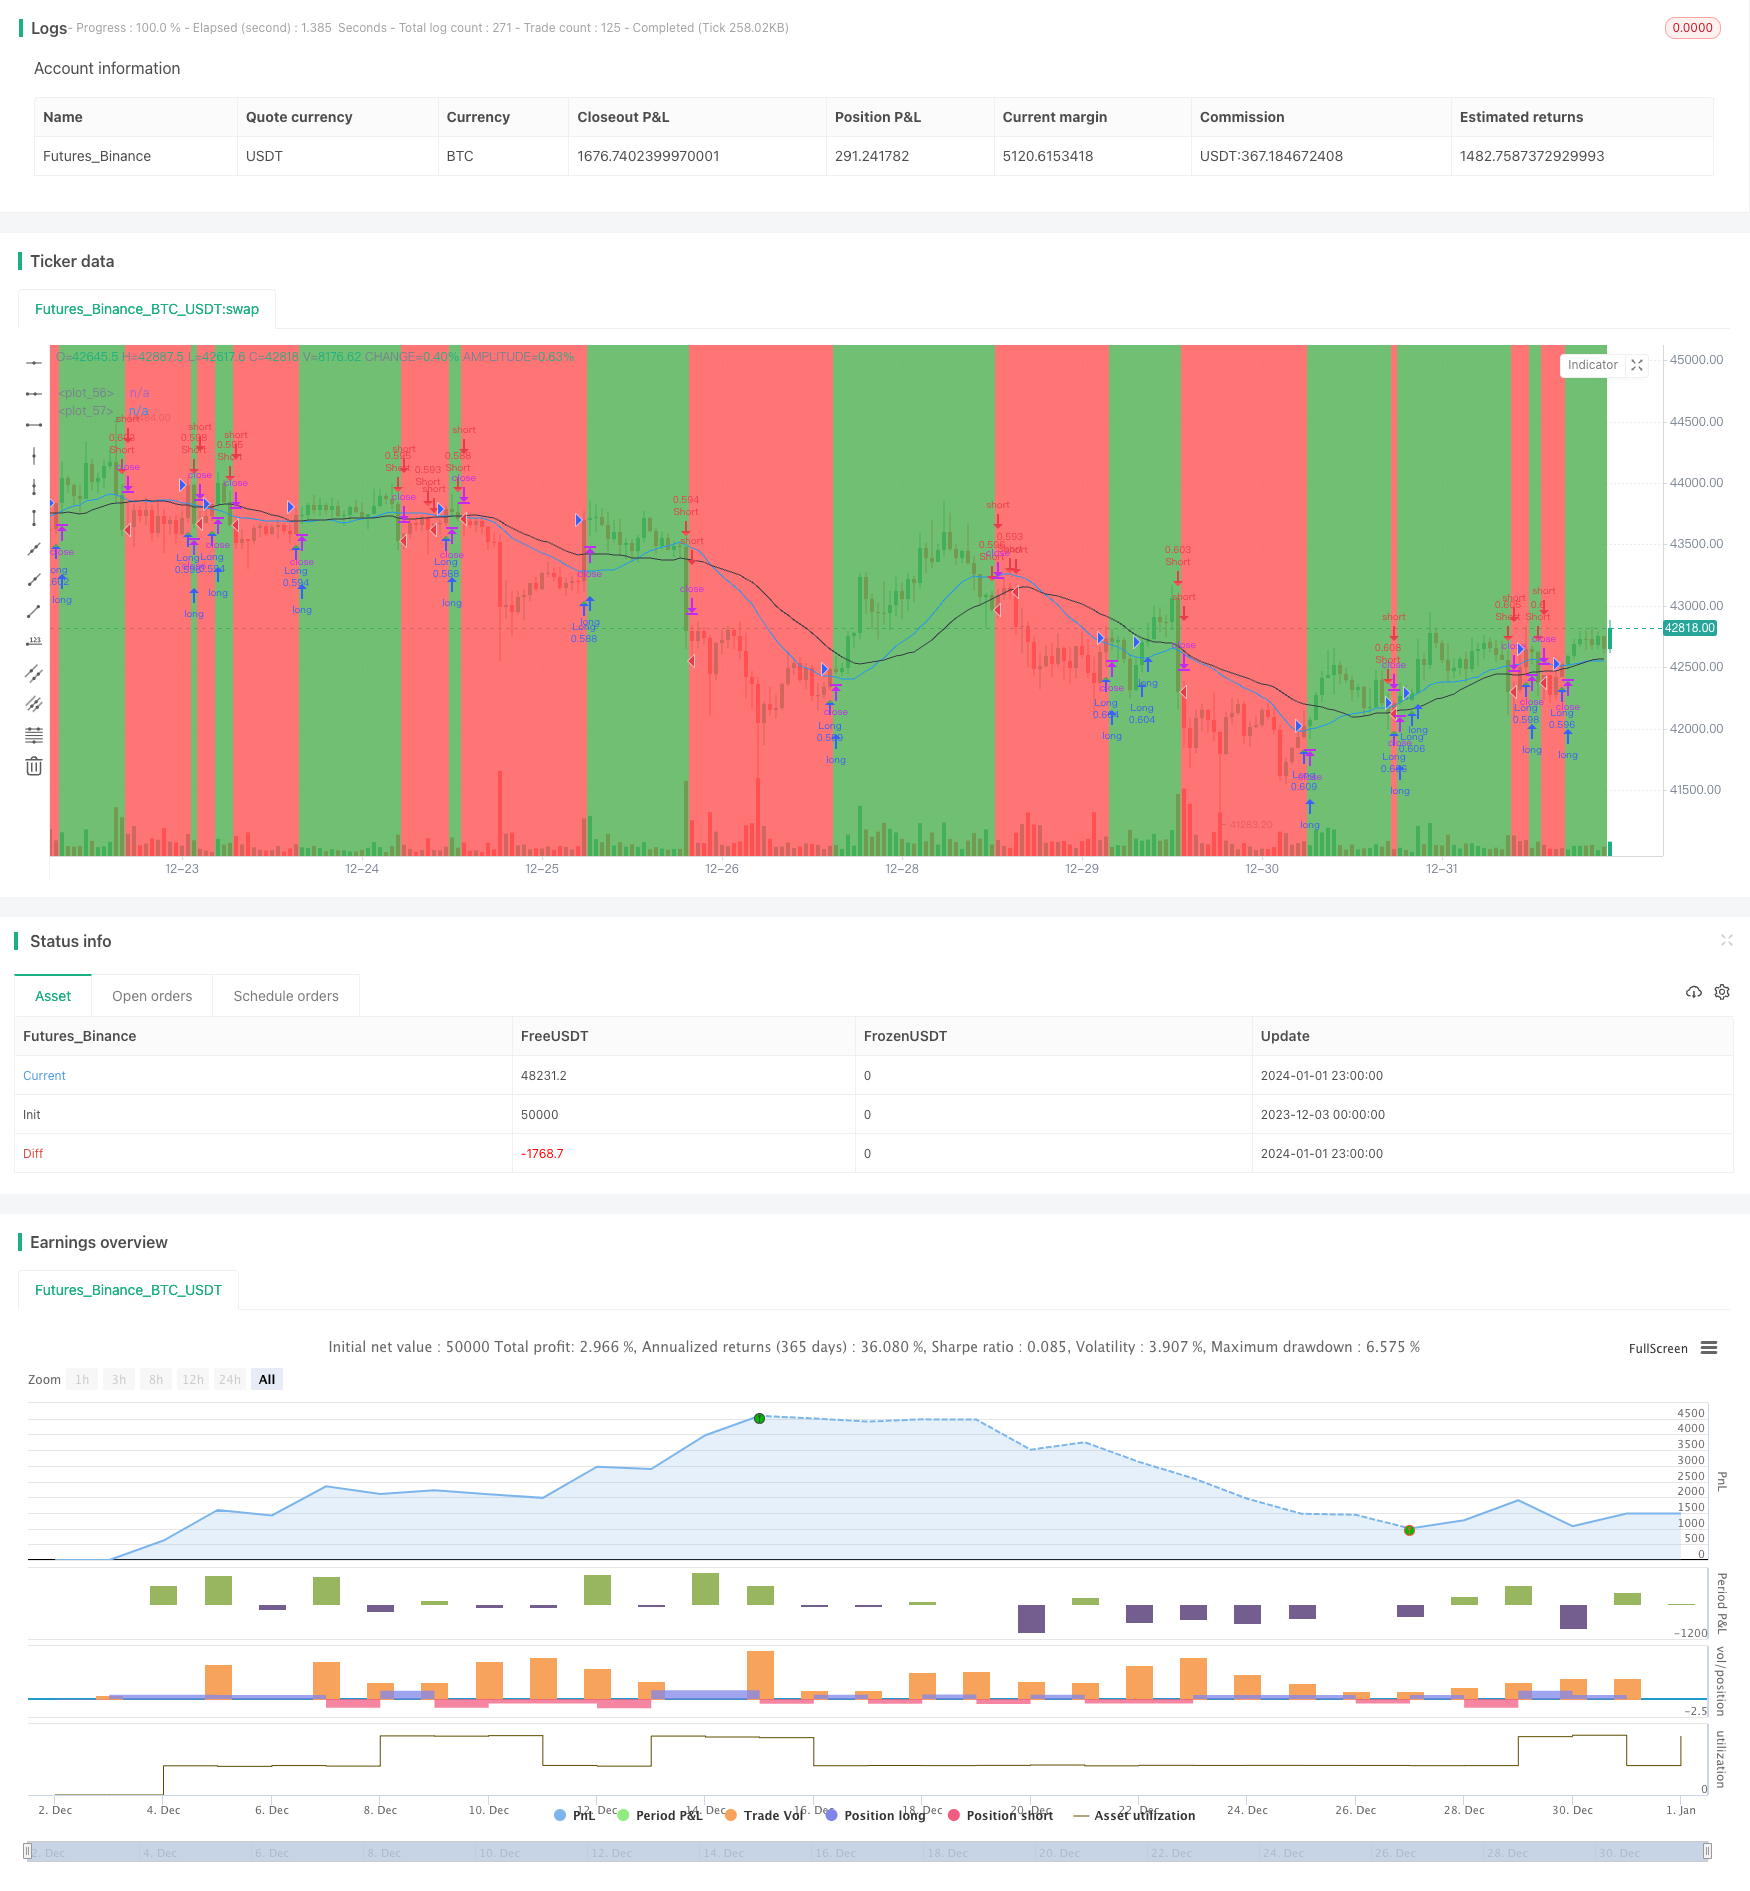
Overview
This is a trend-following strategy based on moving average crossover signals. When the fast moving average crosses above the slow moving average from below, a buy signal is generated. When the fast moving average crosses below the slow moving average from above, a sell signal is generated.
Strategy Logic
The strategy uses two moving averages, a 20-period simple moving average and a 30-period simple moving average. When the 20-period MA crosses above the 30-period MA, a buy signal is generated. When the 20-period MA crosses below the 30-period MA, a sell signal is triggered.
The moving averages themselves serve as trend indicators, depicting the market trend direction effectively. The crossover principle allows the strategy to capture trend reversal points timely and generate trading signals. The 20-day and 30-day periods are set appropriately to reflect the market trend without being too sensitive to noise.
Advantage Analysis
The main advantages of this strategy are:
- The logic is simple and clear, easy to understand and implement, suitable for beginners;
- Trading along the trend avoids counter-trend positions and unnecessary losses;
- The moving averages have a filtering effect to remove market noise and avoid false signals;
- The parameter settings are reasonable not to cause too much sensitivity.
Risk Analysis
The main risks of this strategy include:
- Frequent stop loss orders may be triggered during market consolidation when moving average crossover happens frequently;
- Missing some profits due to the lagging nature of moving averages during strong trends;
- Inappropriate parameter settings may affect the stability.
Solutions:
- Adjust the moving average periods, use triangle moving averages etc to smooth the curves and reduce crossover frequency;
- Use other indicators to determine the trend, avoid trading during consolidation;
- Optimize parameters to find the best combination.
Optimization Directions
The main aspects to optimize the strategy:
- Test different types of moving averages, like weighted moving average, triangular moving average etc;
- Add other technical indicators to avoid signals during consolidation;
- Incorporate other analysis techniques like Elliott Waves, channel theory to determine the trend;
- Adopt machine learning models to optimize parameters dynamically;
- Utilize quant tools and apply stop loss/profit taking techniques to refine money management.
Conclusion
The moving average crossover system is a simple and effective trend following strategy. The logic is clear and easy to understand, very suitable for beginners to learn. It generates trading signals based on moving average crossovers and profits from trading along the trend. The strategy can be optimized in many ways to become more stable and efficient.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long Trades enabled |
| v_input_2 | true | Short Trades enabled |
| v_input_3 | 0 | Buy/Long Crossover Condition: price x MA1 | price x MA2 | MA1 x MA2 |
| v_input_4 | 0 | Sell/Short Crossunder Condition: price x MA2 | price x MA1 | MA1 x MA2 |
| v_input_5 | 0 | Moving Average 1 Type: SMA | EMA |
| v_input_6 | 20 | Moving Average 1 Len |
| v_input_7 | 0 | Moving Average 2 Type: SMA | EMA |
| v_input_8 | 30 | Moving Average 2 Len |
| v_input_9 | 4 | Strategy Start Month |
| v_input_10 | 2018 | Strategy Start Year |
| v_input_11 | 12 | Strategy End Month |
| v_input_12 | 2020 | Strategy End Year |
Source Pine Script
/*backtest
start: 2023-12-03 00:00:00
end: 2024-01-02 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © gliese581d

//@version=4
strategy(title="Moving Averages Testing", overlay=true, precision=2, calc_on_every_tick=false, max_bars_back=5000, pyramiding=2,
 default_qty_type=strategy.percent_of_equity, default_qty_value=50, commission_type=strategy.commission.percent, initial_capital=10000)


//SETTINGS

longs_on = input(title="Long Trades enabled", defval=true)
shorts_on = input(title="Short Trades enabled", defval=true)

long_cond = input(title="Buy/Long Crossover Condition", defval="price x MA1", options=["price x MA1", "price x MA2", "MA1 x MA2"])
short_cond = input(title="Sell/Short Crossunder Condition", defval="price x MA2", options=["price x MA1", "price x MA2", "MA1 x MA2"])

ma1_type = input(title="Moving Average 1 Type", defval="SMA", options=["SMA", "EMA"])
ma1_len = input(defval=20, title="Moving Average 1 Len", type=input.integer, minval=1, maxval=1000, step=1)
ma2_type = input(title="Moving Average 2 Type", defval="SMA", options=["SMA", "EMA"])
ma2_len = input(defval=30, title="Moving Average 2 Len", type=input.integer, minval=1, maxval=1000, step=1)


//MOVING AVERAGES

ma_1 = ma1_type == "EMA" ? ema(close, ma1_len) : sma(close, ma1_len)
ma_2 = ma2_type == "EMA" ? ema(close, ma2_len) : sma(close, ma2_len)


//STRATEGY

//trade entries
long_entry = long_cond == "price x MA1" ? crossover(close, ma_1) : long_cond == "price x MA2" ? crossover(close, ma_2) : long_cond == "MA1 x MA2" ? crossover(ma_1, ma_2) : false
short_entry = short_cond == "price x MA1" ? crossunder(close, ma_1) : short_cond == "price x MA2" ? crossunder(close, ma_2) : short_cond == "MA1 x MA2" ? crossunder(ma_1, ma_2) : false

start_month = input(defval=4, title="Strategy Start Month", type=input.integer, minval=1, maxval=12, step=1)
start_year = input(defval=2018, title="Strategy Start Year", type=input.integer, minval=2000, maxval=2025, step=1)
end_month = input(defval=12, title="Strategy End Month", type=input.integer, minval=1, maxval=12, step=1)
end_year = input(defval=2020, title="Strategy End Year", type=input.integer, minval=2000, maxval=2025, step=1)

in_time =true

strategy.entry("Long", strategy.long, when=longs_on and in_time and long_entry)
strategy.close("Long", when=longs_on and not shorts_on and short_entry)

strategy.entry("Short", strategy.short, when=shorts_on and in_time and short_entry)
strategy.close("Short", when=shorts_on and not longs_on and long_entry)


//PLOTTING

//color background
last_entry_was_long = nz(barssince(long_entry)[1], 5000) < nz(barssince(short_entry)[1], 5000)
bgcol = (longs_on and last_entry_was_long) ? color.green : (shorts_on and not last_entry_was_long) ? color.red : na
bgcolor(color=bgcol, transp=90)

plot((long_cond == "price x MA1" or long_cond == "MA1 x MA2") or (short_cond == "price x MA1" or short_cond == "MA1 x MA2") ? ma_1 : na, color=color.blue)
plot((long_cond == "price x MA2" or long_cond == "MA1 x MA2") or (short_cond == "price x MA2" or short_cond == "MA1 x MA2") ? ma_2 : na, color=color.black)
plotshape(long_entry, style=shape.triangleup, location=location.belowbar, color=color.green)
plotshape(short_entry, style=shape.triangledown, location=location.abovebar, color=color.red)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d