Multi timeframe Fair Value Gap Breakout Strategy with Historical Backtest
This strategy is a comprehensive trading system that combines multi-timeframe analysis, Fair Value Gap (FVG), and Break of Structure (BOS). It identifies potential trading entries by detecting structure breakouts on…
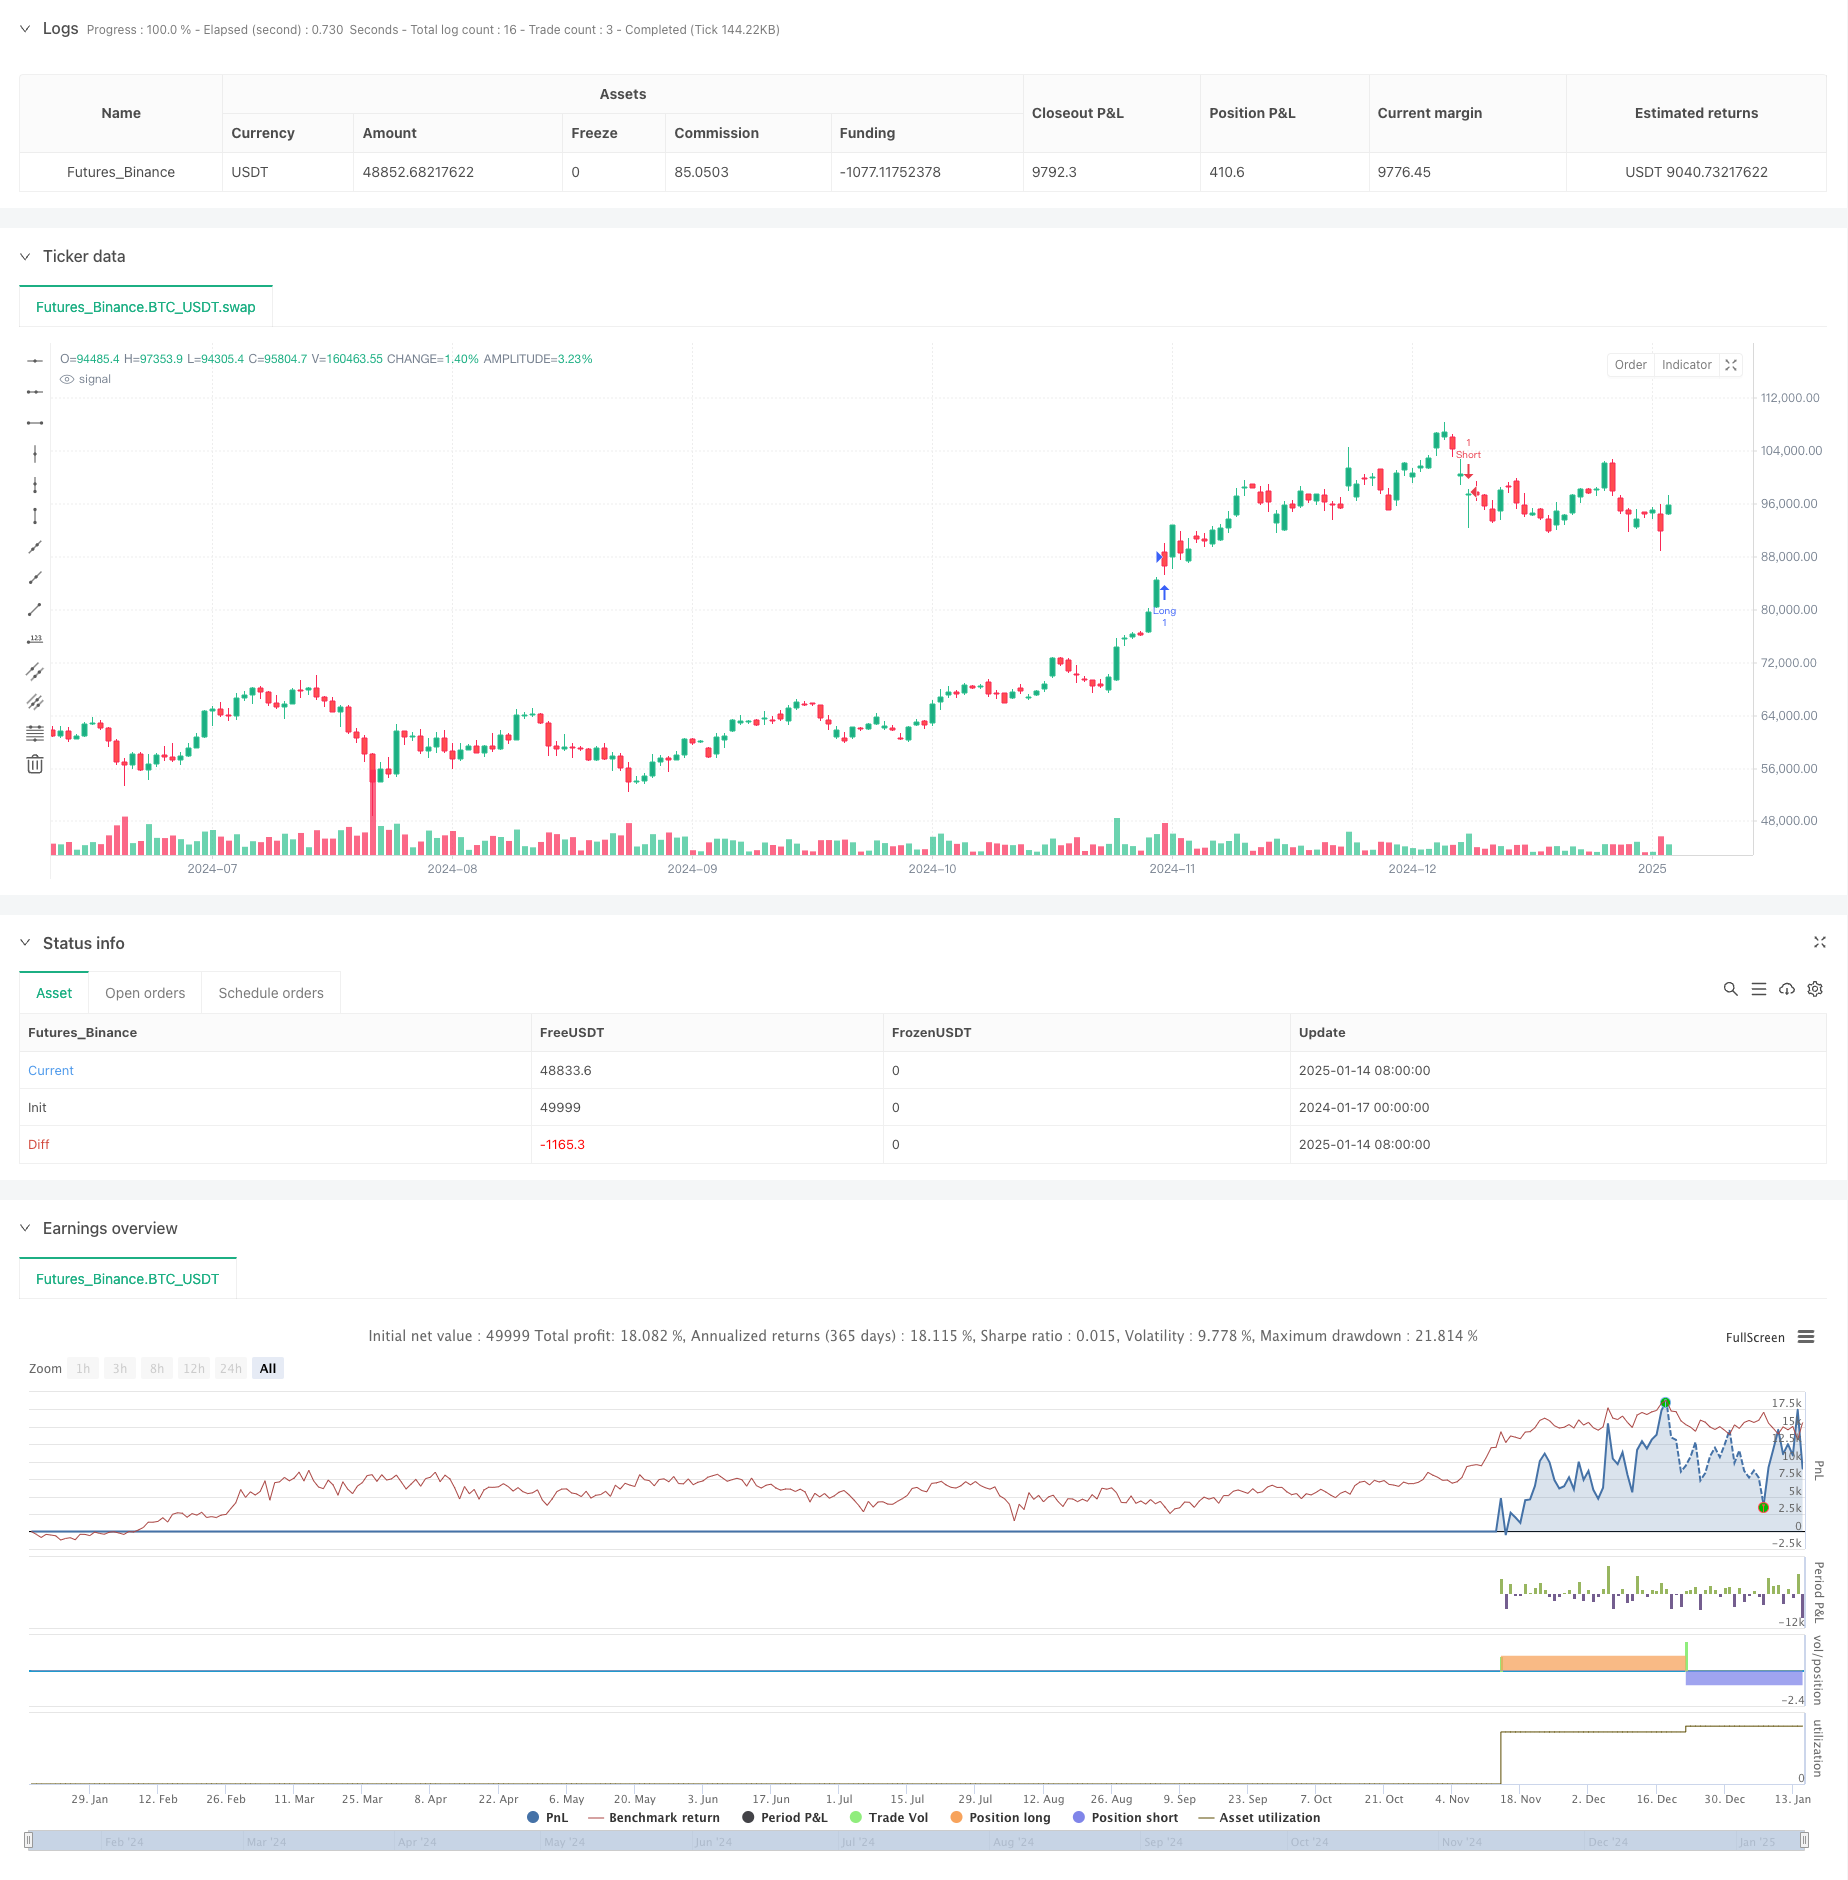
Strategy Overview
This strategy is a comprehensive trading system that combines multi-timeframe analysis, Fair Value Gap (FVG), and Break of Structure (BOS). It identifies potential trading entries by detecting structure breakouts on higher timeframes while looking for fair value gap opportunities on lower timeframes. The strategy also incorporates a risk management system with automated stop-loss and take-profit settings.
Strategy Principles
The core logic is built on three main pillars: First, it uses a higher timeframe (default 1 hour or above) to identify Break of Structure (BOS), which provides the foundational framework for trading direction. Second, it looks for Fair Value Gaps (FVG) on lower timeframes, indicating potential supply-demand imbalances in those areas. Finally, it combines these conditions with current price position to trigger trading signals when price is in favorable locations. The system manages risk through risk-reward ratios and stop-loss factors.
Strategy Advantages
- Multi-dimensional Analysis: Combines multiple timeframe analysis to enhance signal reliability.
- Comprehensive Risk Management: Built-in risk-reward settings and stop-loss control mechanisms ensure clear risk management for each trade.
- Visual Feedback: Strategy provides clear visual feedback including FVG box display and potential trade opportunity markers.
- High Adaptability: Through parameter adjustment, the strategy can adapt to different market conditions and trading styles.
Strategy Risks
- False Breakout Risk: Markets may exhibit false breakouts leading to incorrect trading signals. Solution is to add signal confirmation mechanisms.
- Signal Delay: Due to the use of higher timeframe data, there may be signal lag. Recommended to combine with other technical indicators for confirmation.
- Market Volatility Risk: During high volatility periods, FVG formation may not be stable. Can be addressed by adjusting the FVG observation length.
Strategy Optimization Directions
- Signal Filtering: Add volume confirmation mechanism to confirm signals only when supported by volume.
- Dynamic Parameters: Dynamically adjust risk-reward ratio and stop-loss factor based on market volatility.
- Trend Filtering: Add trend identification indicators to only take positions in trend direction.
- Time Filtering: Add trading session filters to avoid trading during unfavorable market periods.
Summary
This strategy constructs a complete trading system through the comprehensive use of multi-timeframe analysis, price structure breakouts, and fair value gaps. Its strengths lie in its multi-dimensional analysis approach and comprehensive risk management mechanisms, but traders still need to optimize parameters and control risks according to actual market conditions. Further optimization can focus on signal confirmation, dynamic parameter adjustment, and market environment filtering to further improve strategy stability and reliability.
Source Pine Script
/*backtest
start: 2024-01-17 00:00:00
end: 2025-01-15 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

//@version=5
strategy("ICT Strategy with Historical Backtest", overlay=true)

// === Настройки ===
tf = input.timeframe("60", title="Higher Timeframe (1H or above)")  // Таймфрейм для анализа BOS
fvg_length = input(3, title="FVG Lookback Length")                   // Длина для поиска FVG
risk_reward = input(2, title="Risk-Reward Ratio")                    // Риск-вознаграждение
show_fvg_boxes = input(true, title="Show FVG Boxes")                 // Показывать FVG
stop_loss_factor = input.float(1.0, title="Stop Loss Factor")         // Множитель для стоп-лосса

// === Переменные для анализа ===
var float bos_high = na
var float bos_low = na

// Получаем данные с более старшего таймфрейма
htf_high = request.security(syminfo.tickerid, tf, high)
htf_low = request.security(syminfo.tickerid, tf, low)
htf_close = request.security(syminfo.tickerid, tf, close)

// Определение BOS (Break of Structure) на старшем таймфрейме
bos_up = ta.highest(htf_high, fvg_length) > ta.highest(htf_high[1], fvg_length)
bos_down = ta.lowest(htf_low, fvg_length) < ta.lowest(htf_low[1], fvg_length)

// Обновляем уровни BOS
if (bos_up)
    bos_high := ta.highest(htf_high, fvg_length)
if (bos_down)
    bos_low := ta.lowest(htf_low, fvg_length)

// === Определение FVG (Fair Value Gap) ===
fvg_up = low > high[1] and low[1] > high[2]
fvg_down = high < low[1] and high[1] < low[2]

// Визуализация FVG (Fair Value Gap)
// if (show_fvg_boxes)
//     if (fvg_up)
//         box.new(left=bar_index[1], top=high[1], right=bar_index, bottom=low, bgcolor=color.new(color.green, 90), border_color=color.green)
//     if (fvg_down)
//         box.new(left=bar_index[1], top=high, right=bar_index, bottom=low[1], bgcolor=color.new(color.red, 90), border_color=color.red)

// === Логика сделок ===
// Условия для входа в Лонг
long_condition = bos_up and fvg_up and close < bos_high
if (long_condition)
    strategy.entry("Long", strategy.long, stop=low * stop_loss_factor, limit=low + (high - low) * risk_reward)

// Условия для входа в Шорт
short_condition = bos_down and fvg_down and close > bos_low
if (short_condition)
    strategy.entry("Short", strategy.short, stop=high * stop_loss_factor, limit=high - (high - low) * risk_reward)

// === Надписи для прогнозируемых сделок ===
if (long_condition)
    label.new(bar_index, low, text="Potential Long", color=color.green, style=label.style_label_up, textcolor=color.white, size=size.small)

if (short_condition)
    label.new(bar_index, high, text="Potential Short", color=color.red, style=label.style_label_down, textcolor=color.white, size=size.small)
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-timeframe-Fair-Value-Gap-Breakout-Strategy-with-Historical-Backtest.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- Dual Thrust StrategyPine Script · Breakout · 10m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- Dynamic Dual Moving Average Breakthrough Trading System Dynamic Dual Moving Average Breakthrough Trading SystemPine Script · Breakout · 1d
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d