Strategy vault / Trend following
Multi Timeframe Moving Average and EMA Based Trend Strategy
This strategy utilizes moving averages (MA) and EMA across different timeframes to identify and trade trends. By combining SMA, EMA of various periods, as well as candlestick bodies, it can effectively filter market…
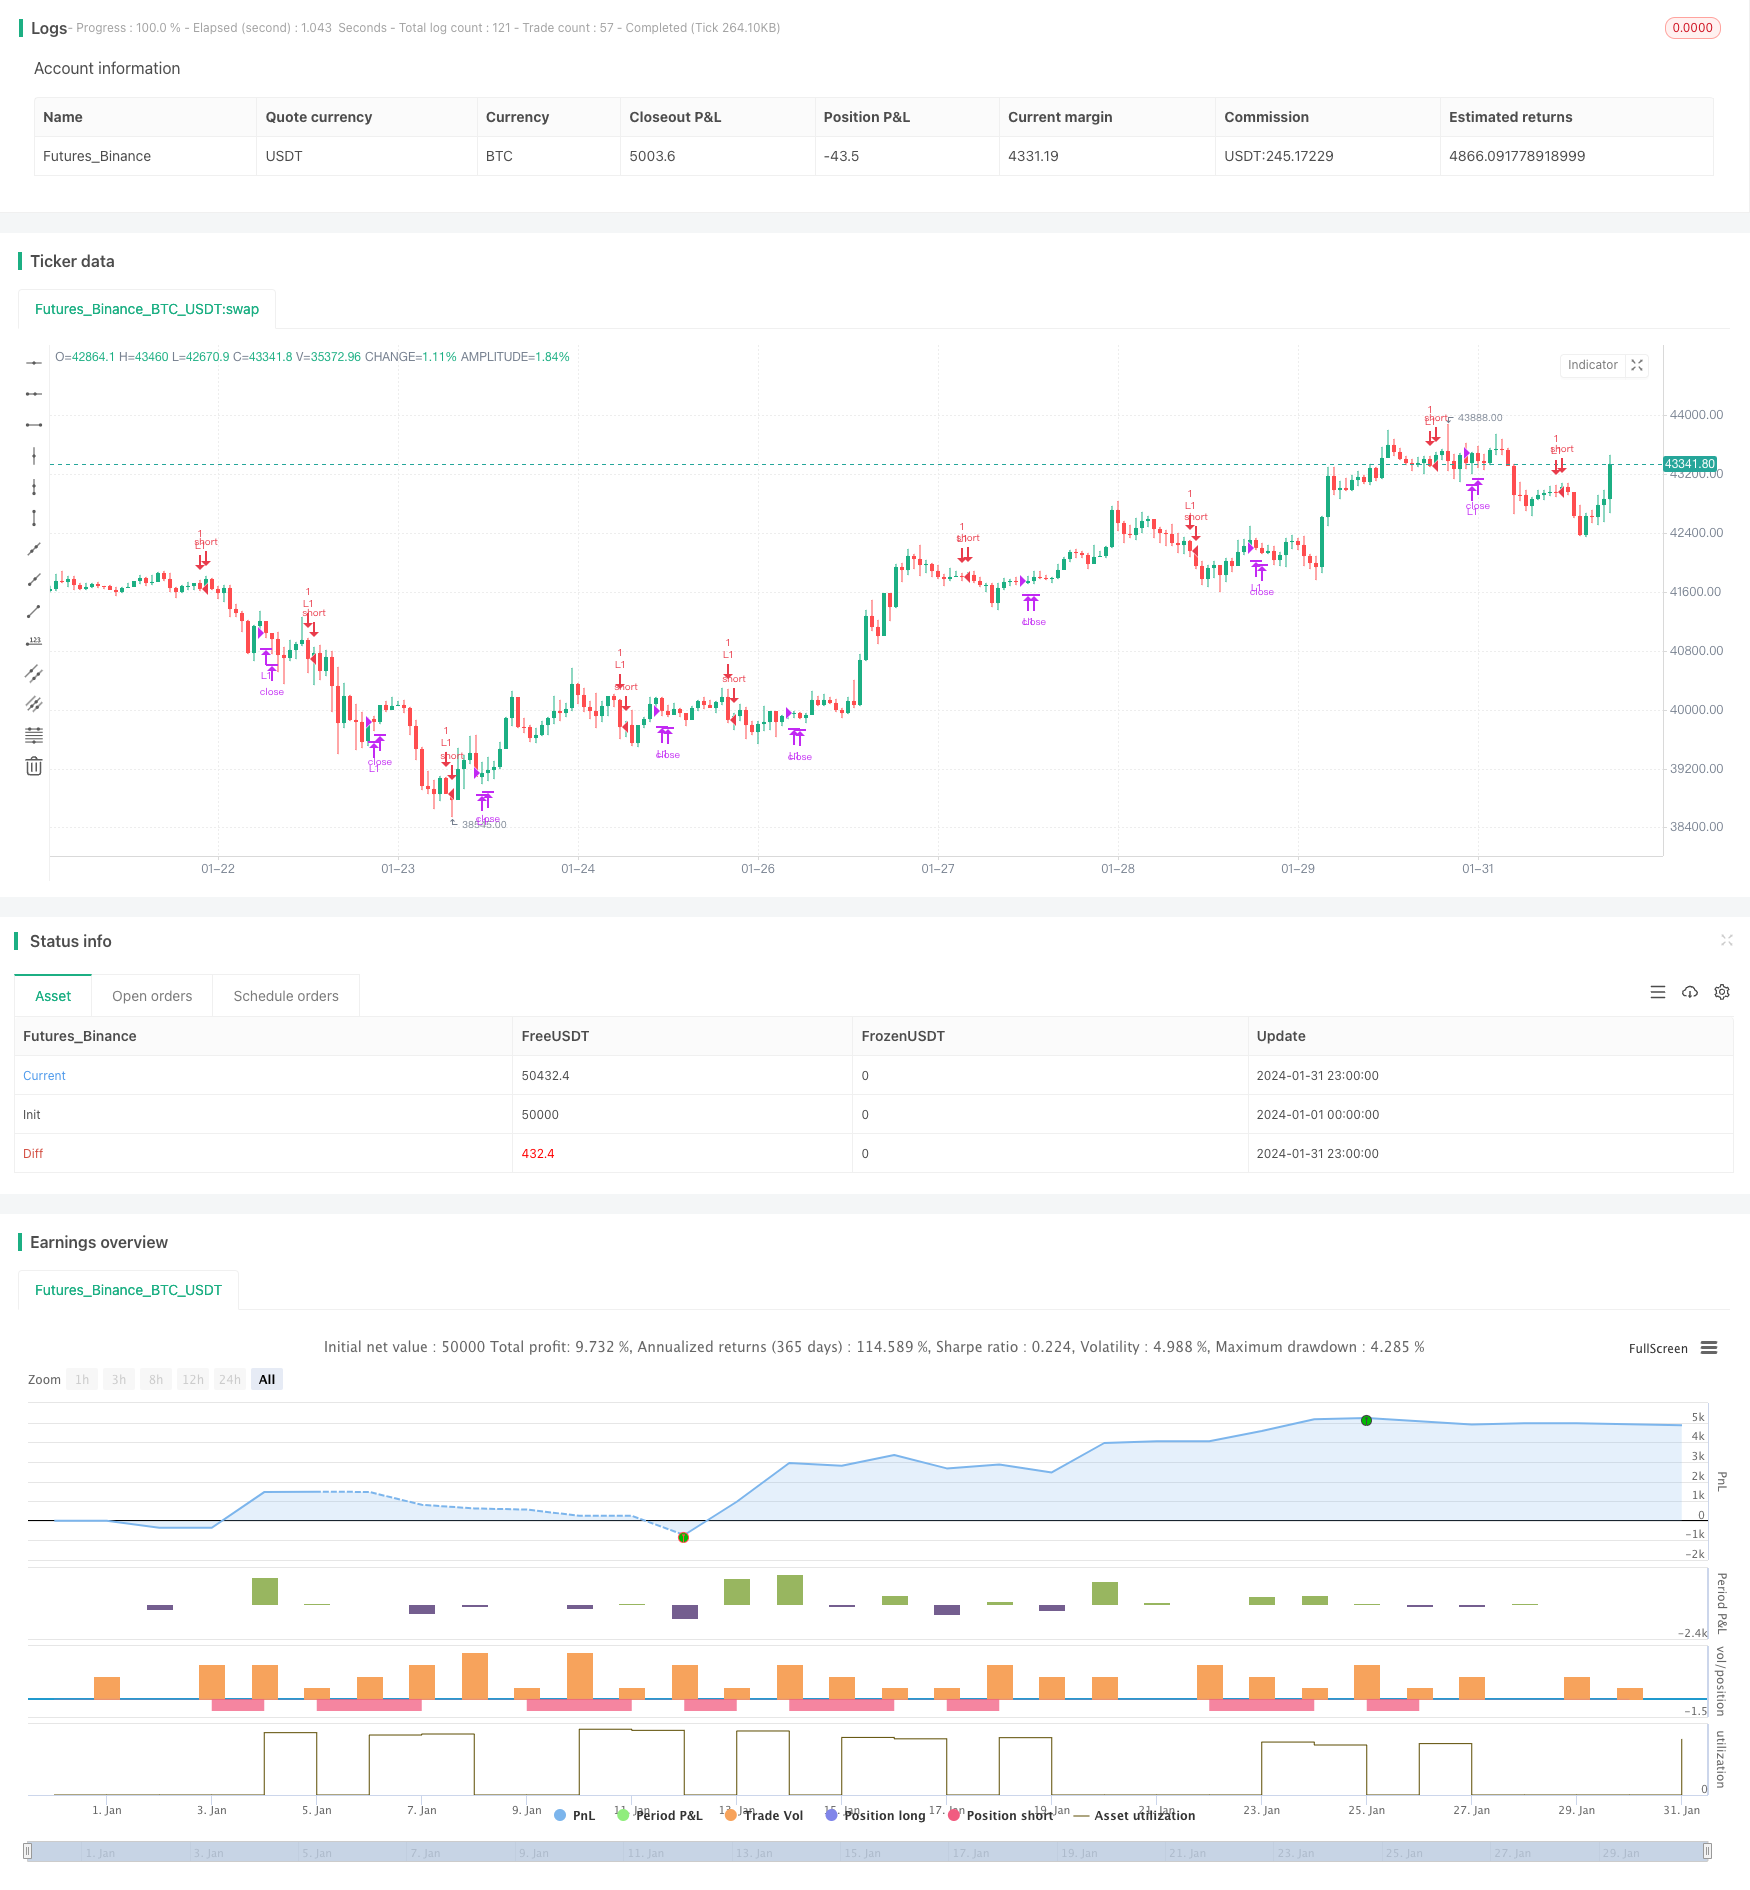
Overview
This strategy utilizes moving averages (MA) and EMA across different timeframes to identify and trade trends. By combining SMA, EMA of various periods, as well as candlestick bodies, it can effectively filter market noise and trade intermediate to long term trends with low risk.
Strategy Logic
The core idea is based on comparison of 3 SMAs of different periods to determine price momentum. Additionally, EMA is used to check if candle body is pointing up.
Specifically, the strategy employs 3 SMAs - 3-, 8-, and 10-period SMA. When price is below all 3 SMAs, it is considered a downtrend. Long signal triggers when price crosses back above the SMAs.
Also, a 5-period EMA checks if the candle body is pointing up before entering long trades.
For exit rules, maximum number of profitable closes or maximum duration is used as stop loss mechanism.
Advantage Analysis
By combining MAs of various timeframes, this strategy can effectively filter market noise and capture intermediate to long term trends. Optimized parameters allow decent performance in historical backtests.
Using EMA to check candle body direction reduces unnecessary slippage from buying into falling candles.
Overall this is a stable and reliable system suitable for trend following over weeks to months.
Risks and Mitigations
The strategy is sensitive to parameters. Suboptimal choice of 3 SMA or 1 EMA periods can deteriorate signal quality. Parameters need to be optimized for different instruments.
Gap risk is not handled. Sudden fundamental news that gap prices could cause losses. Price stop loss can help mitigate such risks.
Enhancement Opportunities
More timeframes of MAs or EMAs can be added to further improve trend accuracy.
Moderate price stop loss can be tested to lock in profits while reducing losses in extreme moves.
Machine learning can dynamically optimize parameters to adapt to evolving market conditions.
Conclusion
The strategy is robust and reliable overall, using MA crossovers to determine trend supplemented by EMA filter. Further parameter optimization and prudent risk controls can enhance win rate and profitability. Worthy of further research and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Quantity |
| v_input_2 | 3 | SMA Period 01 |
| v_input_3 | 8 | SMA Period 02 |
| v_input_4 | 10 | SMA Period 03 |
| v_input_5 | 5 | EMA Period 01 |
| v_input_6 | 5 | Max Profit Close |
| v_input_7 | 10 | Max Total Bars |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Free Strategy #02 (ES / SPY)", overlay=true)

// Inputs
Quantity = input(1, minval=1, title="Quantity")
SmaPeriod01 = input(3, minval=1, title="SMA Period 01")
SmaPeriod02 = input(8, minval=1, title="SMA Period 02")
SmaPeriod03 = input(10, minval=1, title="SMA Period 03")
EmaPeriod01 = input(5, minval=1, title="EMA Period 01")
MaxProfitCloses = input(5, minval=1, title="Max Profit Close")
MaxBars = input(10, minval=1, title="Max Total Bars")

// Misc Variables
src = close
BarsSinceEntry = 0
MaxProfitCount = 0
Sma01 = sma(close, SmaPeriod01)
Sma02 = sma(close, SmaPeriod02)
Sma03 = sma(close, SmaPeriod03)
Ema01 = ema(close, EmaPeriod01)

// Conditions
Cond00 = strategy.position_size == 0
Cond01 = close < Sma03
Cond02 = close <= Sma01
Cond03 = close[1] > Sma01[1]
Cond04 = open > Ema01
Cond05 = Sma02 < Sma02[1]

// Update Exit Variables
BarsSinceEntry := Cond00 ? 0 : nz(BarsSinceEntry[1]) + 1
MaxProfitCount := Cond00 ? 0 : (close > strategy.position_avg_price and BarsSinceEntry > 1) ? nz(MaxProfitCount[1]) + 1 : nz(MaxProfitCount[1])

// Entries
strategy.entry(id="L1", long=true, qty=Quantity, when=(Cond00 and Cond01 and Cond02 and Cond03 and Cond04 and Cond05))

// Exits
strategy.close("L1", (BarsSinceEntry - 1 >= MaxBars or MaxProfitCount >= MaxProfitCloses))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Multi-Timeframe-Moving-Average-and-EMA-Based-Trend-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d