Strategy vault / Trend following
OCC Strategy R51
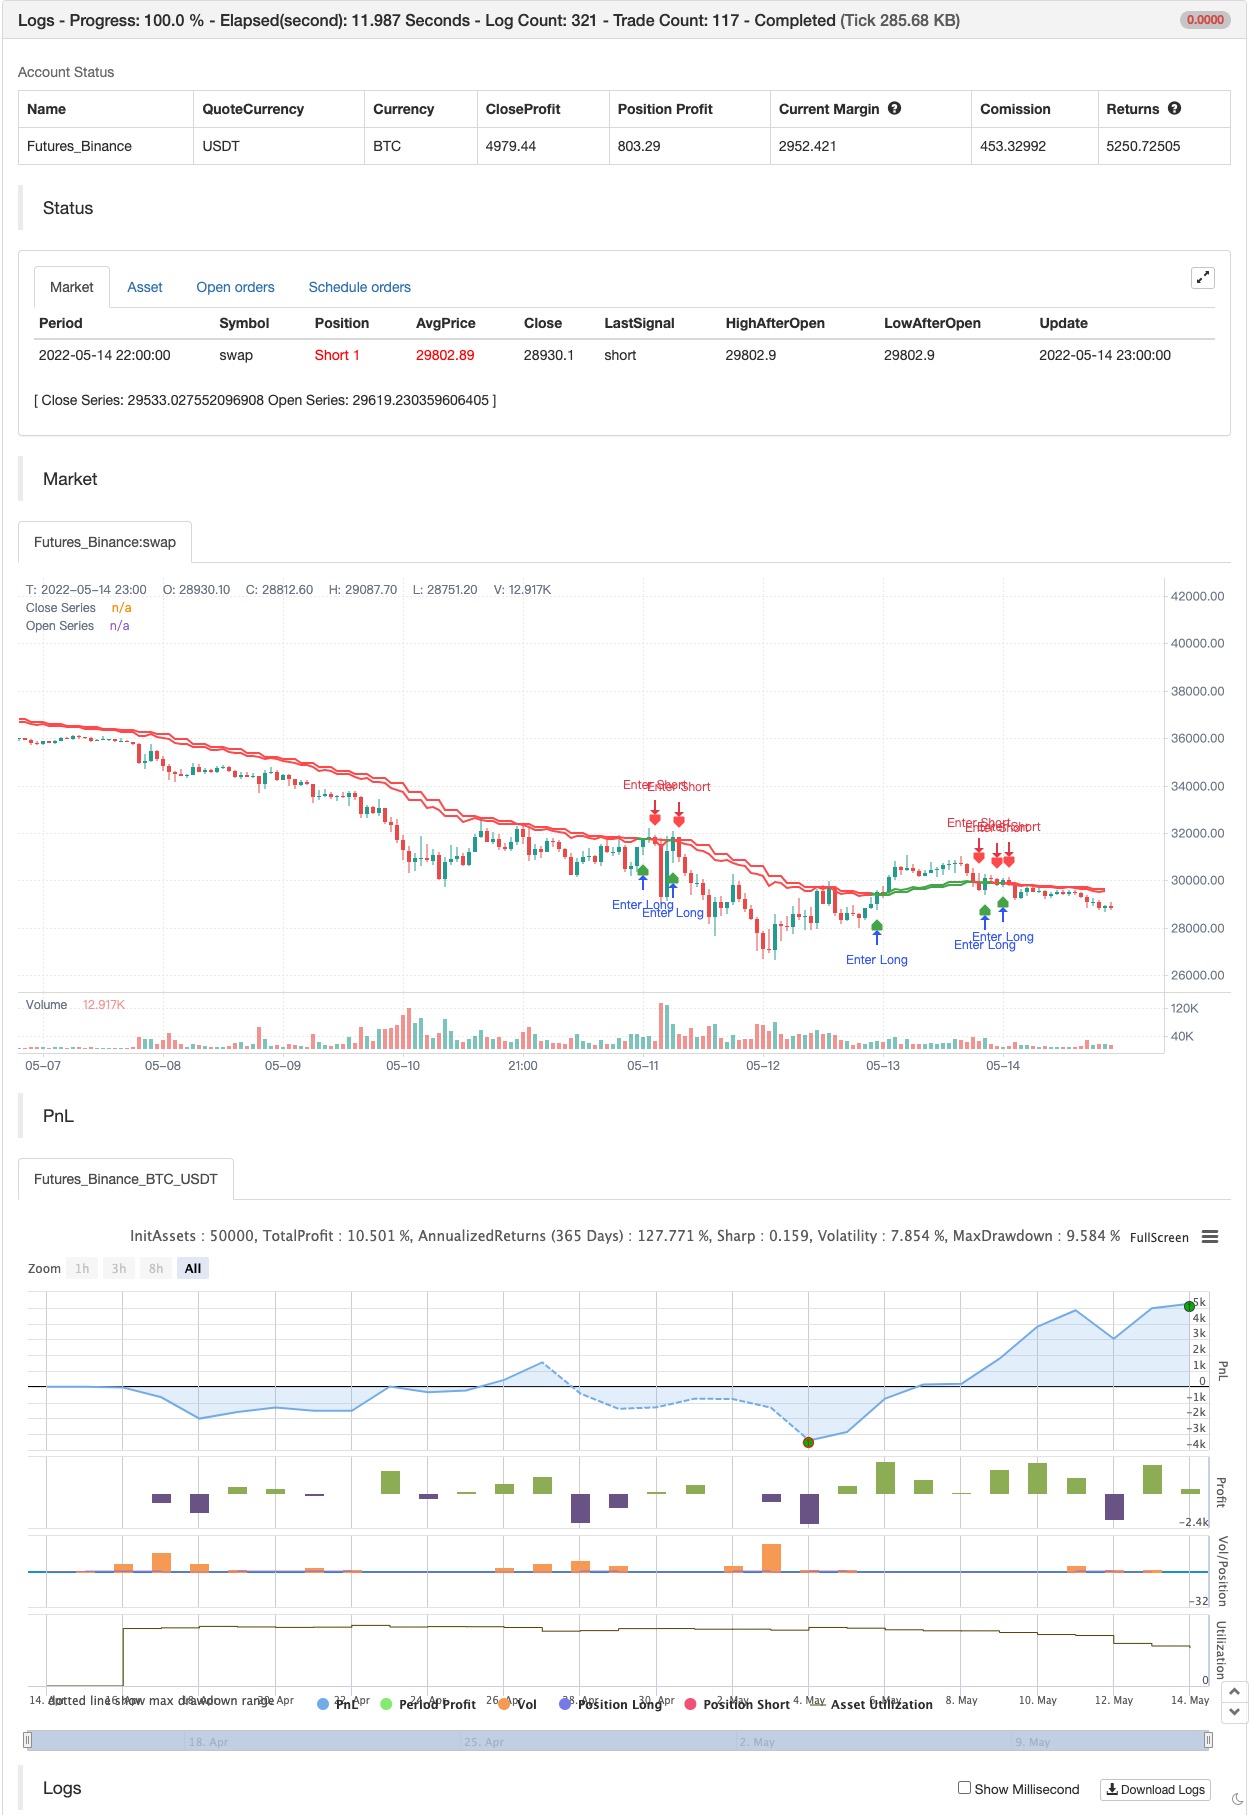
Strategy R5.1 fix It is a modified version of Open Close Cross Strategy R5.1 revised by JustUncleL It helps you determine the time of entry and exit of deals backtest
Strategy R5.1 fix It is a modified version of Open Close Cross Strategy R5.1 revised by JustUncleL It helps you determine the time of entry and exit of deals
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Use Alternate Resolution? |
| v_input_2 | 3 | Multiplier for Alernate Resolution |
| v_input_string_1 | 0 | MA Type: : SMMA | EMA | DEMA | TEMA | WMA | VWMA | SMA | HullMA | LSMA | ALMA | SSMA | TMA |
| v_input_int_1 | 8 | MA Period |
| v_input_int_2 | 6 | Offset for LSMA / Sigma for ALMA |
| v_input_float_1 | 0.85 | Offset for ALMA |
| v_input_3 | false | Show coloured Bars to indicate Trend? |
| v_input_int_3 | false | Delay Open/Close MA (Forces Non-Repainting) |
| v_input_string_2 | 0 | What trades should be taken : : BOTH | SHORT | LONG | NONE |
| v_input_int_4 | false | Initial Stop Loss Points (zero to disable) |
| v_input_int_5 | false | Initial Target Profit Points (zero for disable) |
| v_input_int_6 | 10000 | Number of Bars for Back Testing |
| v_input_4 | false | - SET to ZERO for Daily or Longer Timeframes |
Source Pine Script
/*backtest
start: 2022-04-15 00:00:00
end: 2022-05-14 23:59:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
//

indicator(title='Strategy R5.1 fix', shorttitle='OCC Strategy R5.1', overlay=true)


// === INPUTS ===
useRes = input(defval=true, title='Use Alternate Resolution?')
intRes = input(defval=3, title='Multiplier for Alernate Resolution')
stratRes = timeframe.ismonthly ? str.tostring(timeframe.multiplier * intRes, '###M') : timeframe.isweekly ? str.tostring(timeframe.multiplier * intRes, '###W') : timeframe.isdaily ? str.tostring(timeframe.multiplier * intRes, '###D') : timeframe.isintraday ? str.tostring(timeframe.multiplier * intRes, '####') : '60'
basisType = input.string(defval='SMMA', title='MA Type: ', options=['SMA', 'EMA', 'DEMA', 'TEMA', 'WMA', 'VWMA', 'SMMA', 'HullMA', 'LSMA', 'ALMA', 'SSMA', 'TMA'])
basisLen = input.int(defval=8, title='MA Period', minval=1)
offsetSigma = input.int(defval=6, title='Offset for LSMA / Sigma for ALMA', minval=0)
offsetALMA = input.float(defval=0.85, title='Offset for ALMA', minval=0, step=0.01)
scolor = input(false, title='Show coloured Bars to indicate Trend?')
delayOffset = input.int(defval=0, title='Delay Open/Close MA (Forces Non-Repainting)', minval=0, step=1)
tradeType = input.string('BOTH', title='What trades should be taken : ', options=['LONG', 'SHORT', 'BOTH', 'NONE'])
// === /INPUTS ===

// Constants colours that include fully non-transparent option.
green100 = #008000FF
lime100 = #00FF00FF
red100 = #FF0000FF
blue100 = #0000FFFF
aqua100 = #00FFFFFF
darkred100 = #8B0000FF
gray100 = #808080FF

// === BASE FUNCTIONS ===
// Returns MA input selection variant, default to SMA if blank or typo.
variant(type, src, len, offSig, offALMA) =>
    v1 = ta.sma(src, len)  // Simple
    v2 = ta.ema(src, len)  // Exponential
    v3 = 2 * v2 - ta.ema(v2, len)  // Double Exponential
    v4 = 3 * (v2 - ta.ema(v2, len)) + ta.ema(ta.ema(v2, len), len)  // Triple Exponential
    v5 = ta.wma(src, len)  // Weighted
    v6 = ta.vwma(src, len)  // Volume Weighted
    v7 = 0.0
    sma_1 = ta.sma(src, len)  // Smoothed
    v7 := na(v7[1]) ? sma_1 : (v7[1] * (len - 1) + src) / len
    v8 = ta.wma(2 * ta.wma(src, len / 2) - ta.wma(src, len), math.round(math.sqrt(len)))  // Hull
    v9 = ta.linreg(src, len, offSig)  // Least Squares
    v10 = ta.alma(src, len, offALMA, offSig)  // Arnaud Legoux
    v11 = ta.sma(v1, len)  // Triangular (extreme smooth)
    // SuperSmoother filter
    // © 2013  John F. Ehlers
    a1 = math.exp(-1.414 * 3.14159 / len)
    b1 = 2 * a1 * math.cos(1.414 * 3.14159 / len)
    c2 = b1
    c3 = -a1 * a1
    c1 = 1 - c2 - c3
    v12 = 0.0
    v12 := c1 * (src + nz(src[1])) / 2 + c2 * nz(v12[1]) + c3 * nz(v12[2])
    type == 'EMA' ? v2 : type == 'DEMA' ? v3 : type == 'TEMA' ? v4 : type == 'WMA' ? v5 : type == 'VWMA' ? v6 : type == 'SMMA' ? v7 : type == 'HullMA' ? v8 : type == 'LSMA' ? v9 : type == 'ALMA' ? v10 : type == 'TMA' ? v11 : type == 'SSMA' ? v12 : v1

// security wrapper for repeat calls
reso(exp, use, res) =>
    security_1 = request.security(syminfo.tickerid, res, exp, gaps=barmerge.gaps_off, lookahead=barmerge.lookahead_on)
    use ? security_1 : exp

// === /BASE FUNCTIONS ===

// === SERIES SETUP ===
closeSeries = variant(basisType, close[delayOffset], basisLen, offsetSigma, offsetALMA)
openSeries = variant(basisType, open[delayOffset], basisLen, offsetSigma, offsetALMA)
// === /SERIES ===

// === PLOTTING ===

// Get Alternate resolution Series if selected.
closeSeriesAlt = reso(closeSeries, useRes, stratRes)
openSeriesAlt = reso(openSeries, useRes, stratRes)
//
trendColour = closeSeriesAlt > openSeriesAlt ? color.green : color.red
bcolour = closeSeries > openSeriesAlt ? lime100 : red100
//barcolor(scolor ? bcolour : na, title='Bar Colours')
closeP = plot(closeSeriesAlt, title='Close Series', color=trendColour, linewidth=2, style=plot.style_line, transp=20)
openP = plot(openSeriesAlt, title='Open Series', color=trendColour, linewidth=2, style=plot.style_line, transp=20)
fill(closeP, openP, color=trendColour, transp=80)

// === /PLOTTING ===
//

//
// === ALERT conditions
xlong = ta.crossover(closeSeriesAlt, openSeriesAlt)
xshort = ta.crossunder(closeSeriesAlt, openSeriesAlt)
longCond = xlong  // alternative: longCond[1]? false : (xlong or xlong[1]) and close>closeSeriesAlt and close>=open
shortCond = xshort  // alternative: shortCond[1]? false : (xshort or xshort[1]) and close<closeSeriesAlt and close<=open
// === /ALERT conditions.

// === STRATEGY ===
// stop loss
slPoints = input.int(defval=0, title='Initial Stop Loss Points (zero to disable)', minval=0)
tpPoints = input.int(defval=0, title='Initial Target Profit Points (zero for disable)', minval=0)
// Include bar limiting algorithm
ebar = input.int(defval=10000, title='Number of Bars for Back Testing', minval=0)
dummy = input(false, title='- SET to ZERO for Daily or Longer Timeframes')
//
// Calculate how many mars since last bar
tdays = (timenow - time) / 60000.0  // number of minutes since last bar
tdays := timeframe.ismonthly ? tdays / 1440.0 / 5.0 / 4.3 / timeframe.multiplier : timeframe.isweekly ? tdays / 1440.0 / 5.0 / timeframe.multiplier : timeframe.isdaily ? tdays / 1440.0 / timeframe.multiplier : tdays / timeframe.multiplier  // number of bars since last bar
//
//set up exit parameters
TP = tpPoints > 0 ? tpPoints : na
SL = slPoints > 0 ? slPoints : na


state_occ= "none"

if ((ebar==0 or tdays<=ebar) and tradeType!="NONE")

    if longCond==true and tradeType!="SHORT"
        state_occ:= "Long"

    if shortCond==true and tradeType=="LONG"
        state_occ:= "Long"

    if shortCond==true and tradeType!="LONG"
        state_occ:= "Short"

    if longCond==true and tradeType=="SHORT"
        state_occ:= "Short"

// === /STRATEGY ===
// eof

plotshape(state_occ=="Long", text='LONG', style=shape.labelup, location=location.belowbar, color=color.new(color.green, 0), textcolor=color.new(color.white, 0), offset=0, title='OCC LONG', size=size.normal)
plotshape(state_occ=="Short", text='LONG', style=shape.labeldown, location=location.abovebar, color=color.new(color.red, 0), textcolor=color.new(color.white, 0), offset=0, title='OCC SHORT', size=size.normal)


alertcondition(state_occ=="Long", title='LONG', message='LONG')
alertcondition(state_occ=="Short", title='SHORT', message='SHORT')


//alertcondition((ebar==0 or tdays<=ebar) and tradeType!="NONE" and TP, title='EXIT LONG', message='EXIT LONG')
//alertcondition((ebar==0 or tdays<=ebar) and tradeType!="NONE" and SL, title='EXIT SHORT', message='STOP LOSS')

if state_occ=="Long"
    strategy.entry("Enter Long", strategy.long)
else if state_occ=="Short"
strategy.entry("Enter Short", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/OCC-Strategy-R51.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d