Pivot Based Volume Weighted Breakout Reversal Strategy
This strategy combines support/resistance (S/R) breakout/reversal, volume filtering, and alert systems to capture key market turning points. It identifies price breakout/reversal signals validated by abnormal volume…
Overview
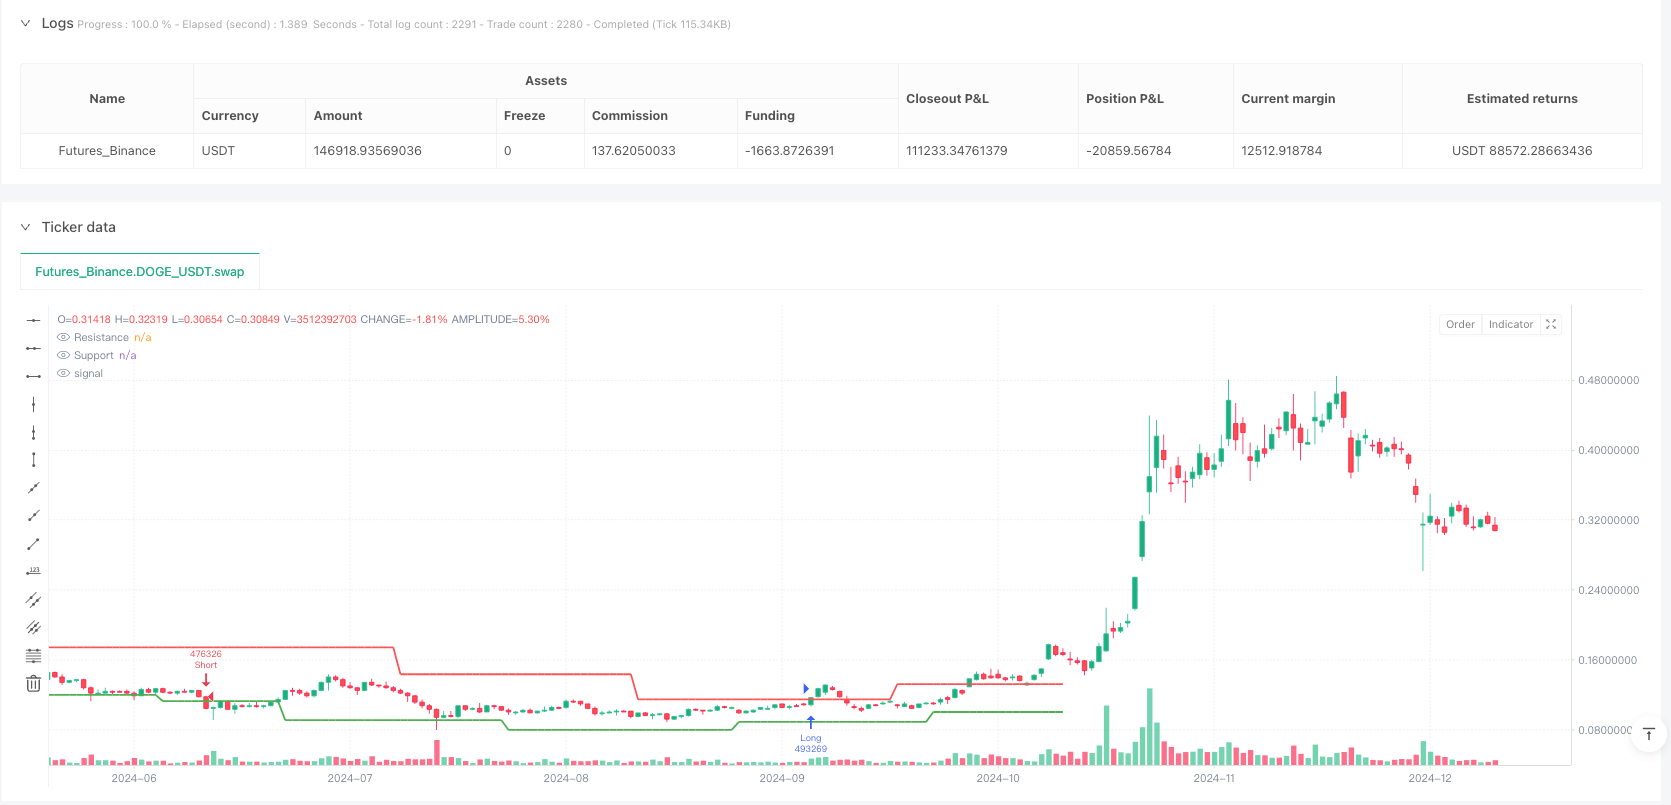
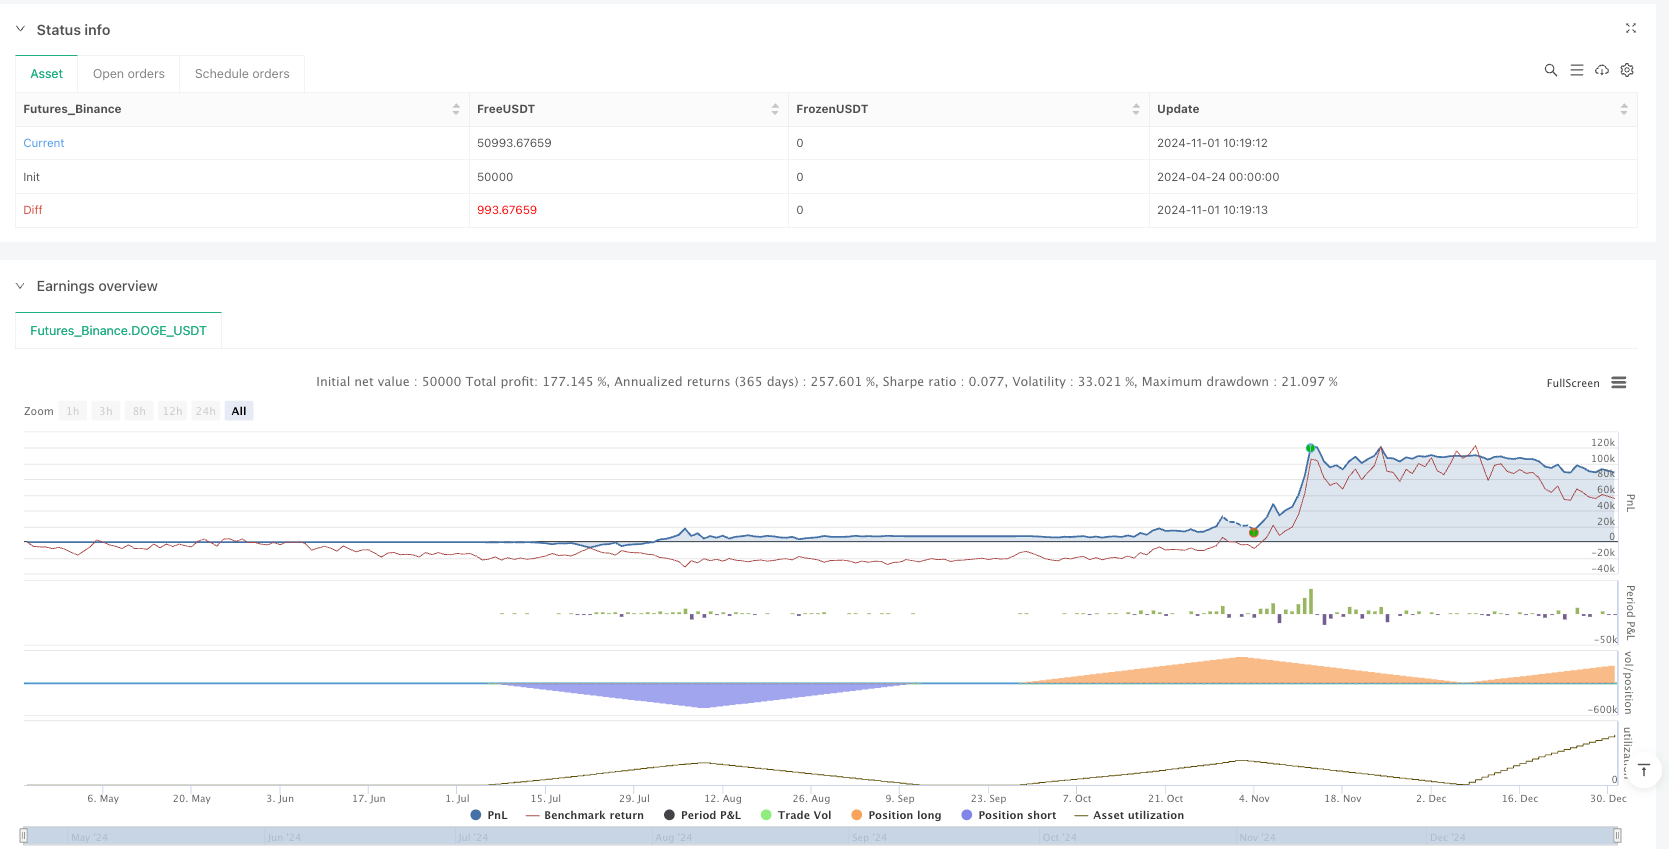
This strategy combines support/resistance (S/R) breakout/reversal, volume filtering, and alert systems to capture key market turning points. It identifies price breakout/reversal signals validated by abnormal volume activity to improve reliability. The strategy employs a fixed 2% stop loss and adjustable take profit (default 3%) for risk management.
Strategy Logic
- S/R Identification: Uses
ta.pivothigh()andta.pivotlow()to detect key price levels within a specified period (pivotLen). Signals trigger when price breaks resistance (upward >1%) or bounces from support (false breakdown recovery). - Volume Filter: Calculates volume SMA (volSmaLength periods). A valid signal requires current volume exceeding SMA by volMultiplier (default 1.5x).
- Long/Short Logic:
- Long Condition: Price breaks resistance (close > resZone*1.01) with high volume, or shows false breakdown near support (±1% range) with volume confirmation.
- Short Condition: Price breaks support (close < supZone*0.99) with high volume, or shows false breakout near resistance (±1% range) with volume confirmation.
- Risk Management: Fixed 2% stop loss and adjustable take profit (default 3%) via
strategy.exit().
Advantages
- Multi-Factor Validation: Combines price structure (S/R), volume, and market behavior (false breaks), significantly reducing false signals.
- Dynamic Adaptation: Auto-updates S/R levels to adapt to market changes.
- Strict Risk Control: Fixed stop loss prevents excessive losses; adjustable take profit suits varying market conditions.
- High Visibility: Real-time S/R plotting and clear signal labels.
- Alert Integration: Compatible with automated trading systems.
Risks
- Range-Bound Risk: Frequent false breakouts in choppy markets. Solution: Add trend filters like ADX or EMA.
- Parameter Sensitivity: pivotLen and volMultiplier require market-specific tuning. Solution: Parameter optimization and Walk-Forward testing.
- Volume Lag: Abnormal volume may follow price moves. Solution: Incorporate order book data or reduce volSmaLength.
- Gap Risk: Opening gaps may skip stop levels. Solution: Use limit orders or avoid high-volatility sessions.
Optimization Directions
- Trend Filtering: Add ADX>25 or 200EMA direction filters to avoid counter-trend trades.
- Dynamic Parameters: Auto-adjust pivotLen and volMultiplier based on volatility (e.g., ATR).
- Scaled Take Profit: Implement two-tier exits (e.g., close 50% at 2%, trail remainder).
- Machine Learning: Train models to optimize volMultiplier and tpPerc historically.
- Multi-Timeframe Confirmation: Validate signals with higher timeframe S/R levels.
Conclusion
This strategy establishes a high-probability framework through triple validation (price position, volume, price action), ideal for capturing early trend phases. Its transparency and controlled risk are key strengths, though range-bound performance requires caution. Future enhancements should focus on parameter self-adaptation and trend filtering for greater robustness.
Source Pine Script
/*backtest
start: 2024-04-24 00:00:00
end: 2024-12-31 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"DOGE_USDT"}]
*/

//@version=5
strategy("S/R Breakout/Reversal + Volume + Alerts", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// === INPUTS ===
pivotLen       = input.int(10, "Pivot Lookback for S/R")
volSmaLength   = input.int(20, "Volume SMA Length")
volMultiplier  = input.float(1.5, "Volume Multiplier")
tpPerc         = input.float(3.0, "Take Profit %", step=0.1)
slPerc         = 2.0  // Stop Loss fixed at 2%

// === S/R ZONES ===
pivotHigh = ta.pivothigh(high, pivotLen, pivotLen)
pivotLow  = ta.pivotlow(low, pivotLen, pivotLen)

var float resZone = na
var float supZone = na
if not na(pivotHigh)
    resZone := pivotHigh
if not na(pivotLow)
    supZone := pivotLow

plot(supZone, title="Support", color=color.green, linewidth=2, style=plot.style_linebr)
plot(resZone, title="Resistance", color=color.red,   linewidth=2, style=plot.style_linebr)

// === VOLUME FILTER ===
volSma     = ta.sma(volume, volSmaLength)
highVolume = volume > volSma * volMultiplier

// === LONG LOGIC ===
priceAboveRes     = close > resZone * 1.01
nearSupport       = close >= supZone * 0.99 and close <= supZone * 1.01
rejectSupport     = low <= supZone and close > supZone
longBreakoutCond  = priceAboveRes and highVolume
longReversalCond  = nearSupport and rejectSupport and highVolume
longCondition     = longBreakoutCond or longReversalCond

// === SHORT LOGIC ===
priceBelowSup     = close < supZone * 0.99
nearResistance    = close >= resZone * 0.99 and close <= resZone * 1.01
rejectResistance  = high >= resZone and close < resZone
shortBreakoutCond = priceBelowSup and highVolume
shortReversalCond = nearResistance and rejectResistance and highVolume
shortCondition    = shortBreakoutCond or shortReversalCond

// === ENTRIES WITH LABELS ===
if (longCondition)
    strategy.entry("Long", strategy.long)
    label.new(bar_index, low * 0.995, "BUY", style=label.style_label_up, color=color.green, textcolor=color.white)

if (shortCondition)
    strategy.entry("Short", strategy.short)
    label.new(bar_index, high * 1.005, "SELL", style=label.style_label_down, color=color.red, textcolor=color.white)

// === TP/SL ===
longTP  = close * (1 + tpPerc / 100)
longSL  = close * (1 - slPerc / 100)
shortTP = close * (1 - tpPerc / 100)
shortSL = close * (1 + slPerc / 100)

strategy.exit("Long TP/SL",  from_entry="Long",  limit=longTP,  stop=longSL)
strategy.exit("Short TP/SL", from_entry="Short", limit=shortTP, stop=shortSL)

// === ALERT CONDITIONS ===
alertcondition(longCondition,  title="Buy Alert",  message="? BUY signal: S/R + Volume breakout/reversal")
alertcondition(shortCondition, title="Sell Alert", message="? SELL signal: S/R + Volume breakout/reversal")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-04-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Pivot-Based-Volume-Weighted-Breakout-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Trend Following and Volatility Breakout StrategyPine Script · Breakout · 2h
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Quantitative Trading Strategy Based on Ichimoku with Multiple SignalsPine Script · Breakout · 1h
- Multi Technical Indicator Trend Following Channel Breakout Trading Strategy with Candlestick Pattern Filtering SystemPine Script · Breakout · 1h