Strategy vault / Trend following
Pivot Trend
Hello Traders, Another original idea is here with you. Actualy I can say that it's a breakout strategy that uses multiple Pivot Point's averages. How it works? - it finds the Pivot Points , you can set the length as…
Hello Traders,
Another original idea is here with you. Actualy I can say that it's a breakout strategy that uses multiple Pivot Point's averages.
How it works?
- it finds the Pivot Points , you can set the length as you want
- it gets averages of Pivot Highs and Pivot Lows, you can set the number of Pivot Points to be included
- it compares the current closing price with averages of Pivot Highs and Pivot Lows
- if both are positive or negative then trend changes
You have two options:
- Pivot Point Period => is the length that is used to find Pivot Points . means it checks left/right bars if it's Pivot Point (4 by default)
- Number of PP to check => is the number of Pivot Points that the script finds and calculates the averages (3 by default)
backtest
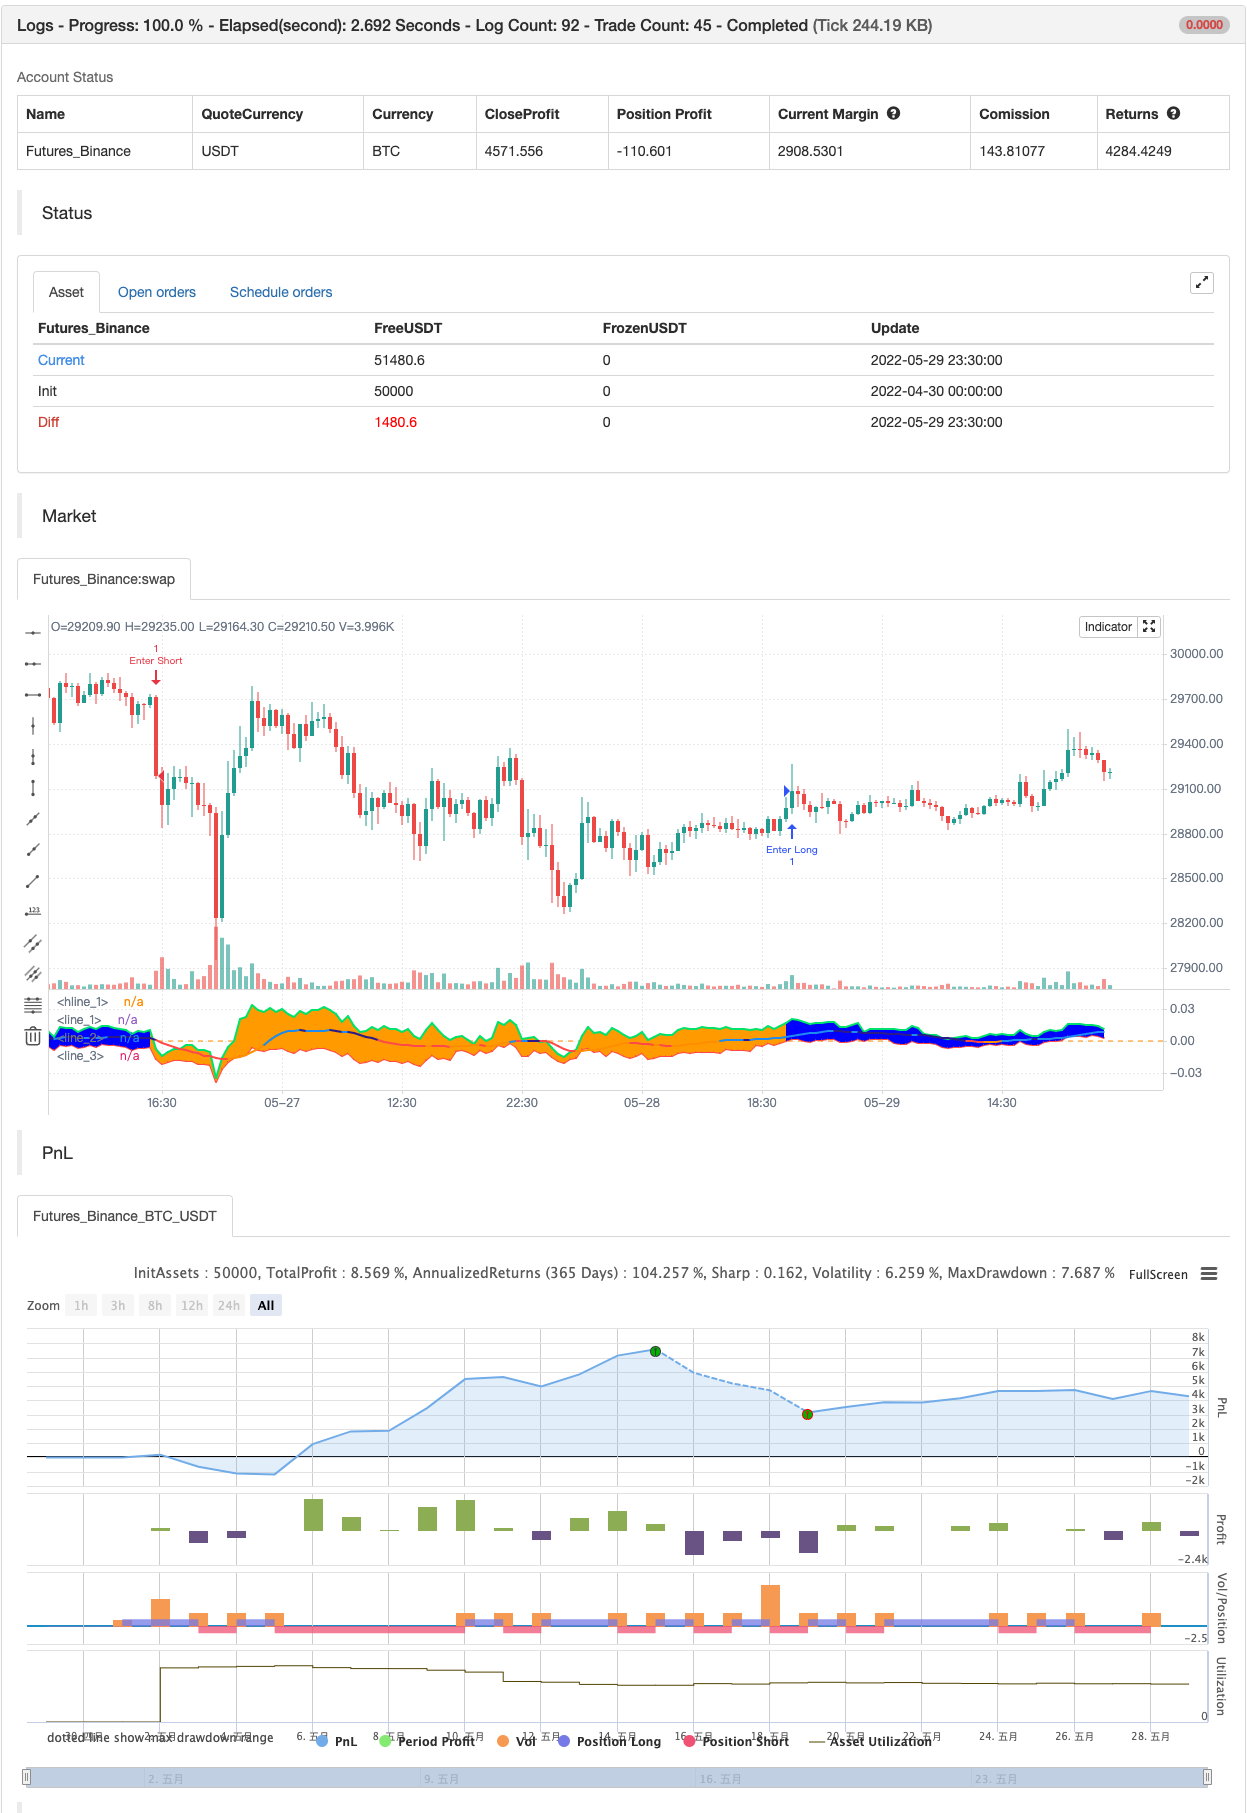
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 4 | Pivot Point Period |
| v_input_2 | 3 | number of PP to check |
| v_input_3 | blue | Colors |
| v_input_4 | orange | coldn |
Source Pine Script
/*backtest
start: 2022-04-30 00:00:00
end: 2022-05-29 23:59:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © LonesomeTheBlue

//@version=4
study("Pivot Trend", precision = 2, explicit_plot_zorder = true)
prd = input(defval = 4, title="Pivot Point Period", minval = 1, maxval = 30)
pnum = input(defval = 3, title="number of PP to check", minval = 1, maxval = 30)
colup = input(defval = color.blue, title = "Colors", inline = "col")
coldn = input(defval = color.orange, title = "", inline = "col")

float ph = pivothigh(prd, prd)
float pl = pivotlow(prd, prd)
var ph_lev = array.new_float(pnum, na)
var pl_lev = array.new_float(pnum, na)

if ph
    array.unshift(ph_lev, ph)
    array.pop(ph_lev)

if pl
    array.unshift(pl_lev, pl)
    array.pop(pl_lev)

float lrate = 0.0
for i = 0 to array.size(pl_lev) - 1
    float rate = (close - array.get(pl_lev, i)) / array.get(pl_lev, i)
    lrate += (rate / pnum)


float hrate = 0.0
for i = 1 to array.size(ph_lev) - 1
    float rate = (close - array.get(ph_lev, i)) / array.get(ph_lev, i)
    hrate += (rate / pnum)

hline(0.)
hln = plot(hrate, color = color.red, linewidth = 2)
lln = plot(lrate, color = color.lime, linewidth = 2)

trend = 0
trend := hrate > 0 and lrate > 0 ? 1 : hrate < 0 and lrate < 0 ? -1 : nz(trend[1])
tcolor = trend == 1 ? color.new(colup, 40) : color.new(coldn, 40)
fill(hln, lln, color = tcolor)

mid = sma((hrate + lrate) / 2, 9)
plot(mid, color = mid >= 0 ? mid >= mid[1] ? color.blue : color.navy : mid <= mid[1] ? color.red : color.orange, linewidth = 2)

alertcondition(change(trend) > 0, title='Pivot Trend UP', message='Pivot Trend UP')
alertcondition(change(trend) < 0, title='Pivot Trend DOWN', message='Pivot Trend DOWN')

if change(trend) > 0
    strategy.entry("Enter Long", strategy.long)
else if change(trend) < 0
strategy.entry("Enter Short", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Pivot-Trend.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands Precise Crossover Quantitative StrategyPine Script · Trend following · 1h
- Comprehensive Trading System Combining SMA Crossover Strategy with Fair Value Gap PullbackPine Script · Trend following · 1d
- Dual Moving Average Trend Following System with Adaptive Dynamic Filtering StrategyPine Script · Trend following · 30m
- EMA AROON ASHPine Script · Trend following · 3m
- EMA SMA Trend Following with Swing Trading Strategy Combined Volume Filter and Percentage Take Profit Stop Loss SystemPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h