Strategy vault / Trend following
Previous Days Close with ATR Trend Tracking Strategy
This strategy sets long and short entry price levels and stop loss price levels based on previous day's close price and ATR indicator to track the trend. It goes long or short when price breaks through the entry…
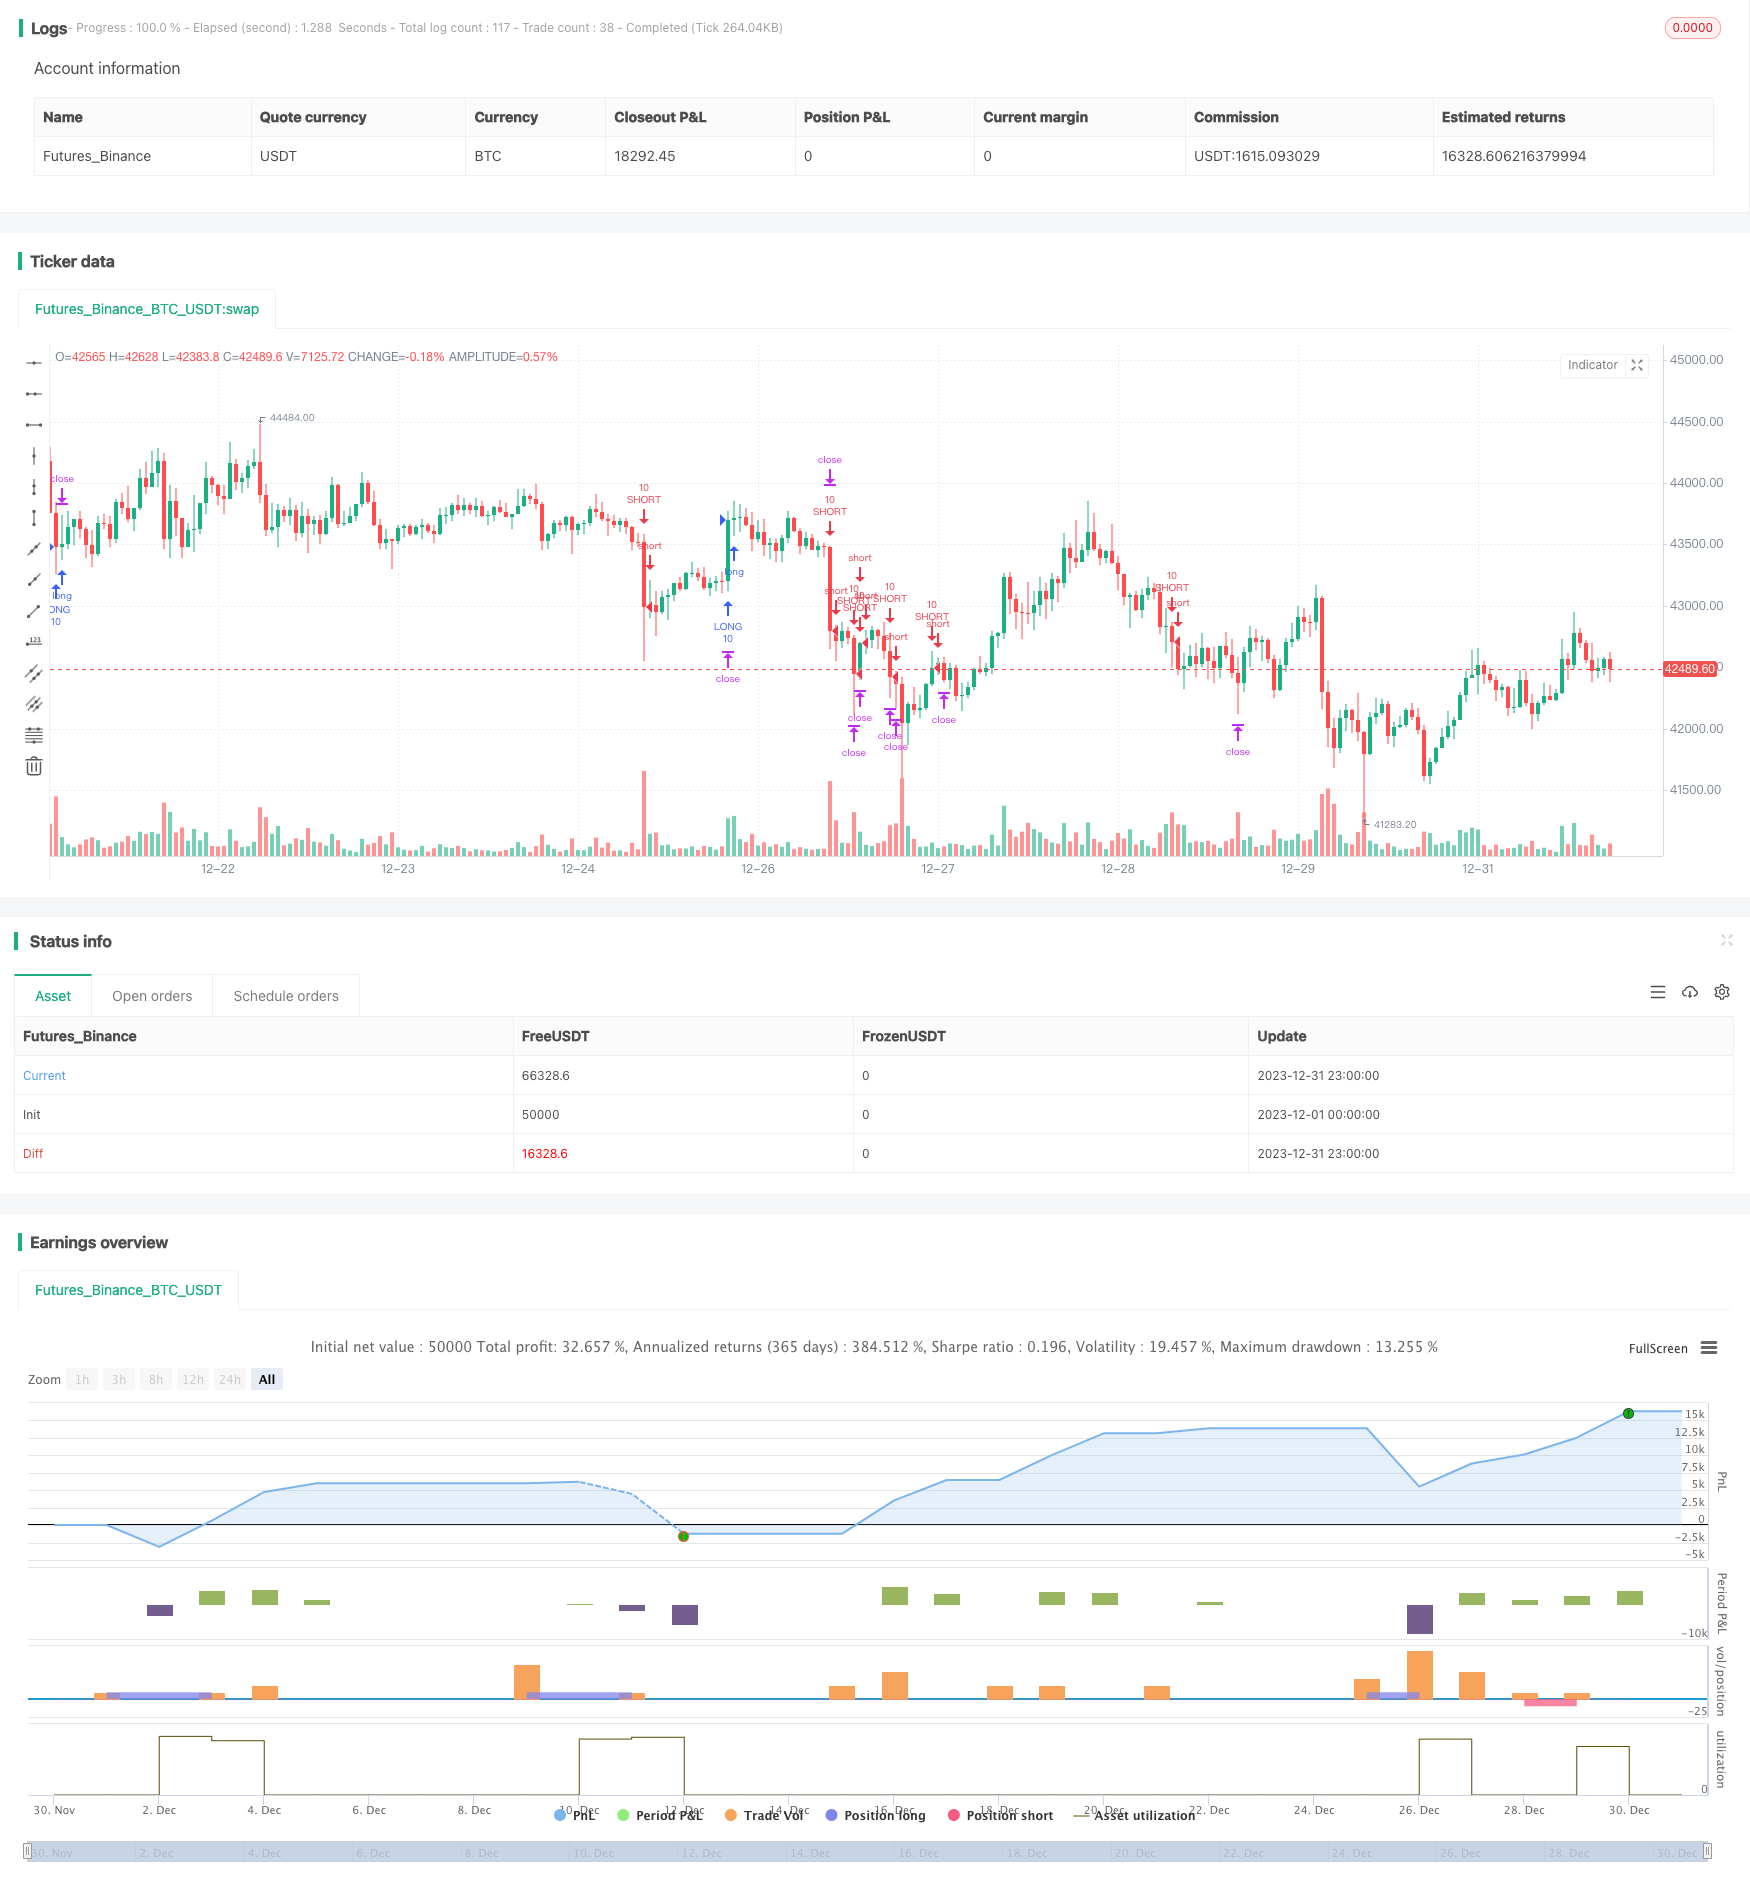
Overview
This strategy sets long and short entry price levels and stop loss price levels based on previous day's close price and ATR indicator to track the trend. It goes long or short when price breaks through the entry price levels, and flattens positions on stop loss or take profit.
Strategy Logic
This strategy uses previous day's close price, high price, low price and ATR indicator to calculate entry price levels and stop loss levels. The specific formulas are as follows:
Long entry price level TPup = Previous day's close + ATR * 0.8
Short entry price level TPdown = Previous day's close - ATR * 0.8
Long stop loss level slup = Previous day's close + ATR * 0.2
Short stop loss level sldown = Previous day's close - ATR * 0.2
Long take profit level profitlevelup = Previous day's low + ATR * 1.7
Short take profit level profitleveldown = Previous day's high - ATR * 1.7
When price breaks through TPup, go long 10 lots. When price breaks through TPdown, go short 10 lots. Then set stop loss and take profit. Exit positions on stop loss trigger or take profit trigger.
Advantage Analysis
The main advantages of this strategy are:
Using ATR indicator to set dynamic entry price levels and stop loss levels based on market volatility, making trades more adaptive to market conditions.
Using previous day's close to determine direction and combining with ATR indicator to identify specific trade levels, avoiding being misled by too much real-time price noise.
Setting both stop loss and take profit mechanisms to effectively control the risk of each trade.
Risk Analysis
The main risks of this strategy are:
The price levels set by ATR may be too idealistic to truly reflect market conditions, leading to frequent stop loss triggers. Parameters of ATR can be adjusted or stop loss range can be widened.
Previous day's close cannot determine future trends. Drastic reversals may mislead directional choices. Other indicators can be combined to confirm trends.
Stop loss and take profit may be manipulated to trigger, failing to truly stop loss. Batch stop loss can be used to avoid being trapped.
Optimization Directions
This strategy can be optimized in the following aspects:
Optimize ATR parameters to make trade levels fit better with market volatility.
Add trend judging mechanisms to avoid trading reversals, e.g. combining with MA indicators.
Adjust take profit range, keeping profitability while reducing probability of profit taking triggers.
Set batch stop loss and profit taking to reduce probability of being trapped or losing.
Add position sizing mechanism to increase positions in trending phases.
Conclusion
This strategy sets dynamic trade levels based on previous day's close and ATR to effectively track trends. It also uses stop loss and take profit to control single trade risks. Optimization directions include parameter tuning, judging mechanism enhancement, take profit adjustment and position sizing etc. In general, this strategy achieves good trend following effects.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | lookback length of ATR |
| v_input_2 | 0.8 | Entry level for ATR |
| v_input_3 | 1.7 | Exit level for ATR |
| v_input_4 | 0.2 | Stop loss level for ATR |
| v_input_5 | 2014 | Backtest Starting year |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("PC with ATR Strategy (by Zhipengcfel)", shorttitle="PC_ATR", pyramiding=1, overlay=true)

// Zhipengcfel's Previous day's close with ATR Strategy
//
// Version 1.0
// @copyright Idea by Zhipengcfel on June 29, 2017.

//Previous day's close plus ATR strategy.
//Buy (if breaking PC+ATR*0.8) or sell (if breaking PC-0.8*ATR).

//This is just a demo vision and can not be used for real auto trading


///////////// ATR value
ATRlength = input(14, minval=1, title="lookback length of ATR")
//ATR = atr(ATRlength)
ATR = request.security(syminfo.tickerid, 'D', atr(ATRlength))

///////////// Entry levels and target levels
entr = input(0.8, minval=0.1, step = 0.05, title="Entry level for ATR")
tplevel = input(1.7, minval=0.1, step = 0.05, title="Exit level for ATR")
yesterday = request.security(syminfo.tickerid, 'D', close[1])
dl = request.security(syminfo.tickerid, 'D', low[1])
dh = request.security(syminfo.tickerid, 'D', high[1])
TPup = yesterday+entr*ATR
TPdown = yesterday-entr*ATR
profitlevelup = dl+tplevel*ATR
profitleveldown = dh-tplevel*ATR

///////////// Stop loss level
sl = input( 0.2  ,minval=0.01, step = 0.05, title="Stop loss level for ATR") //82 for 2, 83 for 3 and more positions
slup = yesterday+sl*ATR
sldown = yesterday-sl*ATR

///////////// Starting year to backtest
yer = input( 2014  , title="Backtest Starting year")


///////////// strategy: PC + ATR
if (close > TPup) and (close < profitlevelup)
    strategy.entry("LONG", strategy.long, 10, comment="Buy", when = year > yer, oca_name="My oca")
    strategy.exit("Stopped", "LONG",  stop = slup, limit= profitlevelup, oca_name="My oca")


if (close < TPdown) and (close > profitleveldown)
    strategy.entry("SHORT", strategy.short, 10, comment="Sell", when = year > yer, oca_name="My oca")
    strategy.exit("Stopped", "SHORT", stop = sldown, limit= profitleveldown, oca_name="My oca")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Previous-Days-Close-with-ATR-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m
- Adaptive ATR and RSI Trend Following Strategy with Trailing Stop LossPine Script · Trend following · 1h
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h