Strategy vault / Multi-timeframe
Price Channel and MACD Based Multi Timeframe Trading Strategy
This strategy combines price channel indicator and MACD indicator to track trends and identify overbought and oversold levels across multiple timeframes, thereby making buy and sell decisions. The strategy also…
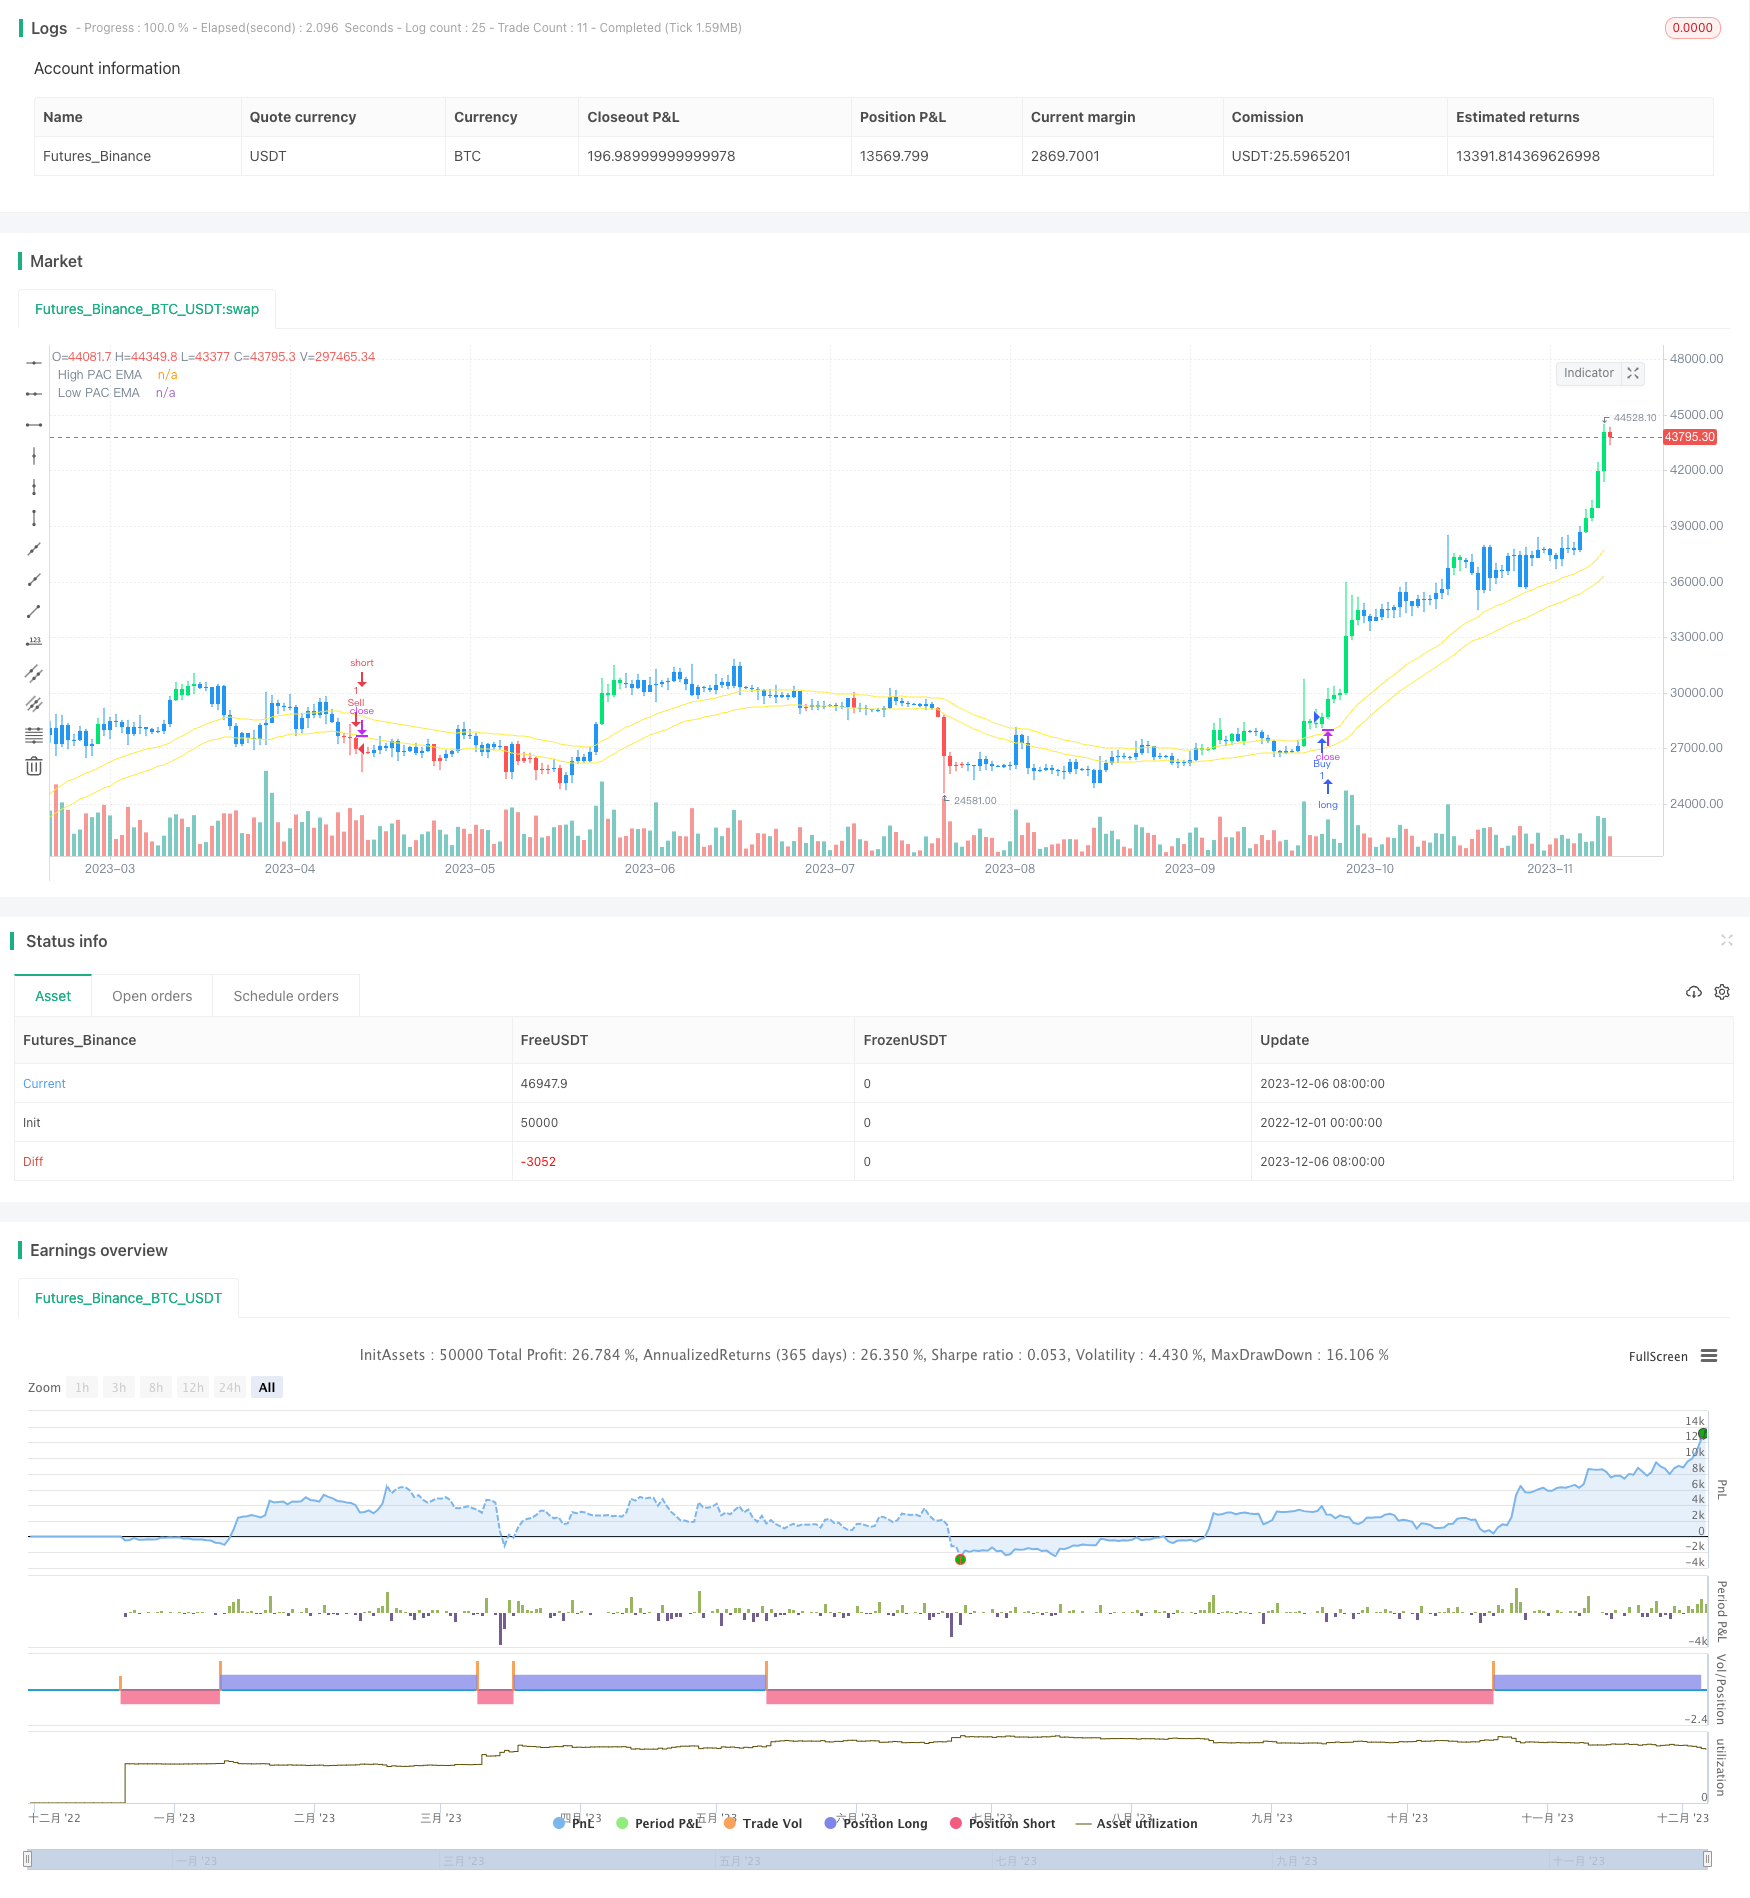
Overview
This strategy combines price channel indicator and MACD indicator to track trends and identify overbought and oversold levels across multiple timeframes, thereby making buy and sell decisions. The strategy also incorporates stop loss and take profit to manage risks.
Strategy Logic
The price channel indicator constructs a price channel based on EMA lines of highest and lowest prices to determine trends when price breaks out of the channel. The MACD indicator judges bullish and bearish momentum. Values above zero line suggest a bull market while values below suggest a bear market.
The trading signals of this strategy come from the following aspects:
Enter long when MACD histogram flips red. Enter short when MACD histogram flips green.
Enter short when price approaches the bottom of the channel and MACD is below zero line.
Enter long when price approaches the top of the channel and MACD is above zero line.
Enter long when MACD crosses above zero line. Enter short when MACD crosses below zero line.
Exits are triggered by stop loss and take profit.
Advantages of the Strategy
Combination of indicators prevents false breakout.
Combination of indicators across timeframes ensures reliable trend detection.
Incorporation of stop loss and take profit effectively controls per trade loss.
Risks of the Strategy
Limited optimization space leading to overoptimization.
Low setting of price channel misses larger moves.
Tight stop loss causes larger losses.
Solutions:
Adopt walk forward optimization to prevent overoptimization.
Set adaptive parameters for price channel.
Introduce volatility based stop loss for dynamic adjustment of stop distance.
Directions of Optimization
Optimize combination of MACD parameters.
Optimize adaptive calculation of price channel parameters.
Add more filters to prevent false breakouts and improve efficiency.
Summary
This strategy combines the strengths of price channel and MACD by reasonable parameter setups and large optimization space. It performs well in trend detection and overbought/oversold identification. The stop loss/take profit mechanism controls per trade loss. Going forwards, improvements can be made by parameters optimization, adding filters and optimizing the stop loss mechanism.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 34 | High Low channel Length |
| v_input_2 | 12 | fastLength |
| v_input_3 | 26 | slowlength |
| v_input_4 | 9 | MACDLength |
| v_input_5 | 34 | PeriodLookBack |
| v_input_6 | 100 | Stop Loss Point |
| v_input_7 | 0.1 | Reward/Risk |
| v_input_8 | false | Use exit order strategy? |
Source Pine Script
/*backtest
start: 2022-12-01 00:00:00
end: 2023-12-07 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("Sonic R + Barcolor MACD", overlay=true)
HiLoLen     = input(34, minval=2,title="High Low channel Length")
pacL        = ema(low,HiLoLen)
pacH        = ema(high,HiLoLen)
// Plot the Price Action Channel (PAC) base on EMA high,low and close//
L=plot(pacL, color=yellow, linewidth=1, title="High PAC EMA",transp=0)
H=plot(pacH, color=yellow, linewidth=1, title="Low PAC EMA",transp=0)
fastLength = input(12)
slowlength = input(26)
MACDLength = input(9)
MACD = ema(close, fastLength) - ema(close, slowlength)
aMACD = ema(MACD, MACDLength)
delta = MACD - aMACD
hisup= iff(delta>delta[1] and delta>0, 1,
	     iff(delta<delta[1], -1, nz(hisup[1], 0)))
hisdown = iff(delta<delta[1] and delta<0, 1,
	     iff(delta>delta[1], -1, nz(hisdown[1], 0)))
barcolor(hisup==1 and MACD>0 ? lime: hisdown==1 and MACD<0 ? red : blue )
//SR
PeriodLookBack = input(34)
xHighest = highest(PeriodLookBack)
xLowest = lowest(PeriodLookBack)
Trend= close>xHighest[1] ? 1: close< xLowest[1]?-1 : nz(Trend[1],0)
// Strategy//
conbuy= hisdown==1 or MACD<0 ? 1: hisup[5]==1 and MACD[5]>0 ?-1 : nz(conbuy[1],0)
gobuy= conbuy==1 and close-open<2*(pacH-pacL) and high-close<(pacH-pacL)/2 and hisup==1 and MACD>0 and close-pacH<1.5*(pacH-pacL) and close>open and high-close<close-open and close>pacH
consell= hisup==1 or MACD>0 ?1 : hisdown[5]==1 and MACD[5]<0 ?-1 : nz(consell[1],0)
gosell= consell==1 and open-close<2*(pacH-pacL) and close-low<(pacH-pacL)/2 and hisdown==1 and MACD<0 and pacL-close<1.5*(pacH-pacL) and close<open and close-low<open-close and close<pacL
if(gobuy)
    strategy.entry("Buy",strategy.long)
if(gosell)
    strategy.entry("Sell",strategy.short)
//if(Trend==-1 and close<pacL)
//    strategy.close("Buy")
//if(Trend==1 and close>pacH)
//    strategy.close("Sell")
 ////////////// TP and SL//
SL = input(defval=100.00, title="Stop Loss Point", type=float, step=1)
rr= input(defval=0.1,title="Reward/Risk",type=float)
useTPandSL = input(defval = false, title = "Use exit order strategy?")
Stop = SL
Take=SL*rr
Q = 100
if(useTPandSL)
    strategy.exit("Out Long", "Buy", qty_percent=Q, profit= Take, loss=Stop)
    strategy.exit("Out Short", "Sell", qty_percent=Q, profit= Take, loss=Stop)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Price-Channel-and-MACD-Based-Multi-Timeframe-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA RSI and MACD Based Multi Timeframe Trading StrategyPine Script · Multi-timeframe · 1h
- MacD Custom Indicator Multiple Time FrameAll Available OptionsPine Script · Multi-timeframe · 1h
- CM MACD Custom Indicator Multiple Time Frame V2Pine Script · Multi-timeframe · 10m
- MACD Dissipation and Multi Time Frame Moving Average StrategyPine Script · Multi-timeframe · 1h
- Multi Timeframe Adaptive Market Regime Quantitative Trading StrategyPine Script · Multi-timeframe · 1m
- Multi Timeframe Moving Average System Trading StrategyPine Script · Multi-timeframe · 4h