Strategy vault / Trend following
Price Divergence Strategy v10
Created by Request: This is a trend trading strategy that uses Price Divergence detection signals that are confirmed by the "Murrey's Math Oscillator" (Donchanin Channel based). Strategy Code Based on: Price…
Created by Request: This is a trend trading strategy that uses Price Divergence detection signals that are confirmed by the "Murrey's Math Oscillator" (Donchanin Channel based).
Strategy Code Based on: Price Divergence Detector V2 by RicardoSantos UCS_Murrey's Math Oscillator by Ucsgears Strategy Risk Management Based on: Strategy Code Example by JayRogers
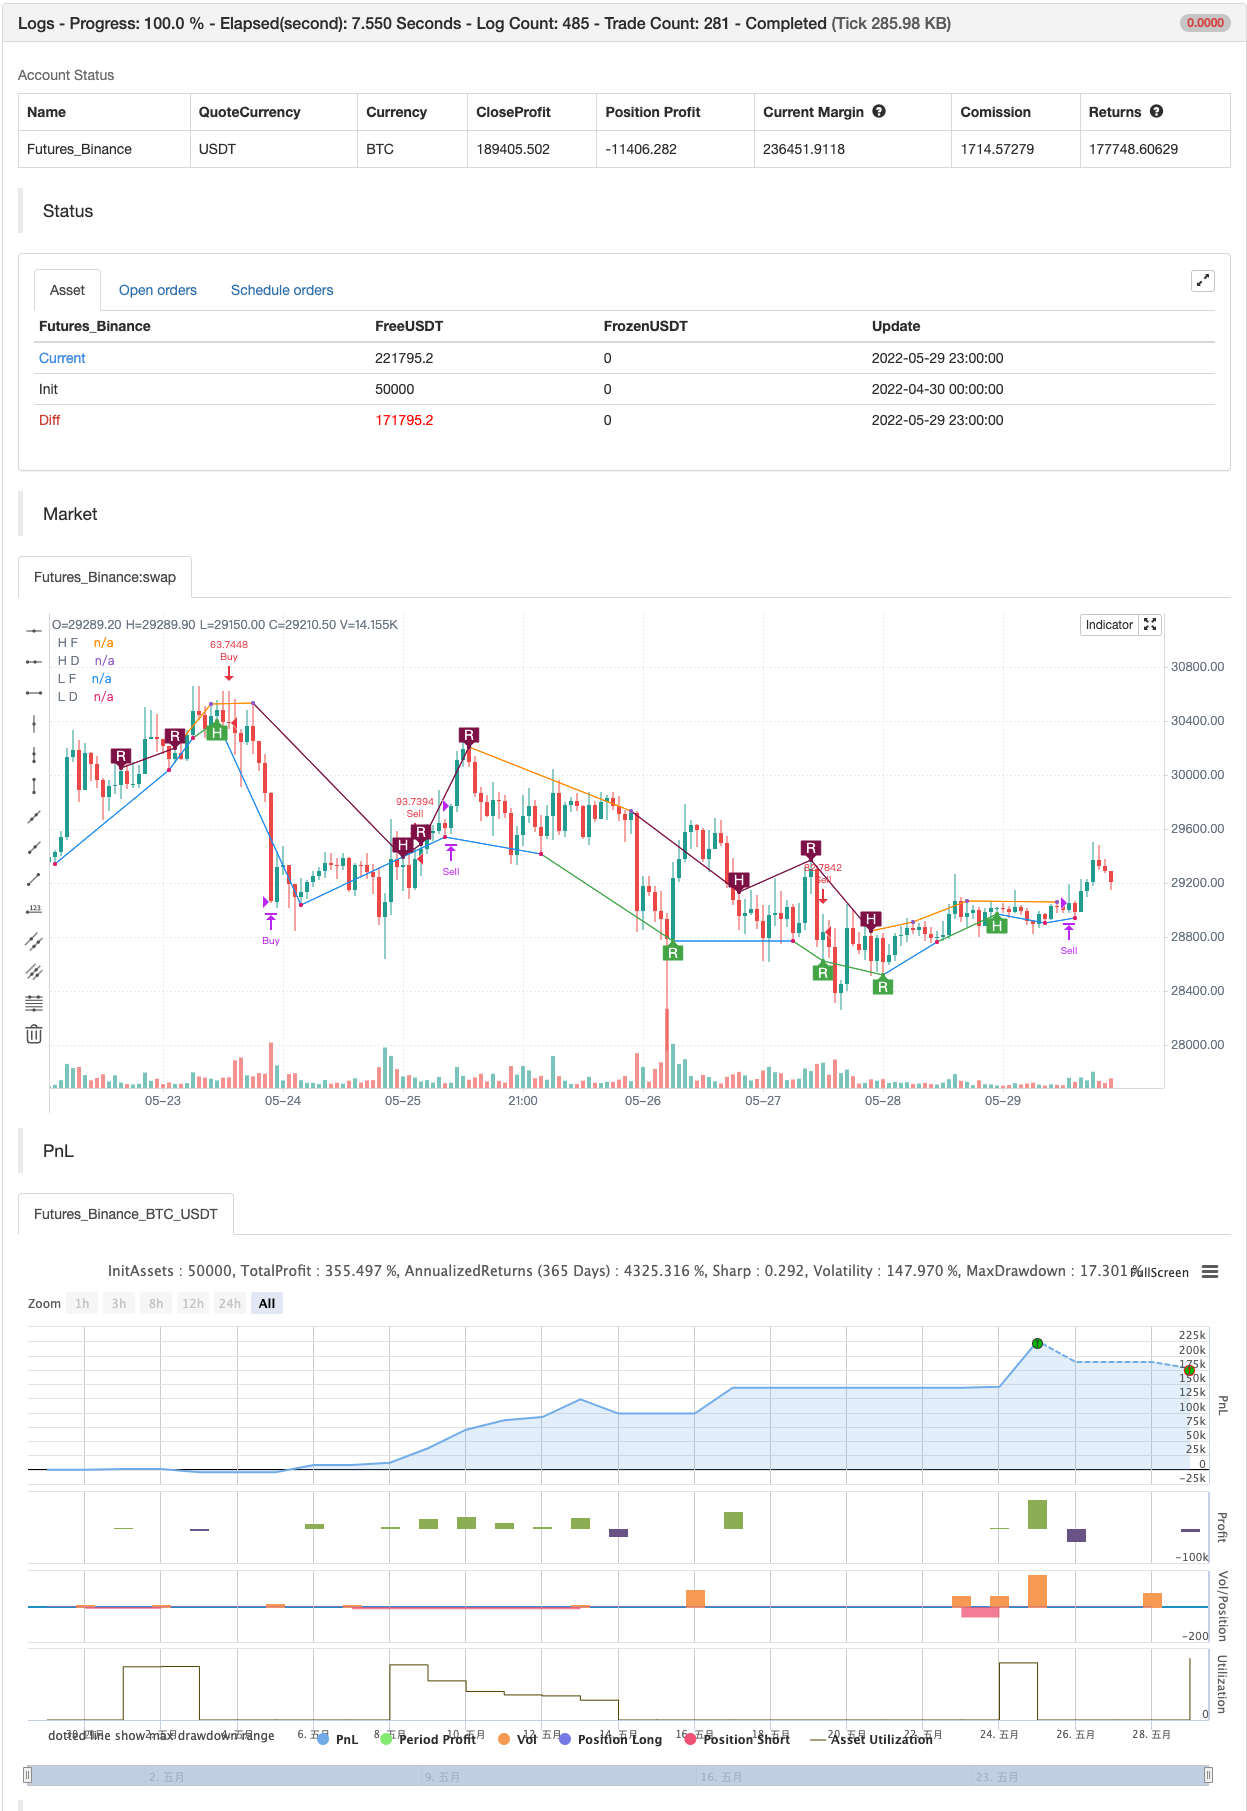
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Method (0=rsi, 1=macd, 2=stoch, 3=volume, 4=acc/dist, 5=fisher, 6=cci): |
| v_input_2 | true | Show Labels |
| v_input_3 | false | Show Channel |
| v_input_4 | true | Use Hidden Divergence in Strategy |
| v_input_5 | true | Use Regular Divergence in Strategy |
| v_input_6 | 5 | RSI/STOCH/Volume/ACC-DIST/Fisher/cci Smooth: |
| v_input_7_close | 0 | MACD Source:: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_8 | 12 | MACD Fast: |
| v_input_9 | 26 | MACD Slow: |
| v_input_10 | 9 | MACD Smooth Signal: |
| v_input_11 | 100 | MMLO Look back Length |
| v_input_12 | 2 | Mininum Quadrant for MMLO Support |
| v_input_13 | false | Take Profit Points |
| v_input_14 | false | Stop Loss Points |
| v_input_15 | 100 | Trailing Stop Loss Points |
| v_input_16 | false | Trailing Stop Loss Offset Points |
Source Pine Script
/*backtest
start: 2022-04-30 00:00:00
end: 2022-05-29 23:59:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//
// Title:   [STRATEGY][UL]Price Divergence Strategy V1.1
// Author:  JustUncleL
// Date:    23-Oct-2016
// Version: v1.1
//
// Description:
//  A trend trading strategy the uses Price Divergence detection signals, that
//  are confirmed by the "Murrey's Math Oscillator" (Donchanin Channel based).
//
//  *** USE AT YOUR OWN RISK ***
//
// Mofidifications:
//  1.0 - original
//  1.1 - Pinescript V4 update 21-Aug-2021
//
// References:
//  Strategy Based on:
//  - [RS]Price Divergence Detector V2 by RicardoSantos
//  - UCS_Murrey's Math Oscillator by Ucsgears
//  Some Code borrowed from:
//  - "Strategy Code Example by JayRogers"
//  Information on Divergence Trading:
//  - http://www.babypips.com/school/high-school/trading-divergences
//
strategy(title='[STRATEGY][UL]Price Divergence Strategy v1.1', pyramiding=0, overlay=true, initial_capital=10000, calc_on_every_tick=false, currency=currency.USD,
  default_qty_type=strategy.percent_of_equity, default_qty_value=10)
//  ||  General Input:
method = input(title='Method (0=rsi, 1=macd, 2=stoch, 3=volume, 4=acc/dist, 5=fisher, 6=cci):', type=input.integer, defval=1, minval=0, maxval=6)
SHOW_LABEL = input(title='Show Labels', type=input.bool, defval=true)
SHOW_CHANNEL = input(title='Show Channel', type=input.bool, defval=false)
uHid = input(true, title="Use Hidden Divergence in Strategy")
uReg = input(true, title="Use Regular Divergence in Strategy")
//  ||  RSI / STOCH / VOLUME / ACC/DIST Input:
rsi_smooth = input(title='RSI/STOCH/Volume/ACC-DIST/Fisher/cci Smooth:', type=input.integer, defval=5)
//  ||  MACD Input:
macd_src = input(title='MACD Source:', type=input.source, defval=close)
macd_fast = input(title='MACD Fast:', type=input.integer, defval=12)
macd_slow = input(title='MACD Slow:', type=input.integer, defval=26)
macd_smooth = input(title='MACD Smooth Signal:', type=input.integer, defval=9)
//  ||  Functions:
f_top_fractal(_src) =>
    _src[4] < _src[2] and _src[3] < _src[2] and _src[2] > _src[1] and
       _src[2] > _src[0]
f_bot_fractal(_src) =>
    _src[4] > _src[2] and _src[3] > _src[2] and _src[2] < _src[1] and
       _src[2] < _src[0]
f_fractalize(_src) =>
    f_bot_fractal__1 = f_bot_fractal(_src)
    f_top_fractal(_src) ? 1 : f_bot_fractal__1 ? -1 : 0

//  ||••>   START MACD FUNCTION
f_macd(_src, _fast, _slow, _smooth) =>
    _fast_ma = sma(_src, _fast)
    _slow_ma = sma(_src, _slow)
    _macd = _fast_ma - _slow_ma
    _signal = ema(_macd, _smooth)
    _hist = _macd - _signal
    _hist
//  ||<••   END MACD FUNCTION

//  ||••>   START ACC/DIST FUNCTION
f_accdist(_smooth) =>
    _return = sma(cum(close == high and close == low or high == low ? 0 : (2 * close - low - high) / (high - low) * volume), _smooth)
    _return
//  ||<••   END ACC/DIST FUNCTION

//  ||••>   START FISHER FUNCTION
f_fisher(_src, _window) =>
    _h = highest(_src, _window)
    _l = lowest(_src, _window)
    _value0 = 0.0
    _fisher = 0.0
    _value0 := .66 * ((_src - _l) / max(_h - _l, .001) - .5) + .67 * nz(_value0[1])
    _value1 = _value0 > .99 ? .999 : _value0 < -.99 ? -.999 : _value0
    _fisher := .5 * log((1 + _value1) / max(1 - _value1, .001)) + .5 * nz(_fisher[1])
    _fisher
//  ||<••   END FISHER FUNCTION

rsi_1 = rsi(high, rsi_smooth)
f_macd__1 = f_macd(macd_src, macd_fast, macd_slow, macd_smooth)
stoch_1 = stoch(close, high, low, rsi_smooth)
sma_1 = sma(volume, rsi_smooth)
f_accdist__1 = f_accdist(rsi_smooth)
f_fisher__1 = f_fisher(high, rsi_smooth)
cci_1 = cci(high, rsi_smooth)
method_high = method == 0 ? rsi_1 : method == 1 ? f_macd__1 :
   method == 2 ? stoch_1 : method == 3 ? sma_1 : method == 4 ? f_accdist__1 :
   method == 5 ? f_fisher__1 : method == 6 ? cci_1 : na

rsi_2 = rsi(low, rsi_smooth)
f_macd__2 = f_macd(macd_src, macd_fast, macd_slow, macd_smooth)
stoch_2 = stoch(close, high, low, rsi_smooth)
sma_2 = sma(volume, rsi_smooth)
f_accdist__2 = f_accdist(rsi_smooth)
f_fisher__2 = f_fisher(low, rsi_smooth)
cci_2 = cci(low, rsi_smooth)
method_low = method == 0 ? rsi_2 : method == 1 ? f_macd__2 :
   method == 2 ? stoch_2 : method == 3 ? sma_2 : method == 4 ? f_accdist__2 :
   method == 5 ? f_fisher__2 : method == 6 ? cci_2 : na

fractal_top = f_fractalize(method_high) > 0 ? method_high[2] : na
fractal_bot = f_fractalize(method_low) < 0 ? method_low[2] : na

high_prev = valuewhen(fractal_top, method_high[2], 1)
high_price = valuewhen(fractal_top, high[2], 1)
low_prev = valuewhen(fractal_bot, method_low[2], 1)
low_price = valuewhen(fractal_bot, low[2], 1)

regular_bearish_div = fractal_top and high[2] > high_price and method_high[2] < high_prev
hidden_bearish_div = fractal_top and high[2] < high_price and method_high[2] > high_prev
regular_bullish_div = fractal_bot and low[2] < low_price and method_low[2] > low_prev
hidden_bullish_div = fractal_bot and low[2] > low_price and method_low[2] < low_prev

plot(title='H F', series=fractal_top ? high[2] : na, color=regular_bearish_div or hidden_bearish_div ? color.maroon : not SHOW_CHANNEL ? na : color.silver, offset=-2)
plot(title='L F', series=fractal_bot ? low[2] : na, color=regular_bullish_div or hidden_bullish_div ? color.green : not SHOW_CHANNEL ? na : color.silver, offset=-2)
plot(title='H D', series=fractal_top ? high[2] : na, style=plot.style_circles, color=regular_bearish_div or hidden_bearish_div ? color.maroon : not SHOW_CHANNEL ? na : color.silver, linewidth=3, offset=-2)
plot(title='L D', series=fractal_bot ? low[2] : na, style=plot.style_circles, color=regular_bullish_div or hidden_bullish_div ? color.green : not SHOW_CHANNEL ? na : color.silver, linewidth=3, offset=-2)

plotshape(title='+RBD', series=not SHOW_LABEL ? na : regular_bearish_div ? high[2] : na, text='R', style=shape.labeldown, location=location.absolute, color=color.maroon, textcolor=color.white, offset=-2)
plotshape(title='+HBD', series=not SHOW_LABEL ? na : hidden_bearish_div ? high[2] : na, text='H', style=shape.labeldown, location=location.absolute, color=color.maroon, textcolor=color.white, offset=-2)
plotshape(title='-RBD', series=not SHOW_LABEL ? na : regular_bullish_div ? low[2] : na, text='R', style=shape.labelup, location=location.absolute, color=color.green, textcolor=color.white, offset=-2)
plotshape(title='-HBD', series=not SHOW_LABEL ? na : hidden_bullish_div ? low[2] : na, text='H', style=shape.labelup, location=location.absolute, color=color.green, textcolor=color.white, offset=-2)

// Code borrowed from UCS_Murrey's Math Oscillator by Ucsgears
//  - UCS_MMLO
// Inputs
length = input(100, minval=10, title="MMLO Look back Length")
quad = input(2, minval=1, maxval=4, step=1, title="Mininum Quadrant for MMLO Support")
mult = 0.125

// Donchanin Channel
hi = highest(high, length)
lo = lowest(low, length)
range = hi - lo
multiplier = range * mult
midline = lo + multiplier * 4

oscillator = (close - midline) / (range / 2)

a = oscillator > 0
b = oscillator > 0 and oscillator > mult * 2
c = oscillator > 0 and oscillator > mult * 4
d = oscillator > 0 and oscillator > mult * 6

z = oscillator < 0
y = oscillator < 0 and oscillator < -mult * 2
x = oscillator < 0 and oscillator < -mult * 4
w = oscillator < 0 and oscillator < -mult * 6


//  Strategy: (Thanks to JayRogers)
// === STRATEGY RELATED INPUTS ===
//tradeInvert     = input(defval = false, title = "Invert Trade Direction?")
// the risk management inputs
inpTakeProfit = input(defval=0, title="Take Profit Points", minval=0)
inpStopLoss = input(defval=0, title="Stop Loss Points", minval=0)
inpTrailStop = input(defval=100, title="Trailing Stop Loss Points", minval=0)
inpTrailOffset = input(defval=0, title="Trailing Stop Loss Offset Points", minval=0)

// === RISK MANAGEMENT VALUE PREP ===
// if an input is less than 1, assuming not wanted so we assign 'na' value to disable it.
useTakeProfit = inpTakeProfit >= 1 ? inpTakeProfit : na
useStopLoss = inpStopLoss >= 1 ? inpStopLoss : na
useTrailStop = inpTrailStop >= 1 ? inpTrailStop : na
useTrailOffset = inpTrailOffset >= 1 ? inpTrailOffset : na

// === STRATEGY - LONG POSITION EXECUTION ===
enterLong() =>  // functions can be used to wrap up and work out complex conditions
    (uReg and regular_bullish_div or uHid and hidden_bullish_div) and
       (quad == 1 ? a[1] :
       quad == 2 ? b[1] : quad == 3 ? c[1] : quad == 4 ? d[1] : false)
exitLong() =>
    oscillator <= 0
strategy.entry(id="Buy", long=true, when=enterLong())  // use function or simple condition to decide when to get in
strategy.close(id="Buy", when=exitLong())  // ...and when to get out

// === STRATEGY - SHORT POSITION EXECUTION ===
enterShort() =>
    (uReg and regular_bearish_div or uHid and hidden_bearish_div) and
       (quad == 1 ? z[1] :
       quad == 2 ? y[1] : quad == 3 ? x[1] : quad == 4 ? w[1] : false)
exitShort() =>
    oscillator >= 0
strategy.entry(id="Sell", long=false, when=enterShort())
strategy.close(id="Sell", when=exitShort())

// === STRATEGY RISK MANAGEMENT EXECUTION ===
// finally, make use of all the earlier values we got prepped
strategy.exit("Exit Buy", from_entry="Buy", profit=useTakeProfit, loss=useStopLoss, trail_points=useTrailStop, trail_offset=useTrailOffset)
strategy.exit("Exit Sell", from_entry="Sell", profit=useTakeProfit, loss=useStopLoss, trail_points=useTrailStop, trail_offset=useTrailOffset)


//EOF
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Price-Divergence-Strategy-v10.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Price Divergence Based Trend Trading StrategyPine Script · Trend following · 2h
- Trend Following Strategy Based on Moving Average Crossover 430022Pine Script · Trend following · 1d
- SuperTrend Trading Strategy with Multiple FiltersPine Script · Trend following · 1h
- Multifactor Driven Trend Trading StrategyPine Script · Trend following · 1m
- Supertrend Advance StrategyPine Script · Trend following · 5m