Strategy vault / Machine learning
Probability Enhanced RSI Strategy
This is a simple long-only strategy using RSI indicator to determine overbought and oversold levels. We enhanced it by adding stop loss and take profit, and integrating a probability module to reinforcement trading…
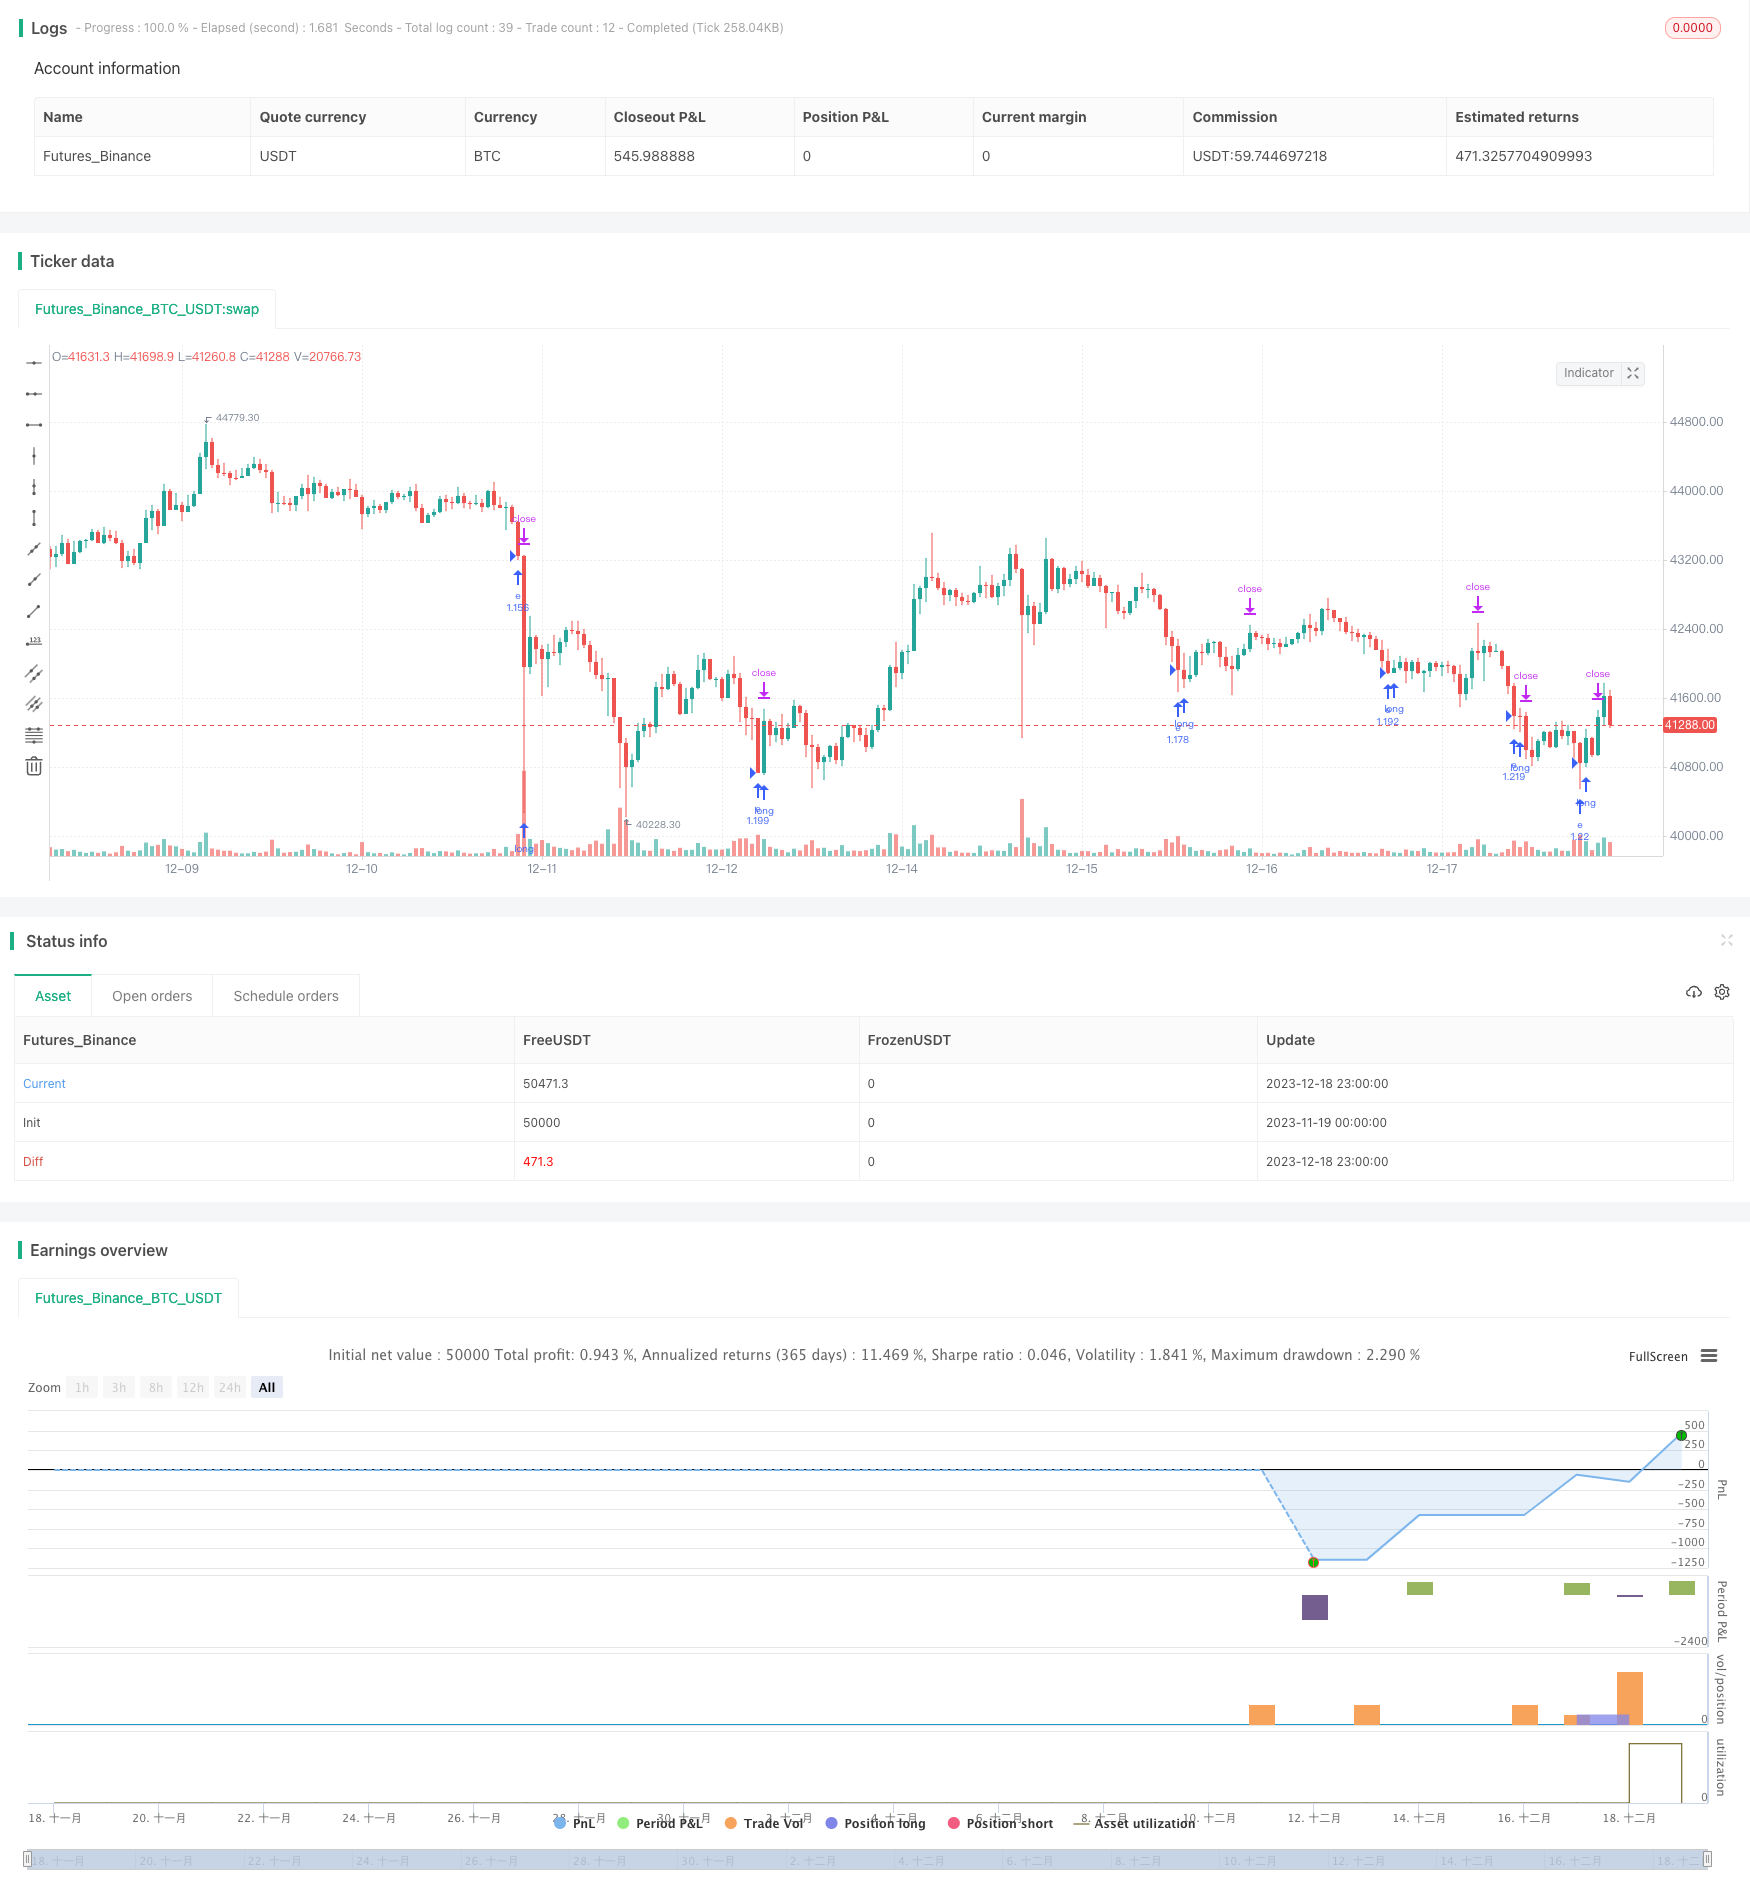
Overview
This is a simple long-only strategy using RSI indicator to determine overbought and oversold levels. We enhanced it by adding stop loss and take profit, and integrating a probability module to reinforcement trading only when the recent profitable trade probability is greater than or equal to 51%. This greatly improved the strategy performance by avoiding potential losing trades.
Principles
The strategy uses RSI indicator to judge market overbought and oversold conditions. Specifically, it goes long when RSI crosses below the lower limit of oversold zone; and closes position when RSI crosses above the upper limit of overbought zone. In addition, we set stop loss and take profit ratios.
The key is we integrated a probability judgement module. This module calculates the profitable percentage of long trades in recent periods (defined by lookback parameter). It only allows entry if recent profitable trading probability is greater than or equal to 51%. This avoids lots of potential losing trades.
Advantages
As a probability enhanced RSI strategy, it has below advantages compared to simple RSI strategies:
- Added stop loss and take profit controls single trade loss and locks profit
- Integrated probability module avoids low probability markets
- Probability module is adjustable for different market environments
- Long-only mechanism is simple to understand and implement
Risk Analysis
There are still some risks within this strategy:
- Long-only, unable to profit from falling market
- Improper probability module judgement could miss opportunities
- Hard to find best parameter combination, significant performance difference across market environments
- Loose stop loss setting, still possible large single trade loss
Solutions:
- Consider adding short mechanism
- Optimize probability module to lower misjudgement rate
- Use machine learning to dynamically optimize parameters
- Set more conservative stop loss level to limit loss
Enhancement Directions
The strategy could be further optimized in below aspects:
- Increase short module for dual direction trading
- Use machine learning for dynamic parameter optimization
- Try other indicators for overbought/oversold
- Optimize stop loss/take profit for profit ratio enhancement
- Add other factors to filter signals and improve probability
Summary
This is a simple RSI strategy enhanced by integrated probability module. Compared to vanilla RSI strategies, it filters out some losing trades and improves overall drawdown and profit ratio. Next step could be improving it by adding short, dynamic optimization etc to make it more robust.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 14 | RSI lenght: |
| v_input_int_2 | 35 | Oversold: |
| v_input_int_3 | 75 | Overbought: |
| v_input_int_4 | 30 | Lookback period: |
| v_input_float_1 | true | Take profit: |
| v_input_float_2 | true | Stop loss: |
Source Pine Script
/*backtest
start: 2023-11-19 00:00:00
end: 2023-12-19 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © thequantscience

//@version=5
strategy("Reinforced RSI",
     overlay = true,
     default_qty_type = strategy.percent_of_equity,
     default_qty_value = 100,
     pyramiding = 1,
     currency = currency.EUR,
     initial_capital = 1000,
     commission_type = strategy.commission.percent,
     commission_value = 0.07)

lenght_rsi = input.int(defval = 14, minval = 1, title = "RSI lenght: ")
rsi = ta.rsi(close, length = lenght_rsi)

rsi_value_check_entry = input.int(defval = 35, minval = 1, title = "Oversold: ")
rsi_value_check_exit = input.int(defval = 75, minval = 1, title = "Overbought: ")

trigger = ta.crossunder(rsi, rsi_value_check_entry)
exit = ta.crossover(rsi, rsi_value_check_exit)

entry_condition   = trigger
TPcondition_exit  = exit

look = input.int(defval = 30, minval = 0, maxval = 500, title = "Lookback period: ")

Probabilities(lookback) =>

    isActiveLong = false
    isActiveLong := nz(isActiveLong[1], false)
    isSellLong = false
    isSellLong := nz(isSellLong[1], false)

    int positive_results = 0
    int negative_results = 0

    float positive_percentage_probabilities = 0
    float negative_percentage_probabilities = 0

    LONG = not isActiveLong and entry_condition == true
    CLOSE_LONG_TP = not isSellLong and TPcondition_exit == true

    p = ta.valuewhen(LONG, close, 0)
    p2 = ta.valuewhen(CLOSE_LONG_TP, close, 0)

    for i = 1 to lookback

	    if (LONG[i])
            isActiveLong := true
		    isSellLong := false

        if (CLOSE_LONG_TP[i])
	        isActiveLong := false
	        isSellLong := true

        if p[i] > p2[i]
            positive_results += 1
        else
            negative_results -= 1

	    positive_relative_probabilities = positive_results / lookback
	    negative_relative_probabilities = negative_results / lookback
	    positive_percentage_probabilities := positive_relative_probabilities * 100
	    negative_percentage_probabilities := negative_relative_probabilities * 100

    positive_percentage_probabilities

probabilities = Probabilities(look)

lots = strategy.equity/close

var float e = 0
var float c = 0

tp = input.float(defval = 1.00, minval = 0, title = "Take profit: ")
sl = input.float(defval = 1.00, minval = 0, title = "Stop loss: ")

if trigger==true and strategy.opentrades==0 and probabilities >= 51
    e := close
    strategy.entry(id = "e", direction = strategy.long, qty = lots, limit = e)
takeprofit = e + ((e * tp)/100)
stoploss = e - ((e * sl)/100)
if exit==true
    c := close
    strategy.exit(id = "c", from_entry = "e", limit = c)
if takeprofit and stoploss
strategy.exit(id = "c", from_entry = "e", stop = stoploss, limit = takeprofit)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Probability-Enhanced-RSI-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- Double Decker RSI Trading StrategyPine Script · Machine learning · 1h
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- Fibonacci HMA AI Buy Sell Signal StrategyPine Script · Machine learning · 1d