Quantitative Trading Strategy Based on Fibonacci 07 Level Trend Breakthrough
This strategy is a trend breakthrough trading system based on the Fibonacci 0.7 retracement level. It generates trading signals when price breaks through the Fibonacci 0.7 level, which is calculated using the highest…
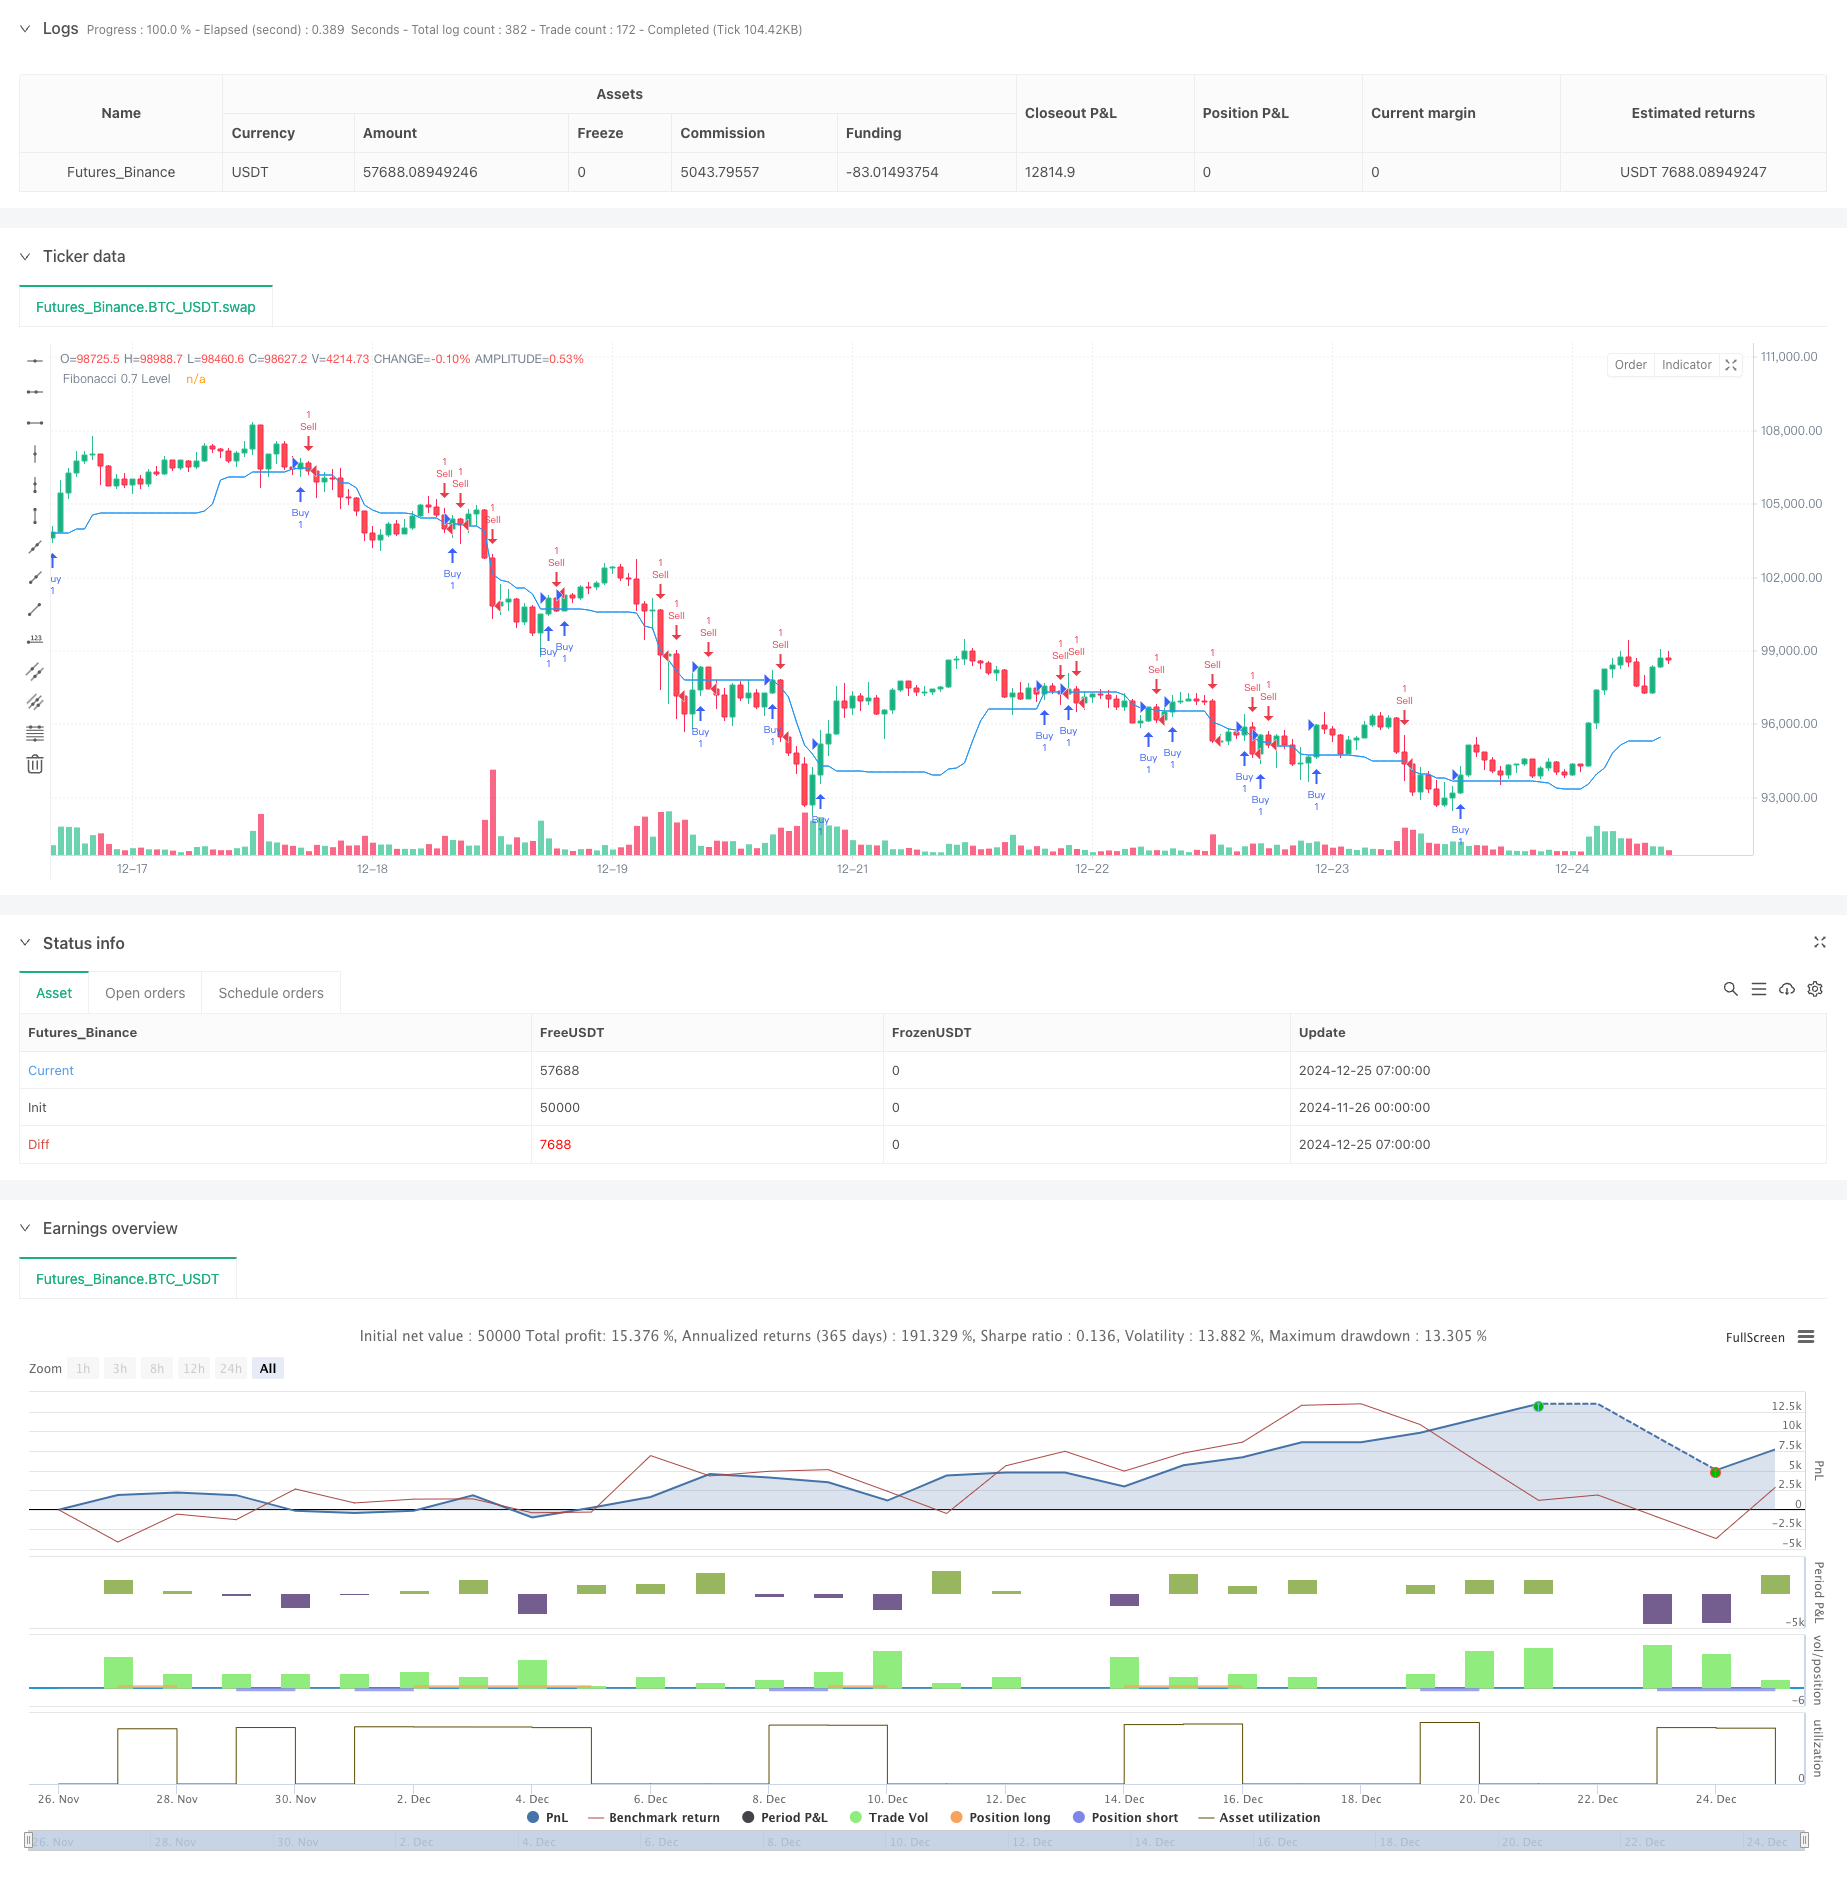
Overview
This strategy is a trend breakthrough trading system based on the Fibonacci 0.7 retracement level. It generates trading signals when price breaks through the Fibonacci 0.7 level, which is calculated using the highest and lowest prices within a specified lookback period. The strategy employs fixed percentage take-profit and stop-loss levels for risk management, using 5% of account equity as the default position size.
Strategy Principle
The core logic of the strategy is based on the following key elements:
- Dynamic Fibonacci level calculation: Continuously tracks the highest and lowest prices within the specified lookback period (default 20 periods) and calculates the 0.7 Fibonacci retracement level.
- Breakthrough signal confirmation: Generates long signals when closing price breaks above the 0.7 level and short signals when it breaks below.
- Risk management: System implements symmetrical take-profit and stop-loss conditions, with default settings of 1.8% for take-profit and 1.2% for stop-loss, reflecting a positive expected value approach.
- Position sizing: Uses a fixed percentage of account equity for position sizing, facilitating dynamic money management and consistent risk control.
Strategy Advantages
- Scientific indicator selection: Fibonacci retracement is a widely recognized technical analysis tool, with the 0.7 level typically representing strong support or resistance.
- Clear signal logic: Uses price breakthrough as trading trigger, avoiding potential lag from complex signal combinations.
- Reasonable risk-reward ratio: Take-profit and stop-loss ratio settings reflect positive expected value, conducive to long-term stable profits.
- Flexible money management: Position sizing based on account percentage automatically adjusts trading volume as account size changes.
Strategy Risks
- Market environment dependency: May generate frequent false breakthrough signals in ranging markets, increasing transaction costs.
- Parameter sensitivity: Choice of lookback period, take-profit, and stop-loss ratios significantly affects strategy performance.
- Slippage impact: May face significant slippage risk in markets with low trading volume.
- Technical limitations: Single technical indicator may not fully capture multi-dimensional market information.
Strategy Optimization Directions
- Signal filtering: Can introduce auxiliary indicators like volume and volatility to filter false breakthrough signals.
- Dynamic parameters: Consider dynamically adjusting lookback period and profit/loss ratios based on market volatility.
- Time filtering: Add trading time window restrictions to avoid highly volatile periods.
- Multi-timeframe verification: Add confirmation mechanisms across multiple timeframes to improve signal reliability.
Summary
The strategy combines classic Fibonacci theory with core elements of trend breakthrough and risk management. While it has certain limitations, through appropriate parameter optimization and signal filtering, it has the potential to maintain stable performance across various market conditions. Successful strategy implementation requires traders to deeply understand market characteristics and make appropriate adjustments and optimizations based on actual conditions.
Source Pine Script
/*backtest
start: 2024-11-26 00:00:00
end: 2024-12-25 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Fibonacci 0.7 Strategy - 60% Win Rate", overlay=true)

// Input parameters
fibonacci_lookback = input.int(20, minval=1, title="Fibonacci Lookback Period")
take_profit_percent = input.float(1.8, title="Take Profit (%)")
stop_loss_percent = input.float(1.2, title="Stop Loss (%)")

// Calculating Fibonacci levels
var float high_level = na
var float low_level = na
if (ta.change(ta.highest(high, fibonacci_lookback)))
    high_level := ta.highest(high, fibonacci_lookback)
if (ta.change(ta.lowest(low, fibonacci_lookback)))
    low_level := ta.lowest(low, fibonacci_lookback)

fib_level_0_7 = high_level - ((high_level - low_level) * 0.7)

// Entry Conditions
buy_signal = close > fib_level_0_7 and close[1] <= fib_level_0_7
sell_signal = close < fib_level_0_7 and close[1] >= fib_level_0_7

// Risk management
long_take_profit = strategy.position_avg_price * (1 + take_profit_percent / 100)
long_stop_loss = strategy.position_avg_price * (1 - stop_loss_percent / 100)
short_take_profit = strategy.position_avg_price * (1 - take_profit_percent / 100)
short_stop_loss = strategy.position_avg_price * (1 + stop_loss_percent / 100)

// Execute trades
if (buy_signal)
    strategy.entry("Buy", strategy.long)
if (sell_signal)
    strategy.entry("Sell", strategy.short)

// Take Profit and Stop Loss
if (strategy.position_size > 0)
    strategy.exit("Take Profit/Stop Loss", "Buy", stop=long_stop_loss, limit=long_take_profit)
if (strategy.position_size < 0)
    strategy.exit("Take Profit/Stop Loss", "Sell", stop=short_stop_loss, limit=short_take_profit)

// Plot Fibonacci Level
plot(fib_level_0_7, color=color.blue, title="Fibonacci 0.7 Level")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quantitative-Trading-Strategy-Based-on-Fibonacci-07-Level-Trend-Breakthrough.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Breakthrough of Daily High low Price Based on Fibonacci LevelsPine Script · Breakout · 10m
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d
- Y Profit Maximizer StrategyPine Script · Breakout · 1d
- 24 Hour Volume Price Fibonacci Retracement MA Cross Trading StrategyPine Script · Breakout · 1d
- Adaptive Multi Level Trading Strategy Based on Fibonacci RetracementPine Script · Breakout · 4h