Strategy vault / Trend following
Quantitative Trading Strategy Based on SMA and Rolling Trendline
This strategy combines the Simple Moving Average (SMA) and rolling linear regression trendline. It sets the long entry condition when the close price is above both SMA and trendline, and exit condition when the close…
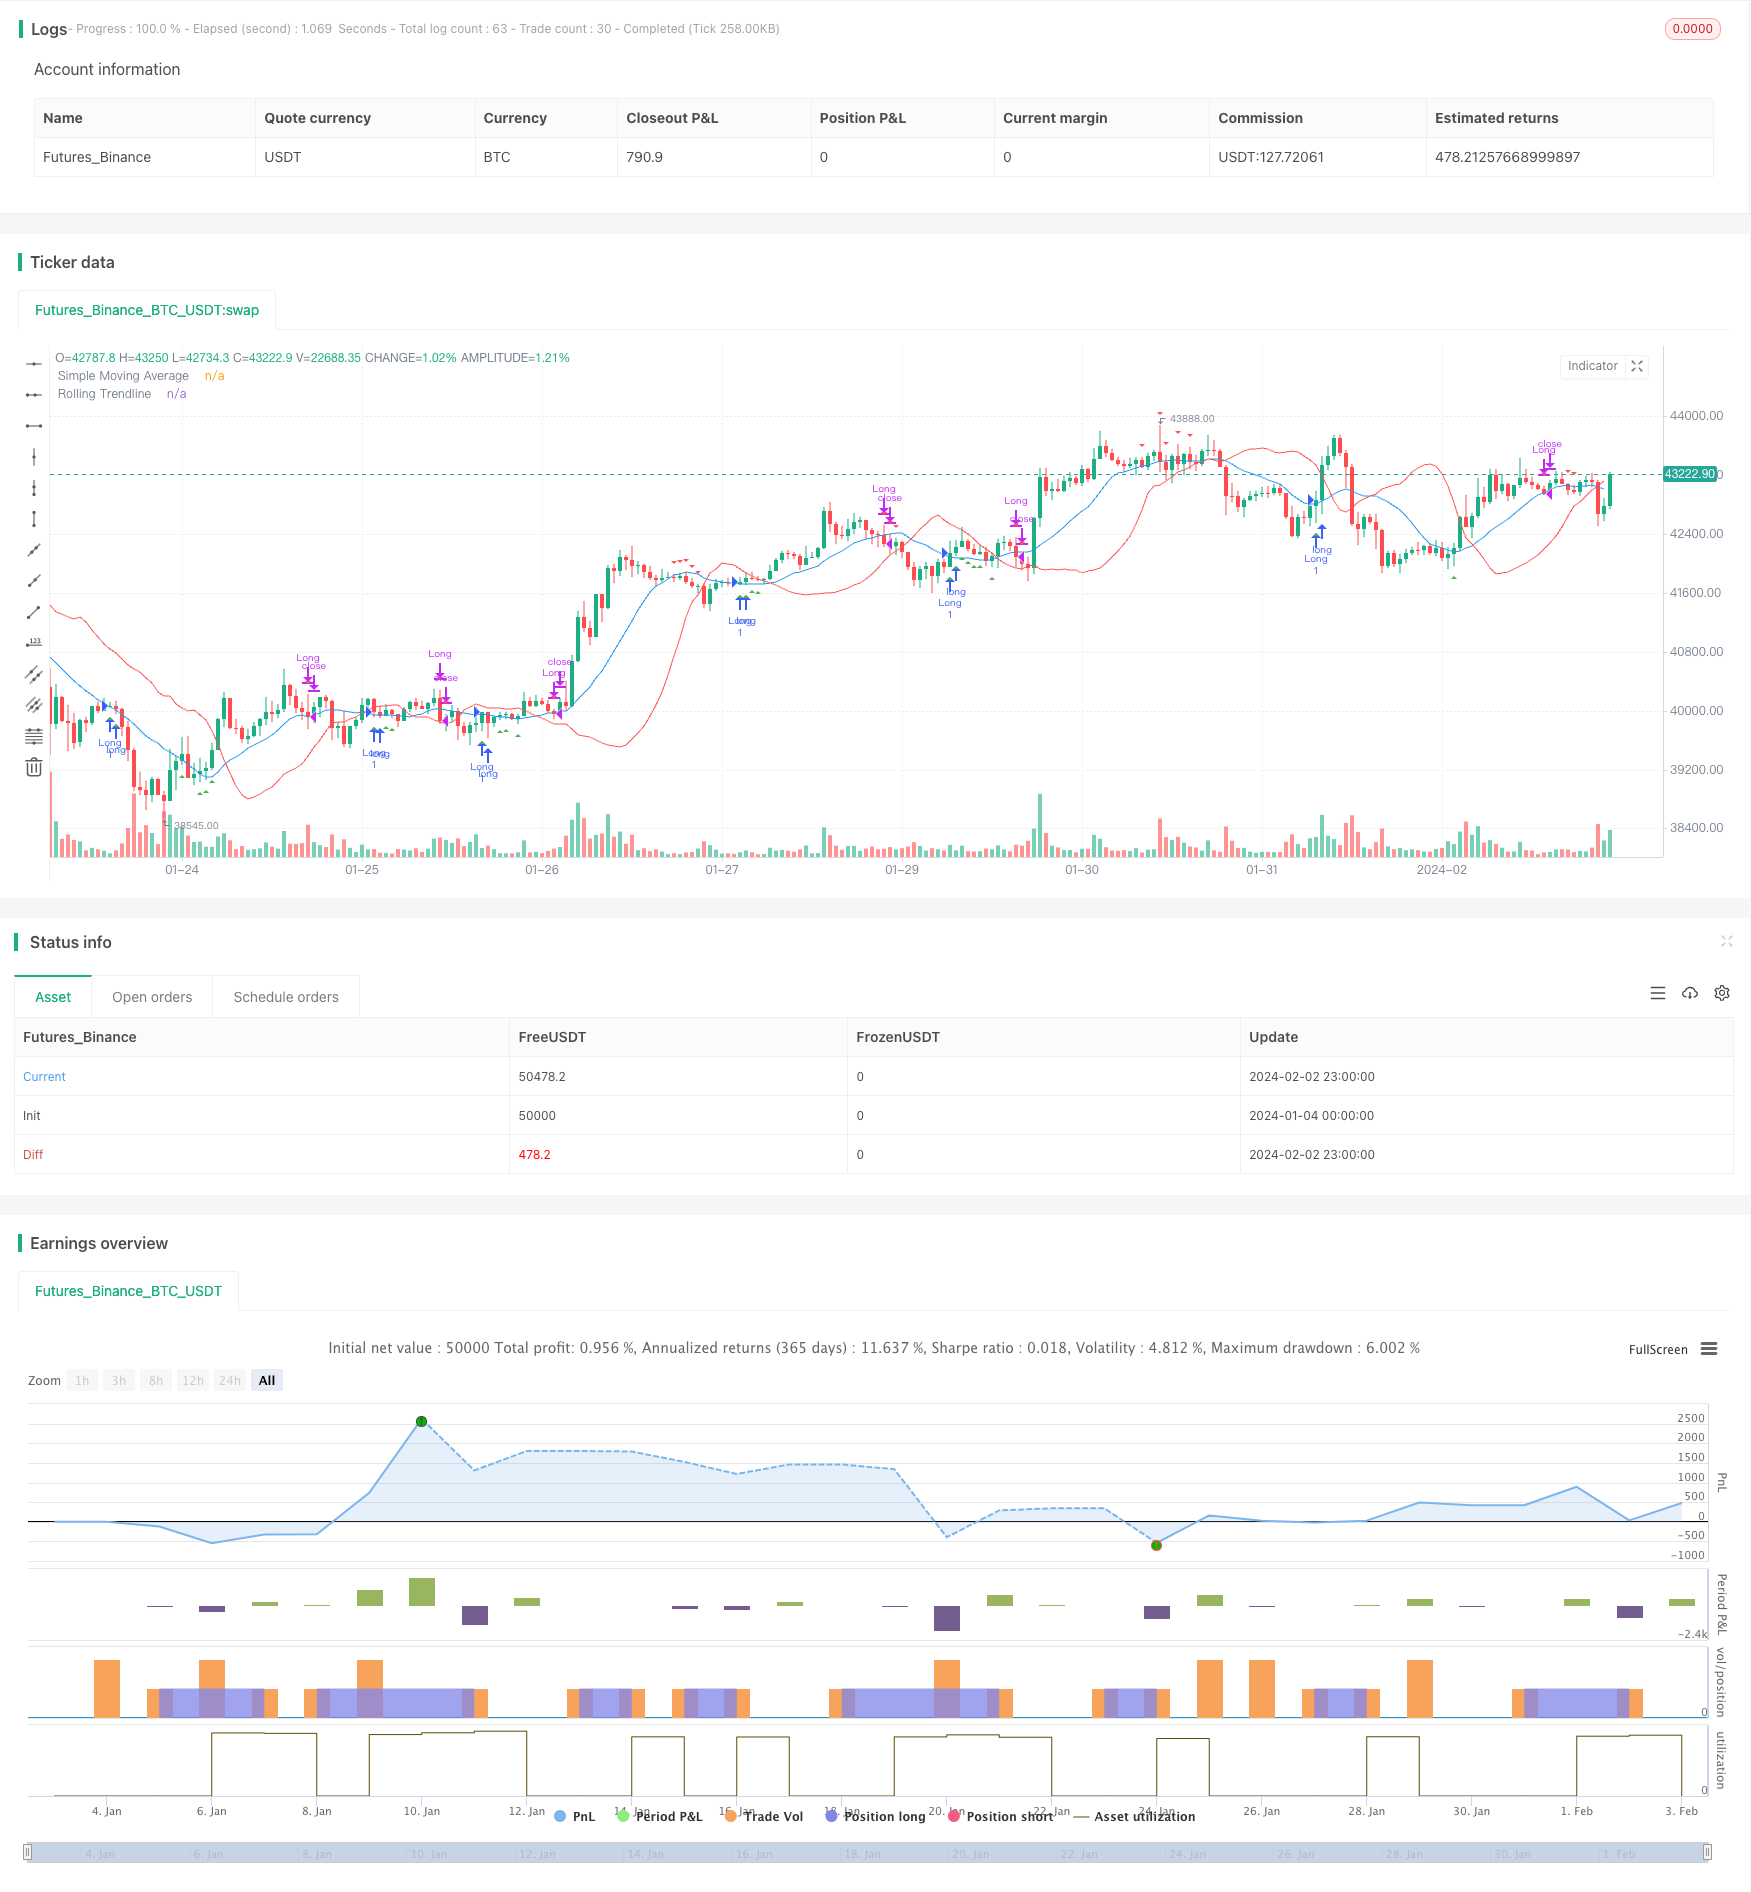
Overview
This strategy combines the Simple Moving Average (SMA) and rolling linear regression trendline. It sets the long entry condition when the close price is above both SMA and trendline, and exit condition when the close price is below them. The strategy mainly utilizes the SMA as trading signal and rolling trendline for channel support. It enters trade when breakout of the upside channel and exits when breakout of the downside channel.
Strategy Logic
The key components of this strategy include:
SMA: Simple moving average, calculating average close price over a period (smaPeriod) as signal line.
Rolling Trendline: Fitting the best linear regression line over a window (window) as trend signal. Calculated by Ordinary Least Square method.
Entry Condition: Go long when close price > SMA and trendline.
Exit Condition: Close position when close price < SMA and trendline.
So the strategy mainly relies on SMA signal breakout for entry, and channel breakout for exit. It utilizes the mean reversion attribute of MA and channel support by linear regression line to implement trend following breakout operations.
Advantage Analysis
This strategy integrates dual filter of MA and trendline, which can effectively reduce false breakout trades. Meanwhile, rolling trendline provides more precise channel support for reliable decisions. The main advantages include:
- Dual filter mechanism avoids false breakout and improves decision accuracy.
- Rolling trendline offers dynamic channel support for more accurate channel trading.
- Simple and intuitive trading logic, easy to understand and implement.
- Customizable parameters adapt to different market environments.
Risk Analysis
There are also some risks of this strategy:
- Improper parameters of SMA and trendline may lead to missing trades or too many false breakouts.
- In highly volatile markets, the channel support by SMA and trendline may weaken.
- Failed breakout can lead to losses, strict stop loss is required.
Some optimizing directions for these risks:
- Optimize parameters for different products.
- Increase stop loss range to reduce single loss.
- Suspend trading in volatile market to avoid being trapped.
Strategy Optimization
This strategy can be optimized in the following aspects:
Add dynamic adjustment functions for SMA period, slippage parameters based on market regimes.
Develop elastic stop loss mechanism. Set stop loss when price breaks trendline at a ratio.
Add filter from other indicators e.g. Volume, RSI to improve decision accuracy.
Develop reversal version. Go long when price approaches bottom and breaks the downside channel.
Conclusion
This strategy integrates the trading signals from moving average and channel support from rolling trendline to implement trend following operations. The dual filter reduces false breakout probability and improves decision quality. It has simple parameters settings and clear logics, which is easy to implement and optimize. In summary, this strategy forms a reliable, simple and intuitive trend breakout trading system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | SMA Period |
| v_input_2 | 20 | Trendline Window |
| v_input_3 | timestamp(2023-01-01) | Start Date |
| v_input_4 | timestamp(2023-12-31) | End Date |
Source Pine Script
/*backtest
start: 2024-01-04 00:00:00
end: 2024-02-03 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("SMA Strategy with Rolling Trendline", overlay=true)

// Input parameters
smaPeriod = input(14, title="SMA Period")
window = input(20, title="Trendline Window")
startDate = input(timestamp("2023-01-01"), title="Start Date")
endDate = input(timestamp("2023-12-31"), title="End Date")

// Calculating SMA
sma = sma(close, smaPeriod)

// Function to calculate linear regression trendline for a window
linreg_trendline(window) =>
    sumX = 0.0
    sumY = 0.0
    sumXY = 0.0
    sumX2 = 0.0
    for i = 0 to window - 1
        sumX := sumX + i
        sumY := sumY + close[i]
        sumXY := sumXY + i * close[i]
        sumX2 := sumX2 + i * i
    slope = (window * sumXY - sumX * sumY) / (window * sumX2 - sumX * sumX)
    intercept = (sumY - slope * sumX) / window
    slope * (window - 1) + intercept

// Calculating the trendline
trendline = linreg_trendline(window)

// Entry and Exit Conditions
longCondition = close > sma and close < trendline
exitLongCondition = close < sma and close > trendline

// Strategy logic
if (true)
    if (longCondition)
        strategy.entry("Long", strategy.long)
    if (exitLongCondition)
        strategy.close("Long")

// Plotting
plot(sma, title="Simple Moving Average", color=color.blue)
plot(trendline, title="Rolling Trendline", color=color.red)
plotshape(series=longCondition, title="Enter Trade", location=location.belowbar, color=color.green, style=shape.triangleup)
plotshape(series=exitLongCondition, title="Exit Trade", location=location.abovebar, color=color.red, style=shape.triangledown)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Quantitative-Trading-Strategy-Based-on-SMA-and-Rolling-Trendline.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crypto RSI Mini Sniper Quick Response Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d