Strategy vault / Mean reversion
Recursive Moving Trend Average Combined with 123 Reversal Pattern Strategy
This strategy combines the Recursive Moving Trend Average and the 123 Reversal Pattern into a composite signal to improve the stability and profitability.
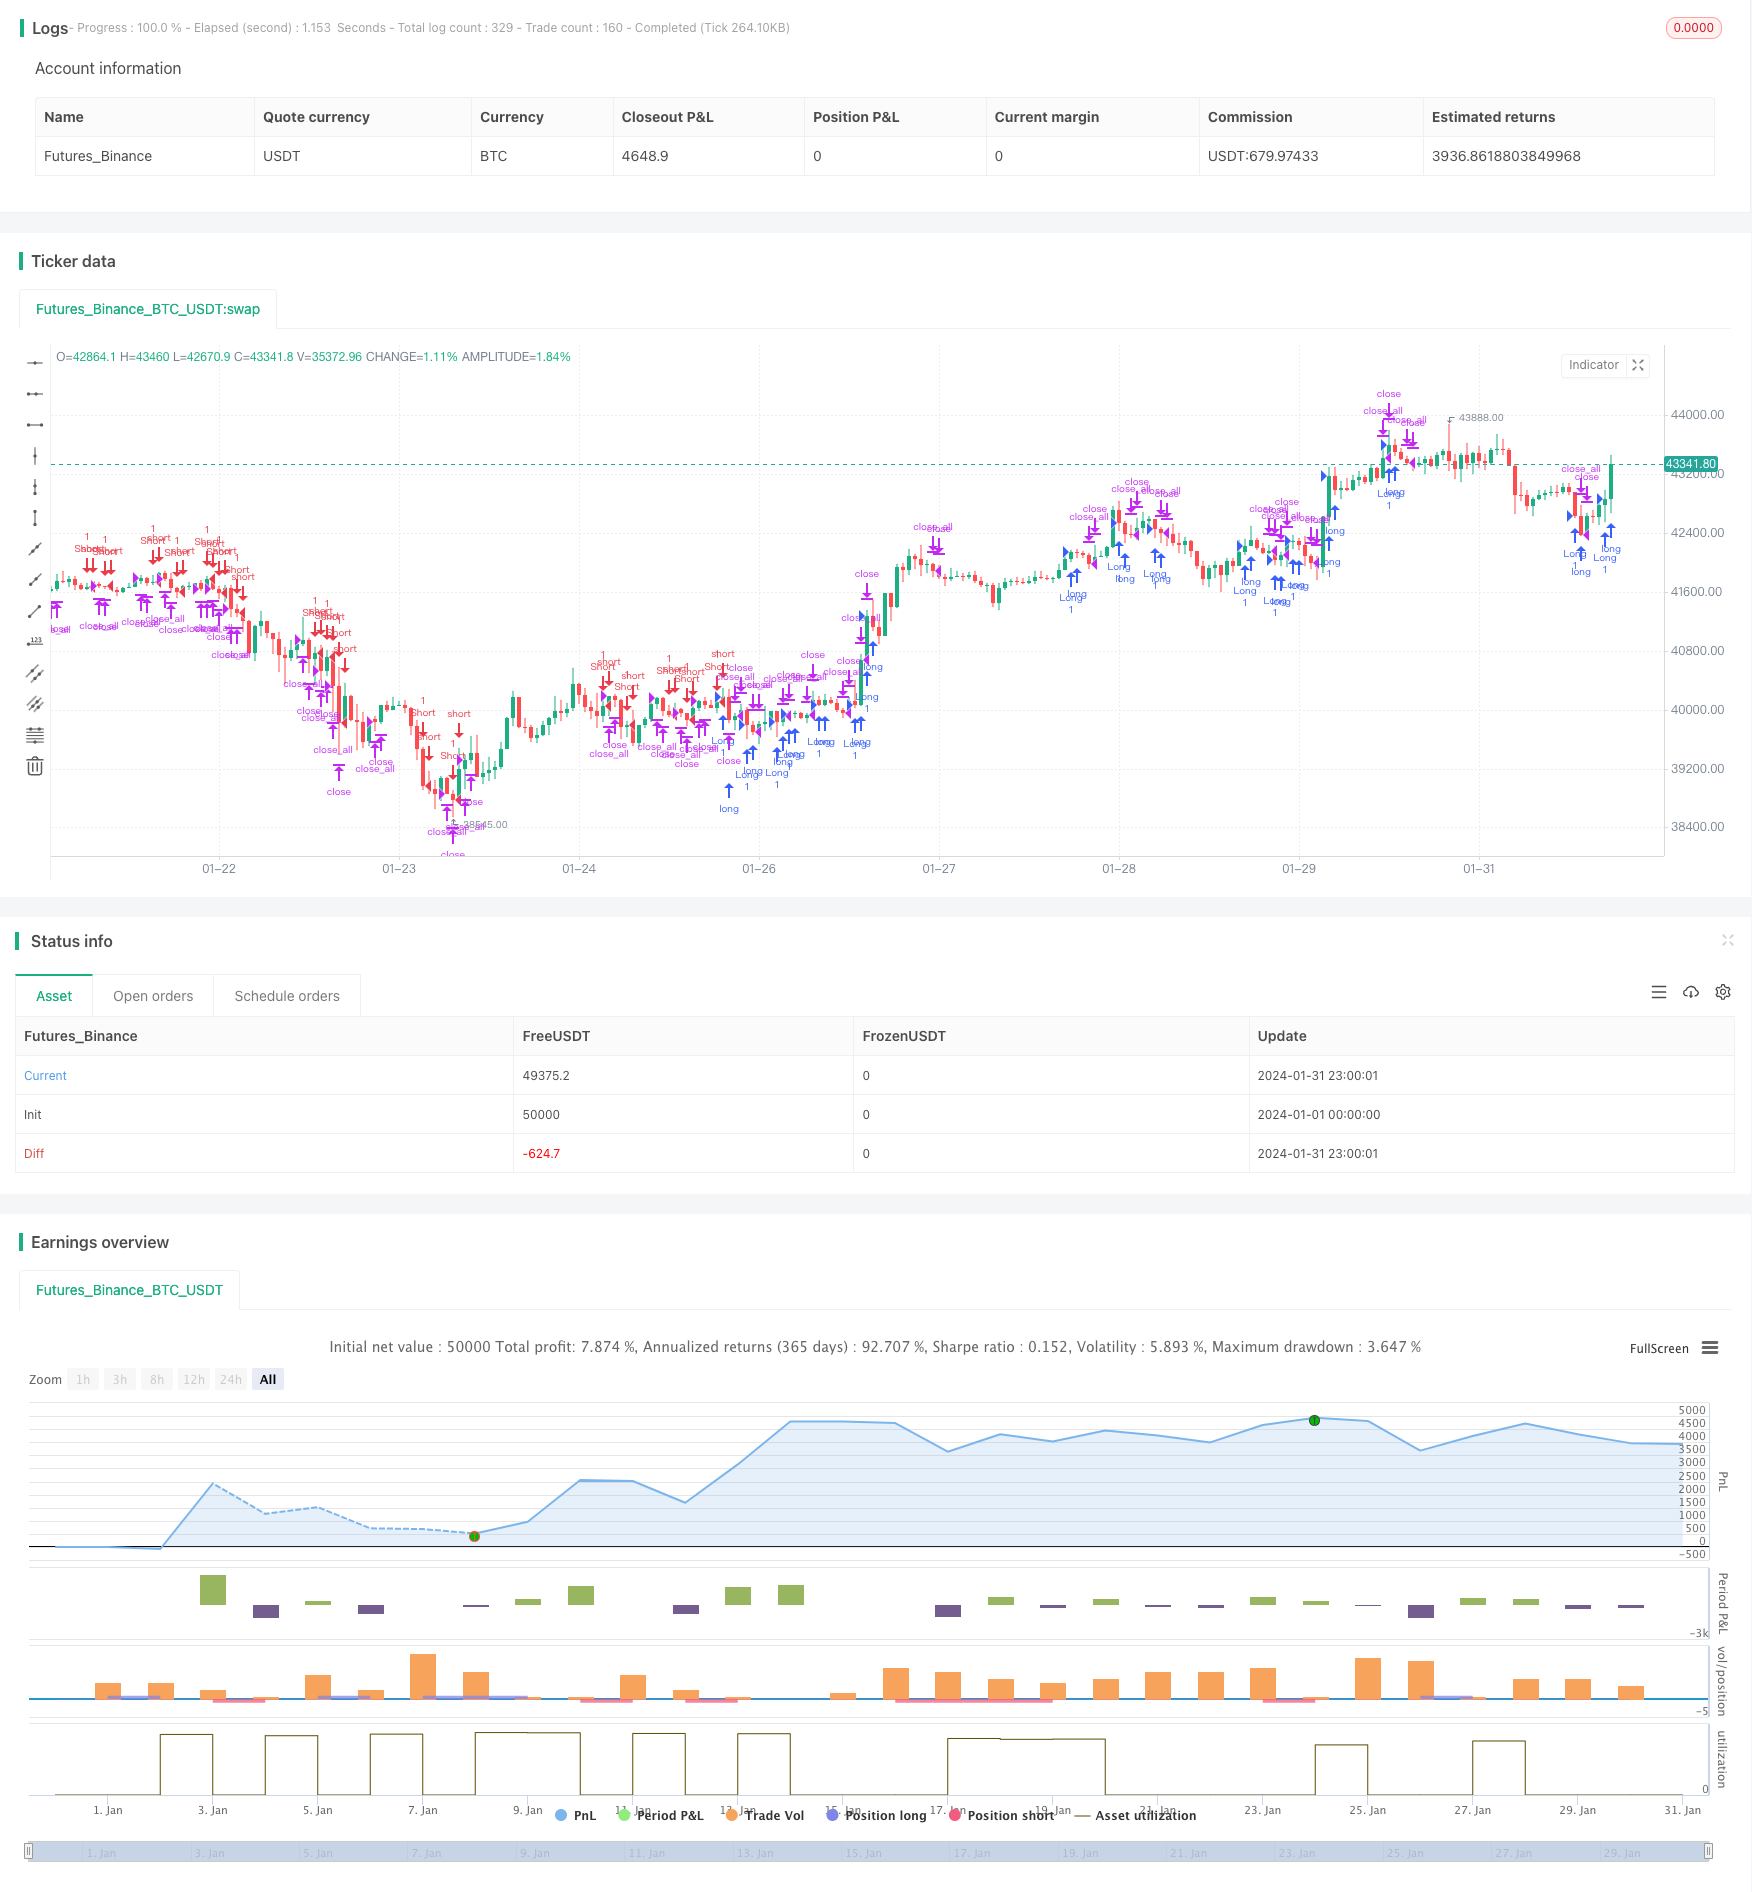
Overview
This strategy combines the Recursive Moving Trend Average and the 123 Reversal Pattern into a composite signal to improve the stability and profitability.
Principle
123 Reversal Pattern
This part is inspired by the book "How I Tripled My Money in the Futures Market" by Ulf Jensen. It buys when the close price rises for two consecutive days and the 9-day STO SLOWK is below 50. It sells when the close price falls for two consecutive days and the 9-day STO FASTK is above 50.
Recursive Moving Trend Average
This technique is called "recursive polynomial fitting". It uses the prices of the past few days and today's price to predict tomorrow's price. It goes short when the predicted price is higher than yesterday's actual price, and goes long otherwise.
Advantages
The combined strategy exploits the strengths of both strategies to avoid the limitations of a single one. The 123 Reversal Pattern can catch major trends when price reversal happens. The Recursive Moving Trend Average can judge the price movement direction more accurately. Together they form stronger composite signals.
Risks and Solutions
- The 123 Reversal Pattern may generate false signals due to short-term price fluctuations. Fine tuning the parameters helps filter out noise.
- The Recursive Moving Trend Average may respond slowly to sudden events. Considering other indicators for local trends is helpful.
- The two strategies may give inconsistent signals sometimes. One solution is to open positions only when double signals emerge, or follow just one signal based on market conditions.
Directions for Enhancement
- Test different combination of period parameters to find the optimal pair.
- Introduce auto stop-loss mechanisms.
- Adjust parameters based on different products and market environments.
- Consider combining with other strategies or indicators to form more robust systems.
Conclusion
This strategy combines two different types of strategies and generates composite signals to improve stability. It exploits both their advantages to catch price reversal points and judge future price trends. Further optimizations may lead to even better performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- Recursive Moving Trend Average ---- |
| v_input_7 | 21 | LengthRMTA |
| v_input_8 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 01/06/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// Taken from an article "The Yen Recused" in the December 1998 issue of TASC,
// written by Dennis Meyers. He describes the Recursive MA in mathematical terms
// as "recursive polynomial fit, a technique that uses a small number of past values
// of the estimated price and today's price to predict tomorrows price."
// Red bars color - short position. Green is long.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


RMTA(Length) =>
    pos = 0.0
    Bot = 0.0
    nRes = 0.0
    Alpha = 2 / (Length+1)
    Bot := (1-Alpha) * nz(Bot[1],close) + close
    nRes := (1-Alpha) * nz(nRes[1],close) + (Alpha*(close + Bot - nz(Bot[1], 0)))
    pos:= iff(nRes > close[1], -1,
    	     iff(nRes < close[1], 1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Recursive Moving Trend Average", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- Recursive Moving Trend Average ----")
LengthRMTA = input(21, minval=3)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posRMTA = RMTA(LengthRMTA)
pos = iff(posReversal123 == 1 and posRMTA == 1 , 1,
	   iff(posReversal123 == -1 and posRMTA == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Recursive-Moving-Trend-Average-Combined-with-123-Reversal-Pattern-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h