Strategy vault / Trend following
Renko and Relative Vigor Index Trend Following Strategy
This strategy combines the Renko charts and Relative Vigor Index (RVI) to capture most of the major market trends. It works well on major symbols like BTCUSD, HSI etc.
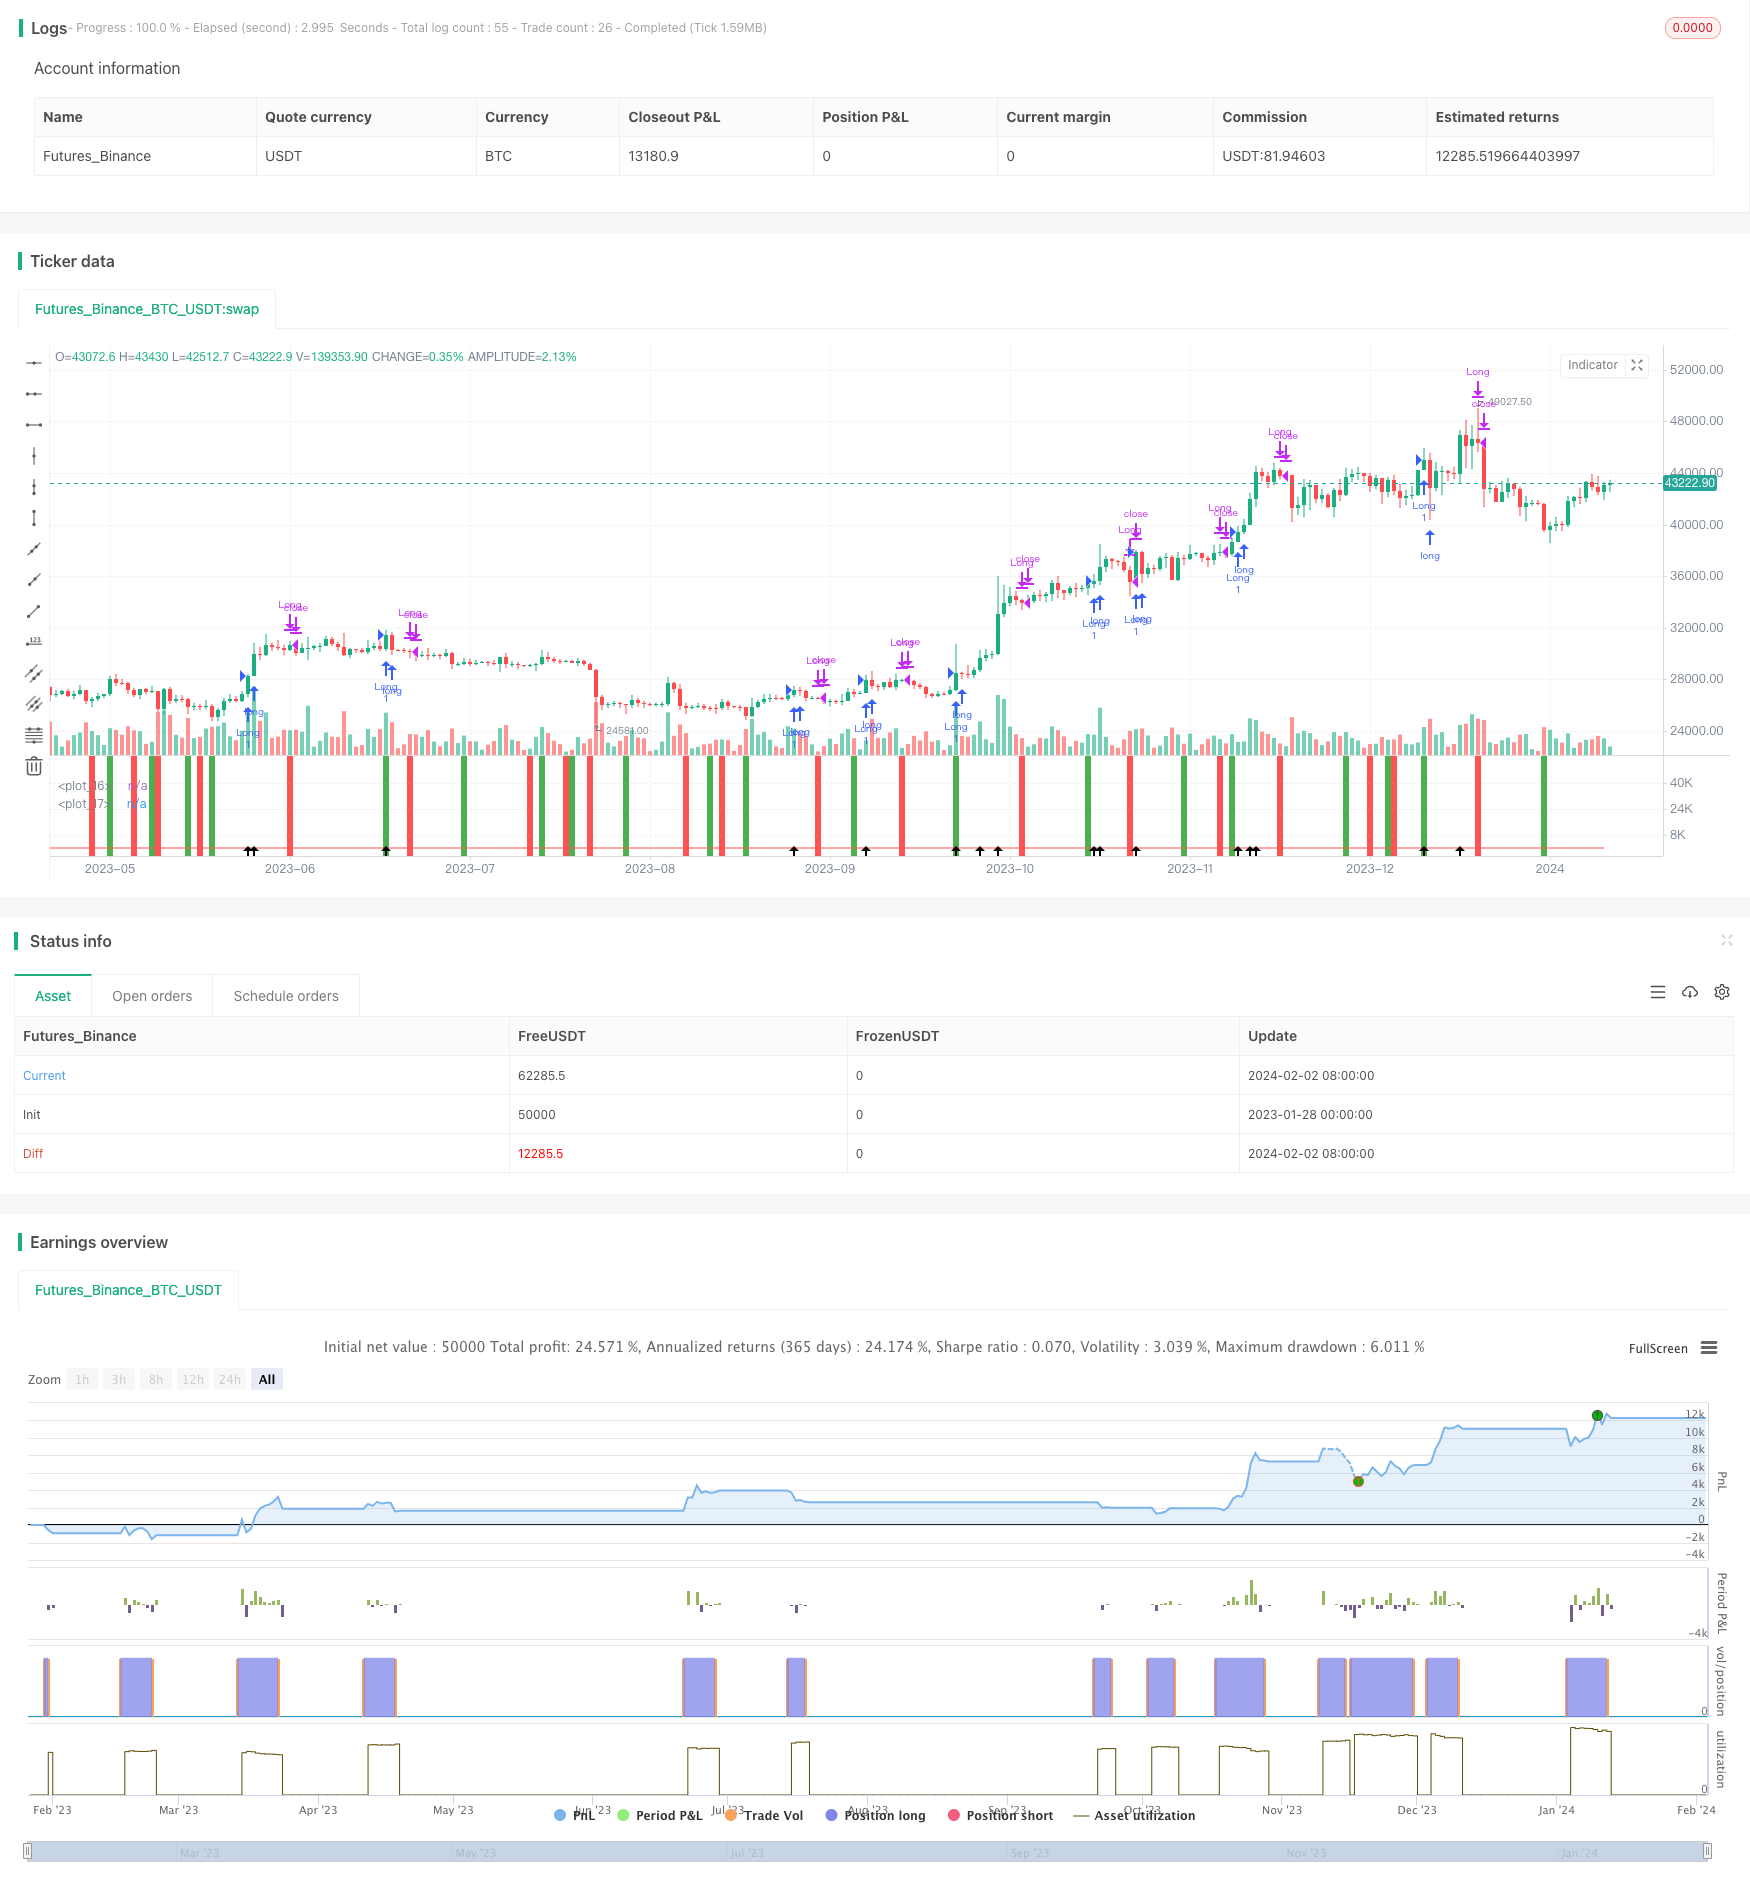
Overview
This strategy combines the Renko charts and Relative Vigor Index (RVI) to capture most of the major market trends. It works well on major symbols like BTCUSD, HSI etc.
Strategy Logic
The strategy constructs Renko bricks based on 9 period ATR. A new green brick is constructed when close price exceeds the previous brick's high. A new red brick is constructed when close price falls below the previous brick's low. The trend direction is determined by RVI indicator.
RVI oscillates between 0-1 to measure the relative strength between buying and selling pressure. Above 0.5 represents stronger buying pressure while below 0.5 represents stronger selling pressure. RVI crossing above its smooth moving average gives buy signal as selling pressure eases. RVI crossing below gives sell signal as buying pressure eases.
Combine the Renko brick direction and RVI signals to enter long or short positions accordingly.
Advantages
- Renko bricks filter out normal market noise and only react to significant price movement, avoiding whipsaws.
- RVI helps identifying trend reversal, further confirming trading signals.
- Combining two indicators filters out some noise and enables capturing major trends.
Risks
- Brick size directly affects trading frequency. Bricks too large may miss opportunity while too small increases costs.
- Improper RVI parameters may cause missing signals or more false signals.
- Double filtering misses some trading opportunity.
Enhancement
- Dynamic brick size to adapt changing volatility.
- Optimize RVI parameters to find best balance.
- Test stability across different symbols and timeframes.
Conclusion
This strategy combines two different types of indicators to capture major trends. Further optimization on Renko and RVI parameters can improve stability. No model is perfect and missing some trades is inevitable. Users need to assess their own risk preference and choose proper symbol/parameter combo.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | D | TimeFrame |
| v_input_2 | 9 | ATR length |
| v_input_3 | 5 | SMA length |
| v_input_4 | 20 | SMA CurTF length |
Source Pine Script
/*backtest
start: 2023-01-28 00:00:00
end: 2024-02-03 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Lancelot RR Strategy", overlay=false)
p=9
CO=close-open
HL=high-low
value1 = (CO + 2*CO[1] + 2*CO[2] + CO[3])/6
value2 = (HL + 2*HL[1] + 2*HL[2] + HL[3])/6
num=sum(value1,p)
denom=sum(value2,p)
RVI=denom!=0?num/denom:0
RVIsig=(RVI+ 2*RVI[1] + 2*RVI[2] + RVI[3])/6

rvicloselongcondition = crossunder(RVI, RVIsig)
rvicloseshortcondition = crossover(RVI, RVIsig)

plot(RVI,color=green,style=line,linewidth=1)
plot(RVIsig,color=red,style=line,linewidth=1)
bgcolor(rvicloseshortcondition ? green : na, transp = 75)
bgcolor(rvicloselongcondition ? red : na, transp = 75)

///Renko///
TF = input(title='TimeFrame', defval="D")
ATRlength = input(title="ATR length",  defval=9, minval=2, maxval=100)
SMAlength = input(title="SMA length",  defval=5, minval=2, maxval=100)
SMACurTFlength = input(title="SMA CurTF length",  defval=20, minval=2, maxval=100)

HIGH = request.security(syminfo.tickerid, TF, high)
LOW = request.security(syminfo.tickerid, TF, low)
CLOSE = request.security(syminfo.tickerid, TF, close)
ATR = request.security(syminfo.tickerid, TF, atr(ATRlength))
SMA = request.security(syminfo.tickerid, TF, sma(close, SMAlength))
SMACurTF = sma(close, SMACurTFlength)

RENKOUP = na
RENKODN = na
H = na
COLOR = na
BUY = na
SELL = na
UP = na
DN = na
CHANGE = na

RENKOUP := na(RENKOUP[1]) ? ((HIGH+LOW)/2)+(ATR/2) : RENKOUP[1]
RENKODN := na(RENKOUP[1]) ? ((HIGH+LOW)/2)-(ATR/2) : RENKODN[1]
H := na(RENKOUP[1]) or na(RENKODN[1]) ? RENKOUP-RENKODN : RENKOUP[1]-RENKODN[1]
COLOR := na(COLOR[1]) ? white : COLOR[1]
BUY := na(BUY[1]) ? 0 : BUY[1]
SELL := na(SELL[1]) ? 0 : SELL[1]
UP := false
DN := false
CHANGE := false

if(not CHANGE and close >= RENKOUP[1]+H*3)
    CHANGE := true
    UP := true
    RENKOUP := RENKOUP[1]+ATR*3
    RENKODN := RENKOUP[1]+ATR*2
    COLOR := lime
    SELL := 0
    BUY := BUY+3

if(not CHANGE and close >= RENKOUP[1]+H*2)
    CHANGE := true
    UP := true
    RENKOUP := RENKOUP[1]+ATR*2
    RENKODN := RENKOUP[1]+ATR
    COLOR := lime
    SELL := 0
    BUY := BUY+2

if(not CHANGE and close >= RENKOUP[1]+H)
    CHANGE := true
    UP := true
    RENKOUP := RENKOUP[1]+ATR
    RENKODN := RENKOUP[1]
    COLOR := lime
    SELL := 0
    BUY := BUY+1

if(not CHANGE and close <= RENKODN[1]-H*3)
    CHANGE := true
    DN := true
    RENKODN := RENKODN[1]-ATR*3
    RENKOUP := RENKODN[1]-ATR*2
    COLOR := red
    BUY := 0
    SELL := SELL+3

if(not CHANGE and close <= RENKODN[1]-H*2)
    CHANGE := true
    DN := true
    RENKODN := RENKODN[1]-ATR*2
    RENKOUP := RENKODN[1]-ATR
    COLOR := red
    BUY := 0
    SELL := SELL+2

if(not CHANGE and close <= RENKODN[1]-H)
    CHANGE := true
    DN := true
    RENKODN := RENKODN[1]-ATR
    RENKOUP := RENKODN[1]
    COLOR := red
    BUY := 0
    SELL := SELL+1

plotshape(UP, style=shape.arrowup, location=location.bottom, size=size.normal)

renkolongcondition = UP
renkoshortcondition = DN

///Long Entry///
longcondition = UP
if (longcondition)
    strategy.entry("Long", strategy.long)

///Long exit///
closeconditionlong = rvicloselongcondition
if (closeconditionlong)
strategy.close("Long")Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Renko-and-Relative-Vigor-Index-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m