Reversal Breakout Strategy
The reversal breakout strategy utilizes Bollinger Bands and Stochastic Oscillator to identify potential reversal points when an asset is overbought or oversold. It is suitable for intraday traders to capitalize on…
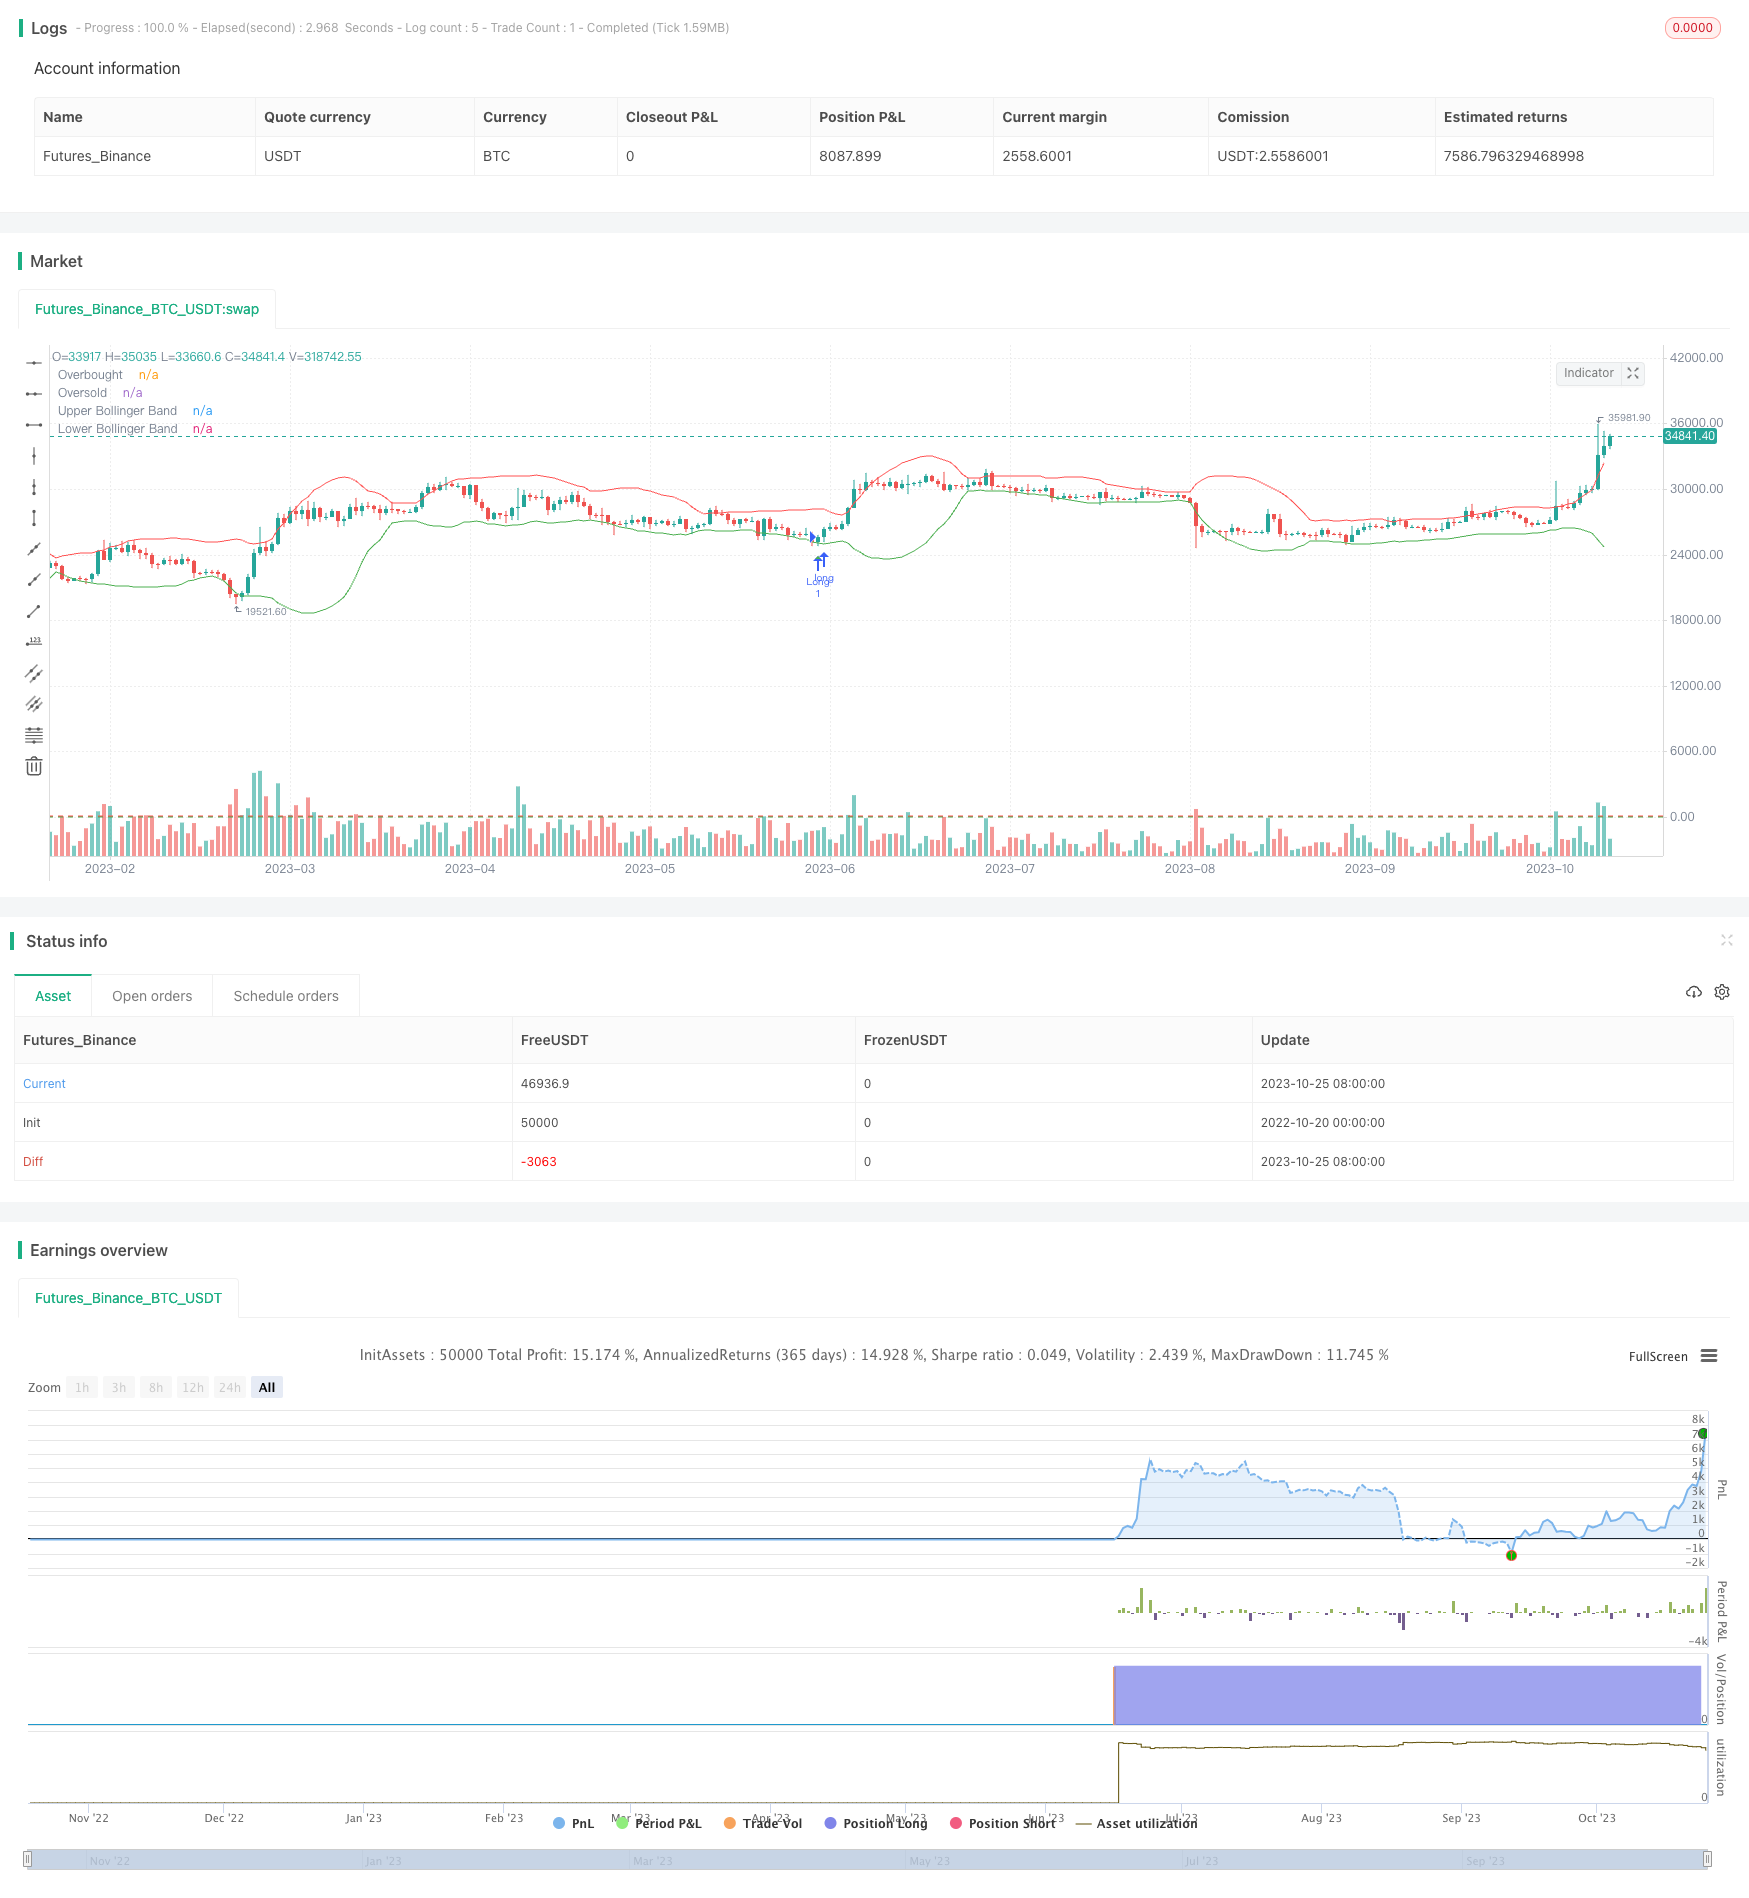
Overview
The reversal breakout strategy utilizes Bollinger Bands and Stochastic Oscillator to identify potential reversal points when an asset is overbought or oversold. It is suitable for intraday traders to capitalize on small price fluctuations for profits. The main idea is to look for trading opportunities when the price breaks out of the Bollinger Bands and Stochastic shows overbought/oversold signals.
Strategy Logic
The strategy uses both Bollinger Bands and Stochastic as the main technical indicators. Bollinger Bands are plotted at standard deviation levels above and below a simple moving average. Prices reaching the upper band are considered overbought while lower band oversold. Stochastic Oscillator determines if prices have moved too far and are due for a reversal. Readings above 80 suggest overbought conditions while below 20 oversold.
The trading rules are: go long when price breaks below the lower Bollinger band and Stochastic is below 20; go short when price breaks above the upper band and Stochastic is above 80. The stop loss is placed a few pips below the low (for longs) or above the high (for shorts). Take profit target is set at average price swing beyond recent bars.
The crossovers identify the band breakouts. Shape markers plot the entry signals. Stops and profit targets are defined after entry.
Advantages
Combining bands for support/resistance and Stochastic for overbought/oversold improves signal quality vs. a single indicator. Reversal trading after band breakouts has potential for larger gains.
The tight stop loss helps limit losses. Take profit based on average true range aims for balanced reward/risk. High frequency trading captures small moves.
Risks
Band breakouts assume mean reversion which may fail. Stochastic lags price so some moves may be missed.
Small stops restrain the profit potential. Frequent trading needs strong psychology - avoiding over-stopping.
Enhancements
Test longer Bollinger periods or confirm closes outside bands to improve quality.
Combine other indicators like MACD and KD with Stochastic for better overbought/oversold signals.
Consider dynamic stops based on volatility instead of fixed pips.
Conclusion
The strategy seeks to identify reversals by combining Bollinger Bands for support/resistance and Stochastic for overbought/oversold conditions. Fine tuning parameters, controlling risk, and ongoing optimization are key for real-world performance. Transaction costs should be considered. Past performance is no guarantee of future results.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | Bollinger Bands Length |
| v_input_2_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | 2 | Multiplier |
| v_input_4 | 14 | Stochastic Length |
| v_input_5 | 5 | Stochastic %K Smoothing |
| v_input_6 | 3 | Stochastic %D Smoothing |
| v_input_7 | 50 | Take Profit (pips) |
| v_input_8 | 3 | Stop Loss (pips) |
Source Pine Script
/*backtest
start: 2022-10-20 00:00:00
end: 2023-10-26 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Bollinger Bands & Stochastic Scalping Strategy", shorttitle="BB & Stoch Scalp", overlay=true)

// Bollinger Bands
length = input(20, title="Bollinger Bands Length")
src = input(close, title="Source")
mult = input(2, title="Multiplier")
basis = sma(src, length)
dev = mult * stdev(src, length)
upperBB = basis + dev
lowerBB = basis - dev

// Stochastic
stochLength = input(14, title="Stochastic Length")
smoothK = input(5, title="Stochastic %K Smoothing")
smoothD = input(3, title="Stochastic %D Smoothing")
k = sma(stoch(close, high, low, stochLength), smoothK)
d = sma(k, smoothD)

// Entry Conditions
longCondition = crossover(close, lowerBB) and crossover(k, 20)
shortCondition = crossunder(close, upperBB) and crossunder(k, 80)

// Exit Conditions
takeProfit = input(50, title="Take Profit (pips)")

plotshape(series=longCondition, title="Long Entry Signal", location=location.belowbar, color=color.green, style=shape.triangleup, size=size.small)
plotshape(series=shortCondition, title="Short Entry Signal", location=location.abovebar, color=color.red, style=shape.triangledown, size=size.small)

// Stop Loss
stopLossPips = input(3, title="Stop Loss (pips)")
stopLossLong = close - stopLossPips * syminfo.mintick
stopLossShort = close + stopLossPips * syminfo.mintick

strategy.entry("Long", strategy.long, when=longCondition)
strategy.entry("Short", strategy.short, when=shortCondition)

strategy.exit("Take Profit/Stop Loss", from_entry="Long", profit=takeProfit, stop=stopLossLong)
strategy.exit("Take Profit/Stop Loss", from_entry="Short", profit=takeProfit, stop=stopLossShort)

plot(upperBB, title="Upper Bollinger Band", color=color.red)
plot(lowerBB, title="Lower Bollinger Band", color=color.green)

hline(80, "Overbought", color=color.red)
hline(20, "Oversold", color=color.green)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Reversal-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m
- Volatility Breakthrough StrategyPine Script · Breakout · 10m
- Amazing Price Breakout StrategyPine Script · Breakout · 1h
- Cross Timeframe SuperTrend Breakout StrategyPine Script · Breakout · 1h