Robust Dual Moving Average Trading Strategy
The Robust Dual Moving Average Trading Strategy combines the power of both Relative Strength Index (RSI) and Rate of Change (ROC) indicators to identify the direction of intermediate-to-long-term trends. With…
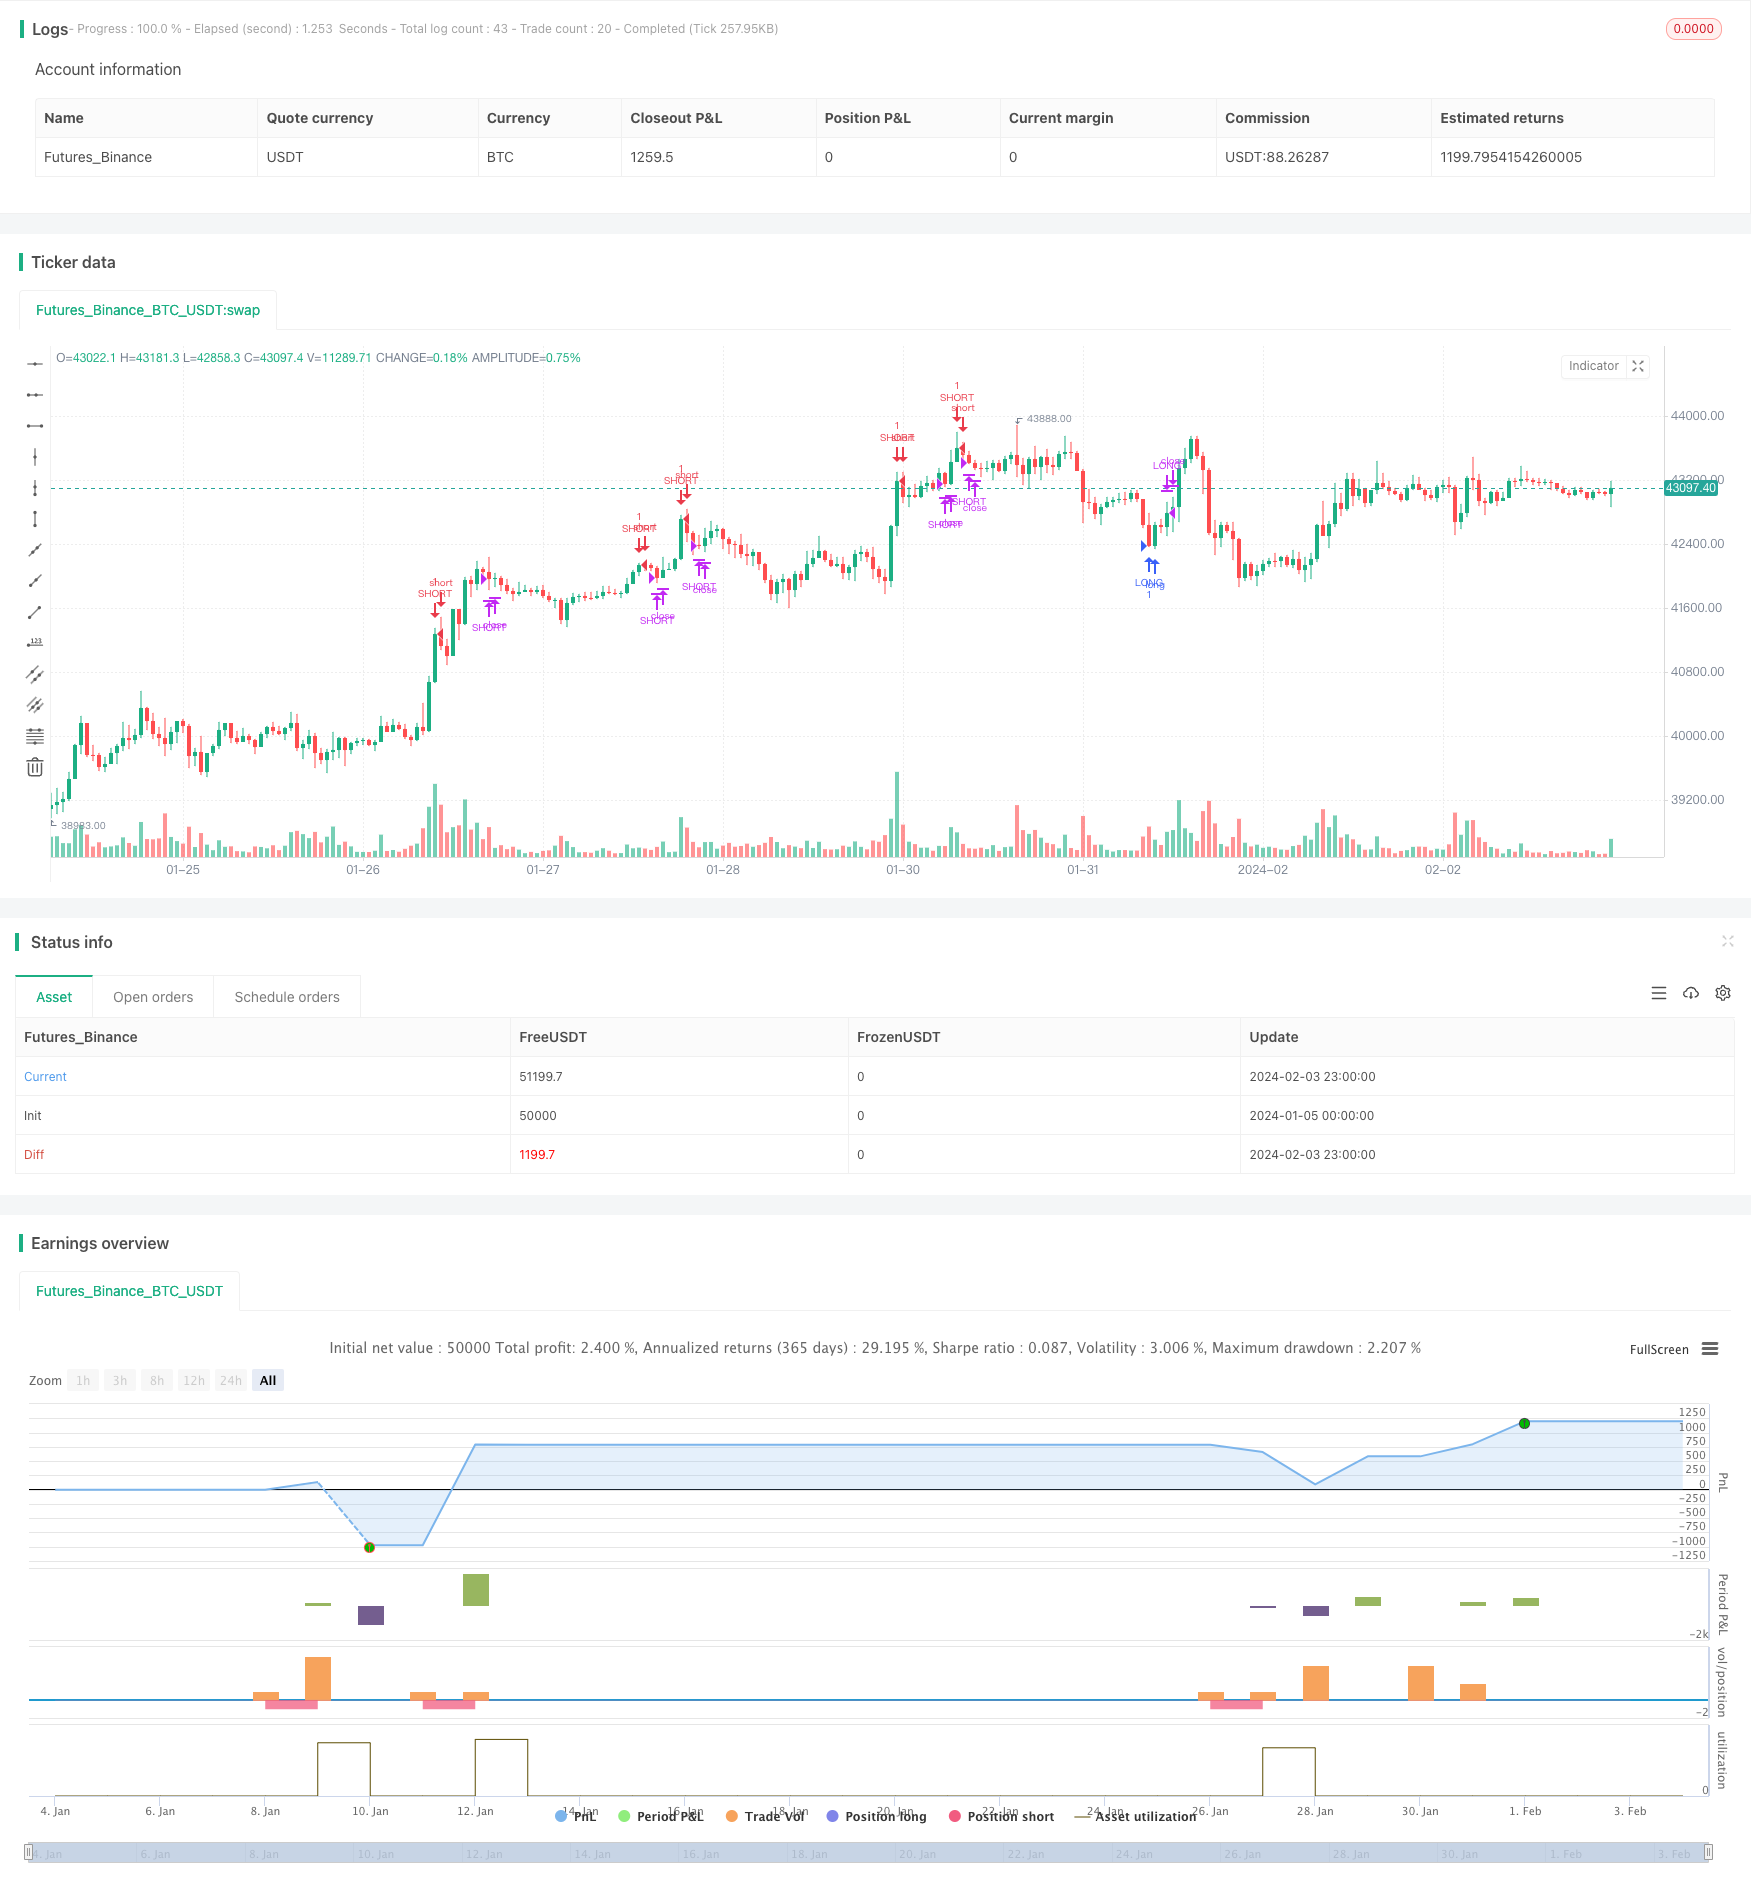
Overview
The Robust Dual Moving Average Trading Strategy combines the power of both Relative Strength Index (RSI) and Rate of Change (ROC) indicators to identify the direction of intermediate-to-long-term trends. With built-in filters and stop loss conditions, this strategy enters the market only after the trend direction is confirmed, which effectively reduces the risk of false breakouts.
Strategy Logic
This strategy uses a combination of RSI and ROC indicators to determine entry signals. When prices approach the overbought/oversold areas, it indicates potential reversal points and formation of reversal signals. When prices oscillate within these areas, it suggests the current trend may persist for some time. The ROC indicator judges price trend and momentum from the perspective of rate of change. The two indicators complement each other in assessing market structure.
In addition, the strategy incorporates intermediate-to-long-term trend filters (SMA) and short-term stop loss lines before entering any trades. This ensures that entries only occur in confirmed trend direction and without imminent stop loss risks in oscillating markets. Such configurations reduce the likelihood of being whipsawed in range-bound environments, making the strategy risk-manageable for traders.
The flexible input settings also allow traders to choose between RSI only, ROC only or a combination of both as the entry trigger. This expands the adaptability of the strategy across different products and market conditions.
Advantage Analysis
The biggest advantage of this strategy lies in combining both trend and reversal signals for entry decisions, taking into consideration both trend and structural factors to ensure precise timing. Compared to single-indicator strategies, the RSI+ROC combo also makes the strategy more robust against market noise and randomness.
Another advantage is the built-in trend filters (SMA) and short-term stop loss, which reduce the probability of being trapped in oscillating markets. The two lines of defense via trend diagnosis and short-term stop loss make this a risk-controllable robust strategy.
Lastly, the multiple parameter setting combinations allow traders to optimize the strategy for different products and market environments. Whether in trending or range-bound markets, the strategy can be adaptive through parameter tuning.
Risk Analysis
The biggest risk of the strategy comes from the lagging nature of reversal signal indicators like RSI and ROC. When trends start to shift, these indicators often lag behind before reaching the threshold levels set in the parameters. Such lag may delay the strategy's entry and cause it to miss the initial stage of trend launches.
Another potential risk is that in oscillating markets, the RSI and ROC parameter settings may become too sensitive and generate certain false signals. If triggered concurrently with short-term stop loss, such false signals can lead to actual losses.
Optimization Directions
The strategy can be optimized in the following aspects:
Incorporate more indicators for combo usage like KDJ, MACD to improve signal accuracy with multi-dimensional assessments of market structure
Introduce adaptive optimization mechanisms into RSI and ROC parameters so the settings can dynamically adjust based on real-time volatility
Refine entry logic by adding confirmation mechanisms when trend tools and reversal tools concurrently meet conditions, avoiding acting on false signals in oscillations
Expand stop loss range or set trailing stop loss to provide reversals more room, reducing missed profits due to stop loss clustering
Conclusion
The Robust Dual Moving Average Trading Strategy successfully combines trend diagnosis and reversal indicators to capture structural opportunities upon intermediate-to-long-term trend confirmation. With robust configurability, traders can optimize parameters for individual stocks and market conditions. The dual line of defense also makes it a risk-controllable choice. Further performance improvements can be achieved by incorporating more indicators or establishing adaptive parameter tuning mechanisms.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Long Only or Short Only or Both?: Both | Long Only | Short Only |
| v_input_2 | 0 | RSI Only, ROC Only, Both?: Both | RSI Only | ROC Only |
| v_input_3 | 14 | RSI Length |
| v_input_4 | 70 | RSI Upper Threshold |
| v_input_5 | 30 | RSI Lower Threshold |
| v_input_6 | 14 | ROC Length |
| v_input_7 | 0.01 | ROC Upper Threshold |
| v_input_8 | -0.01 | ROC Lower Threshold |
| v_input_9 | 5 | Long Exit SMA Length |
| v_input_10 | 5 | Short Exit SMA Length |
| v_input_11 | 0 | Trend SMA Filter?: Above | Below | Don't Include |
| v_input_12 | 200 | Trend SMA Length |
Source Pine Script
/*backtest
start: 2024-01-05 00:00:00
end: 2024-02-04 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © GlobalMarketSignals

//@version=4
strategy("GMS: RSI & ROC Strategy", overlay=true)

LongShort = input(title="Long Only or Short Only or Both?", type=input.string, defval="Both", options=["Both", "Long Only", "Short Only"])
RSIroc = input(title="RSI Only, ROC Only, Both?", type=input.string, defval="Both", options=["Both", "RSI Only", "ROC Only"])
RSILength = input(title="RSI Length", type = input.integer ,defval=14)
RSIUpper = input(title="RSI Upper Threshold", type = input.float ,defval=70)
RSILower = input(title="RSI Lower Threshold", type = input.float ,defval=30)
ROCLength = input(title="ROC Length", type = input.integer ,defval=14)
ROCUpper = input(title="ROC Upper Threshold", type = input.float ,defval=0.01)
ROCLower = input(title="ROC Lower Threshold", type = input.float ,defval=-0.01)
LongExit = input(title="Long Exit SMA Length", type = input.integer ,defval=5)
ShortExit = input(title="Short Exit SMA Length", type = input.integer ,defval=5)
AboveBelow = input(title="Trend SMA Filter?", type=input.string, defval="Above", options=["Above", "Below", "Don't Include"])
TrendLength = input(title="Trend SMA Length", type = input.integer ,defval=200)

//RSI ONLY
 //Long Side

if LongShort =="Long Only" and AboveBelow == "Above" and RSIroc == "RSI Only"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Below" and RSIroc == "RSI Only"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Don't Include" and RSIroc == "RSI Only"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Above" and RSIroc == "RSI Only"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Below" and RSIroc == "RSI Only"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Don't Include" and RSIroc == "RSI Only"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

//RSI ONLY
 //SHORT SIDE

if LongShort =="Short Only" and AboveBelow == "Above" and RSIroc == "RSI Only"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Below" and RSIroc == "RSI Only"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Don't Include" and RSIroc == "RSI Only"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Above" and RSIroc == "RSI Only"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Below" and RSIroc == "RSI Only"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Don't Include" and RSIroc == "RSI Only"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

///////-----------------/////////////
///////-----------------/////////////
///////-----------------/////////////


//ROC ONLY
 //Long Side

if LongShort =="Long Only" and AboveBelow == "Above" and RSIroc == "ROC Only"
    strategy.entry("LONG", true, when = roc(close,ROCLength)<ROCLower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Below" and RSIroc == "ROC Only"
    strategy.entry("LONG", true, when = roc(close,ROCLength)<ROCLower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Don't Include" and RSIroc == "ROC Only"
    strategy.entry("LONG", true, when = roc(close,ROCLength)<ROCLower and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Above" and RSIroc == "ROC Only"
    strategy.entry("LONG", true, when = roc(close,ROCLength)<ROCLower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Below" and RSIroc == "ROC Only"
    strategy.entry("LONG", true, when = roc(close,ROCLength)<ROCLower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Don't Include" and RSIroc == "ROC Only"
    strategy.entry("LONG", true, when = rsi(close,ROCLength)<ROCLower and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

//ROC ONLY
 //SHORT SIDE

if LongShort =="Short Only" and AboveBelow == "Above" and RSIroc == "ROC Only"
    strategy.entry("SHORT", false, when = roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Below" and RSIroc == "ROC Only"
    strategy.entry("SHORT", false, when = roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Don't Include" and RSIroc == "ROC Only"
    strategy.entry("SHORT", false, when = roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Above" and RSIroc == "ROC Only"
    strategy.entry("SHORT", false, when = roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Below" and RSIroc == "ROC Only"
    strategy.entry("SHORT", false, when = roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Don't Include" and RSIroc == "ROC Only"
    strategy.entry("SHORT", false, when = roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))


///////-----------------/////////////
///////-----------------/////////////
///////-----------------/////////////


//BOTH
 //Long Side

if LongShort =="Long Only" and AboveBelow == "Above" and RSIroc == "Both"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and roc(close,ROCLength)<ROCLower and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Below" and RSIroc == "Both"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and roc(close,ROCLength)<ROCLower and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Long Only" and AboveBelow == "Don't Include" and RSIroc == "Both"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and roc(close,ROCLength)<ROCLower  and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Above" and RSIroc == "Both"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and roc(close,ROCLength)<ROCLower  and close< sma(close,LongExit) and close>sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Below" and RSIroc == "Both"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and roc(close,ROCLength)<ROCLower  and close< sma(close,LongExit) and close<sma(close,TrendLength))
    strategy.close("LONG", when = close>sma(close,LongExit))

if LongShort =="Both" and AboveBelow == "Don't Include" and RSIroc == "Both"
    strategy.entry("LONG", true, when = rsi(close,RSILength)<RSILower and roc(close,ROCLength)<ROCLower  and close< sma(close,LongExit))
    strategy.close("LONG", when = close>sma(close,LongExit))

//BOTH
 //SHORT SIDE

if LongShort =="Short Only" and AboveBelow == "Above" and RSIroc == "Both"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Below" and RSIroc == "Both"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Short Only" and AboveBelow == "Don't Include" and RSIroc == "Both"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Above" and RSIroc == "Both"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close>sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Below" and RSIroc == "Both"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit) and close<sma(close,TrendLength))
    strategy.close("SHORT", when = close<sma(close,ShortExit))

if LongShort =="Both" and AboveBelow == "Don't Include" and RSIroc == "Both"
    strategy.entry("SHORT", false, when = rsi(close,RSILength)>RSIUpper and roc(close,ROCLength)>ROCUpper and close> sma(close,ShortExit))
    strategy.close("SHORT", when = close<sma(close,ShortExit))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Robust-Dual-Moving-Average-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h