RSI Dynamic Exit Level Momentum Trading Strategy
This strategy is a dynamic exit system based on the Relative Strength Index (RSI), capturing market trends through dynamic entry and exit conditions. The strategy generates trading signals when RSI breaks through…
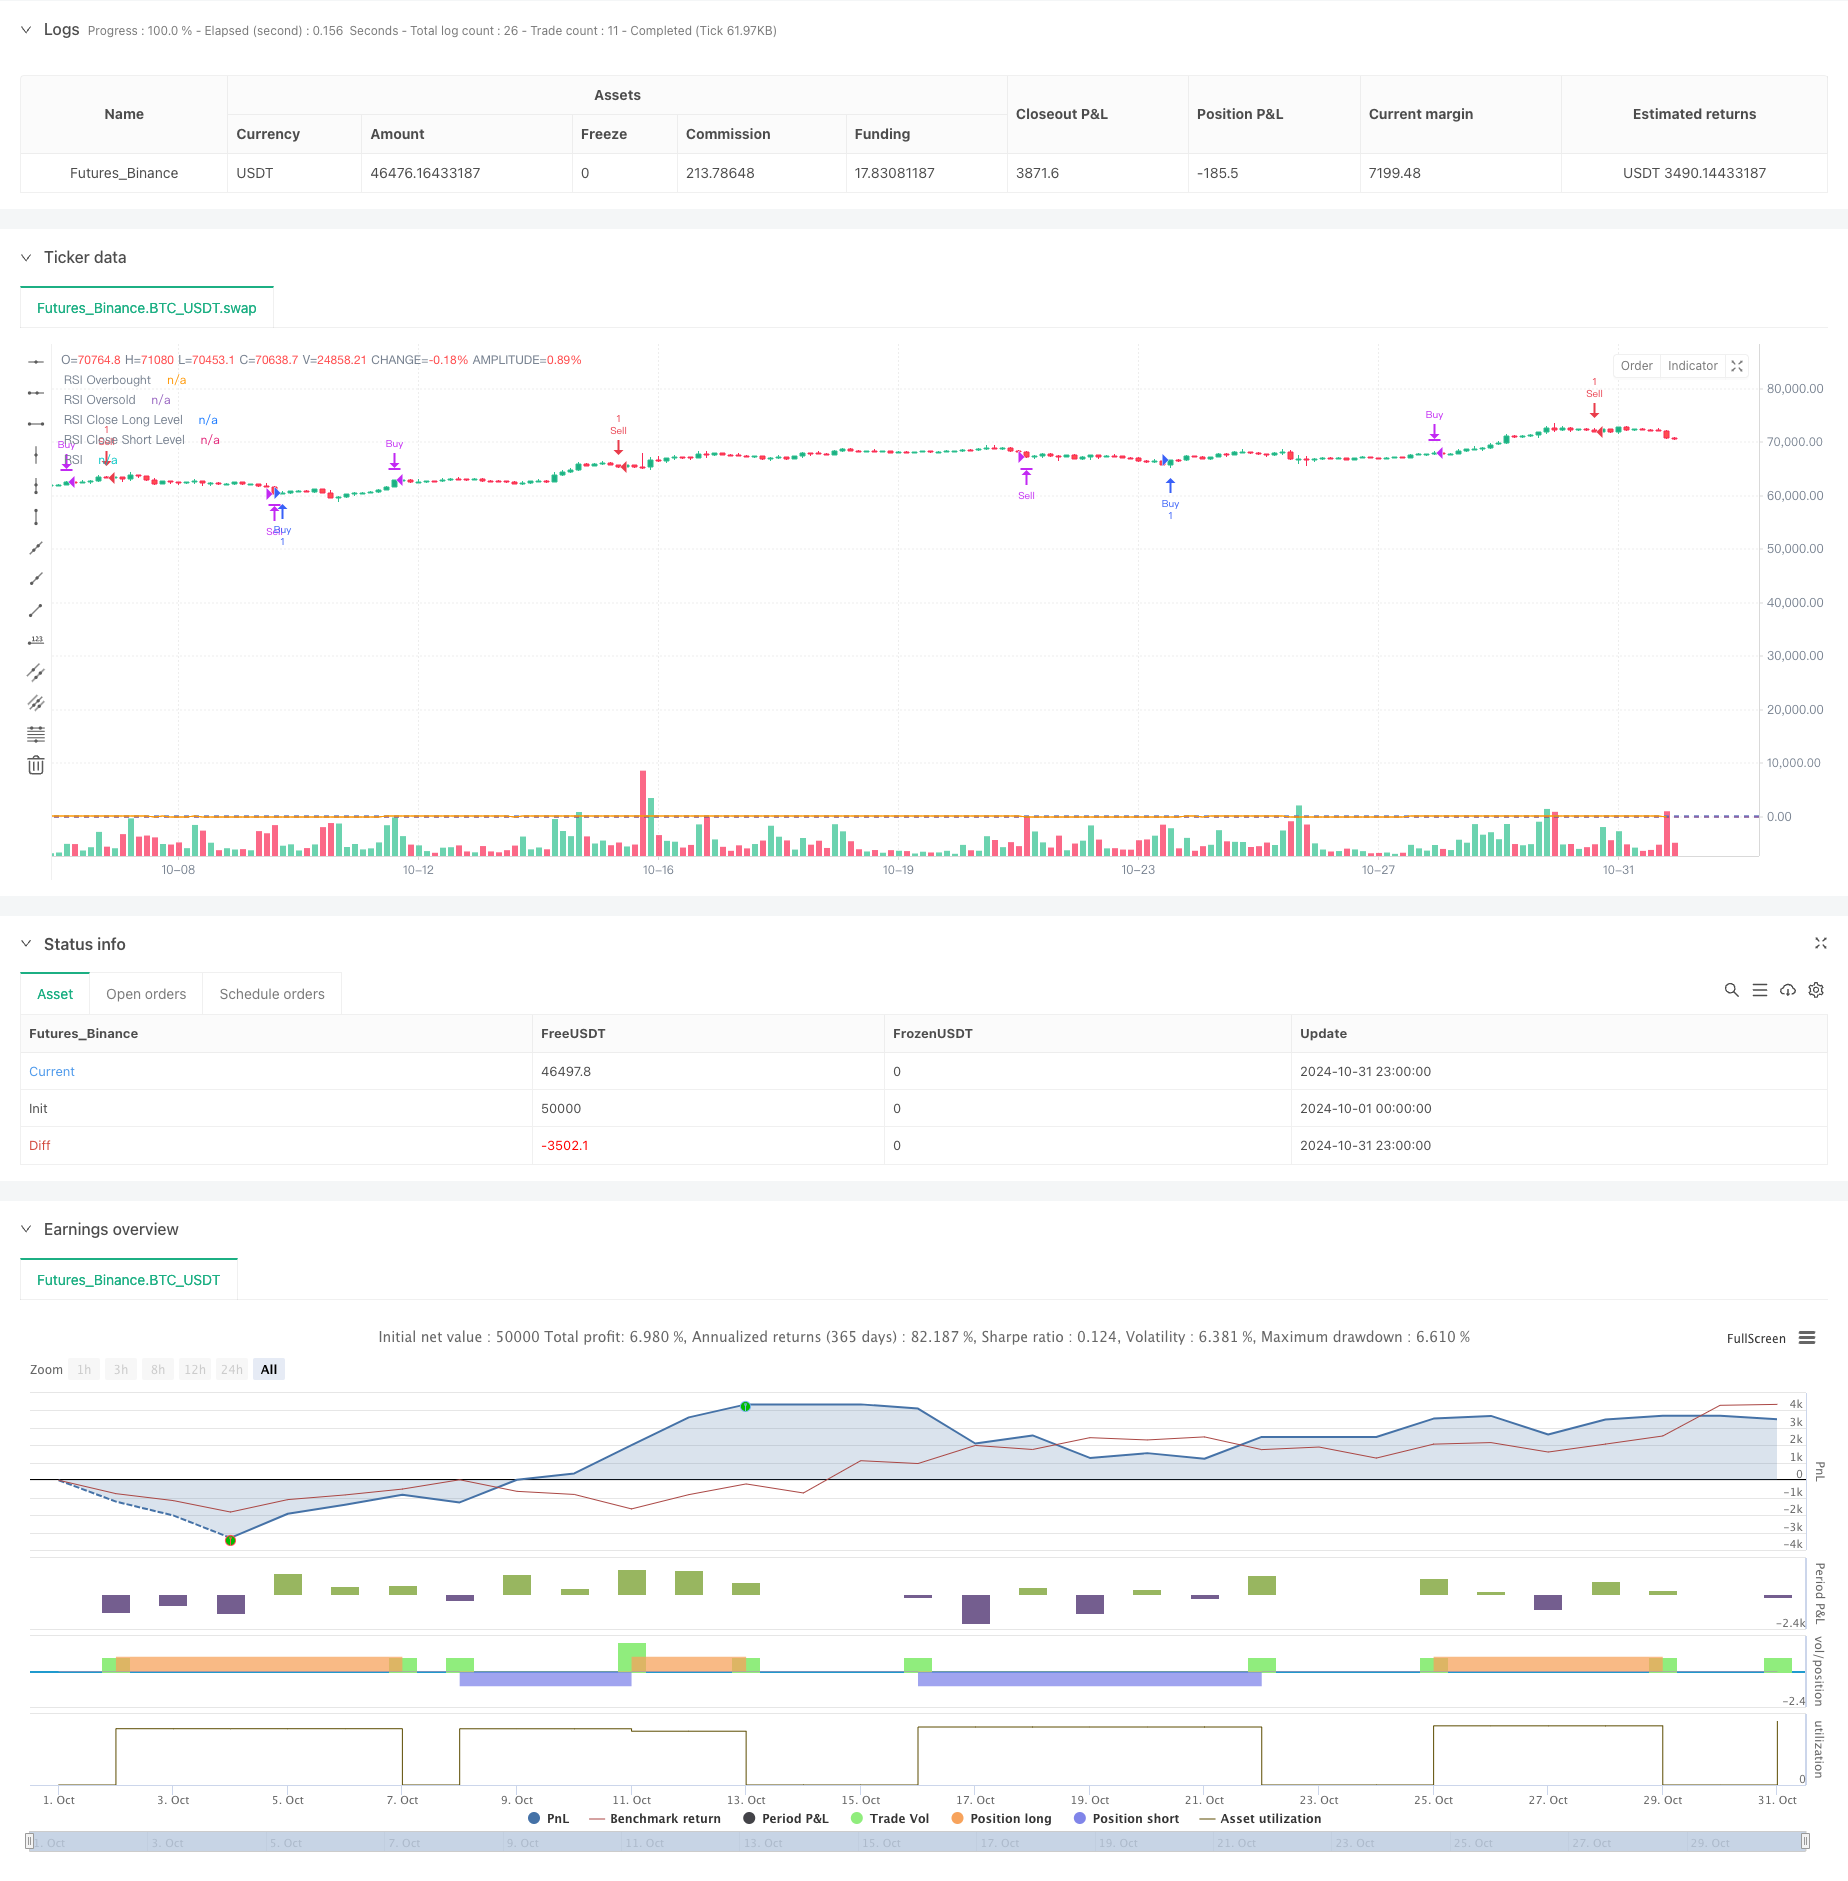
Overview
This strategy is a dynamic exit system based on the Relative Strength Index (RSI), capturing market trends through dynamic entry and exit conditions. The strategy generates trading signals when RSI breaks through overbought and oversold levels, incorporating a unique dynamic exit mechanism by setting exit conditions at different RSI levels to optimize trading performance. It employs a complete long-short trading system capable of capturing opportunities in both market directions.
Strategy Principles
The core logic includes several key components:
- Signal Generation: Uses RSI overbought/oversold levels (70/30) as primary trading signals. Buy signals are generated when RSI crosses above 30, sell signals when crossing below 70.
- Position Management: Implements a single position principle, ensuring only one directional position at any time to effectively control risk exposure.
- Dynamic Exit Mechanism: Sets differentiated RSI exit levels (60 for longs/40 for shorts), with this asymmetric design better adapting to market trend characteristics.
- Visualization Module: Plots RSI line, overbought/oversold levels, and exit levels on the chart for intuitive market state understanding.
Strategy Advantages
- Systematic Trading: Fully systematic approach eliminates emotional interference from subjective judgment.
- Risk Control: Effective risk management through single position principle and dynamic exit mechanism.
- High Adaptability: RSI parameters and exit levels can be adjusted for different market characteristics.
- Bilateral Trading: Captures opportunities in both rising and falling markets.
- Visual Support: Intuitive chart display aids understanding of market conditions and strategy logic.
Strategy Risks
- Choppy Market Risk: May generate frequent trades in sideways markets, increasing transaction costs.
- Trend Continuation Risk: Early exits might miss larger trend opportunities.
- Parameter Sensitivity: Strategy performance is sensitive to RSI parameter and exit level settings.
- Slippage Impact: May face significant slippage risk during volatile market conditions.
Optimization Directions
- Introduce Trend Filters: Add trend indicators like moving averages to filter false signals.
- Dynamic Parameter Optimization: Automatically adjust RSI parameters and exit levels based on market volatility.
- Enhanced Position Management: Incorporate money management module to adjust position size based on market risk levels.
- Optimize Exit Mechanism: Consider adding trailing stop functionality for better profit protection.
Summary
This is a well-designed momentum trading strategy that captures market opportunities through RSI indicators and dynamic exit mechanisms. The strategy's main features are its high systematic nature, robust risk control, and strong adaptability. While inherent risks exist, there is significant room for improvement through parameter optimization and functional extensions. For investors seeking a robust trading system, this represents a worthy strategy framework to consider.
Source Pine Script
/*backtest
start: 2024-10-01 00:00:00
end: 2024-10-31 23:59:59
period: 3h
basePeriod: 3h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("RSI Strategy with Close Levels", shorttitle="RSI Strat", overlay=true)

// RSI Input settings
rsiLength = input.int(14, title="RSI Length")
rsiOverbought = input.int(70, title="RSI Overbought Level")
rsiOversold = input.int(30, title="RSI Oversold Level")
rsiCloseLongLevel = input.int(60, title="RSI Level to Close Long Position")
rsiCloseShortLevel = input.int(40, title="RSI Level to Close Short Position")

// Calculate RSI
rsi = ta.rsi(close, rsiLength)

// Generate buy and sell signals based on RSI levels
buySignal = ta.crossover(rsi, rsiOversold)
sellSignal = ta.crossunder(rsi, rsiOverbought)

// Check if there are open positions
var bool inPosition = na
if (strategy.opentrades > 0)
    inPosition := true
else
    inPosition := false

// Open long position on buy signal if not already in a position
if (buySignal and not inPosition)
    strategy.entry("Buy", strategy.long)
    inPosition := true

// Close long position on sell signal or when RSI reaches the close long level
if (inPosition and strategy.position_size > 0 and (sellSignal or rsi >= rsiCloseLongLevel))
    strategy.close("Buy")
    inPosition := false

// Open short position on sell signal if not already in a position
if (sellSignal and not inPosition)
    strategy.entry("Sell", strategy.short)
    inPosition := true

// Close short position on buy signal or when RSI reaches the close short level
if (inPosition and strategy.position_size < 0 and (buySignal or rsi <= rsiCloseShortLevel))
    strategy.close("Sell")
    inPosition := false

// Plot buy and sell signals
//plotshape(series=buySignal, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
//plotshape(series=sellSignal, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")

// Plot RSI for visualization
hline(rsiOverbought, "RSI Overbought", color=color.red)
hline(rsiOversold, "RSI Oversold", color=color.green)
hline(rsiCloseLongLevel, "RSI Close Long Level", color=color.blue)
hline(rsiCloseShortLevel, "RSI Close Short Level", color=color.purple)
plot(rsi, title="RSI", color=color.orange)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Dynamic-Exit-Level-Momentum-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Cross Momentum Trend Following Strategy SMA RSI Cross Momentum SystemPine Script · Momentum · 1h
- Cross Period Momentum EMA Strategy with RSI and Dynamic ATR Stop LossPine Script · Momentum · 1d
- Dual EMA Crossover with RSI Momentum Enhanced Trading StrategyPine Script · Momentum · 1d