RSI Momentum based Smart Adaptive Trading System with Multi level Risk Management
This strategy is an adaptive trading system based on the Relative Strength Index (RSI), designed to capture market momentum changes by monitoring RSI's overbought and oversold zones. The system integrates intelligent…
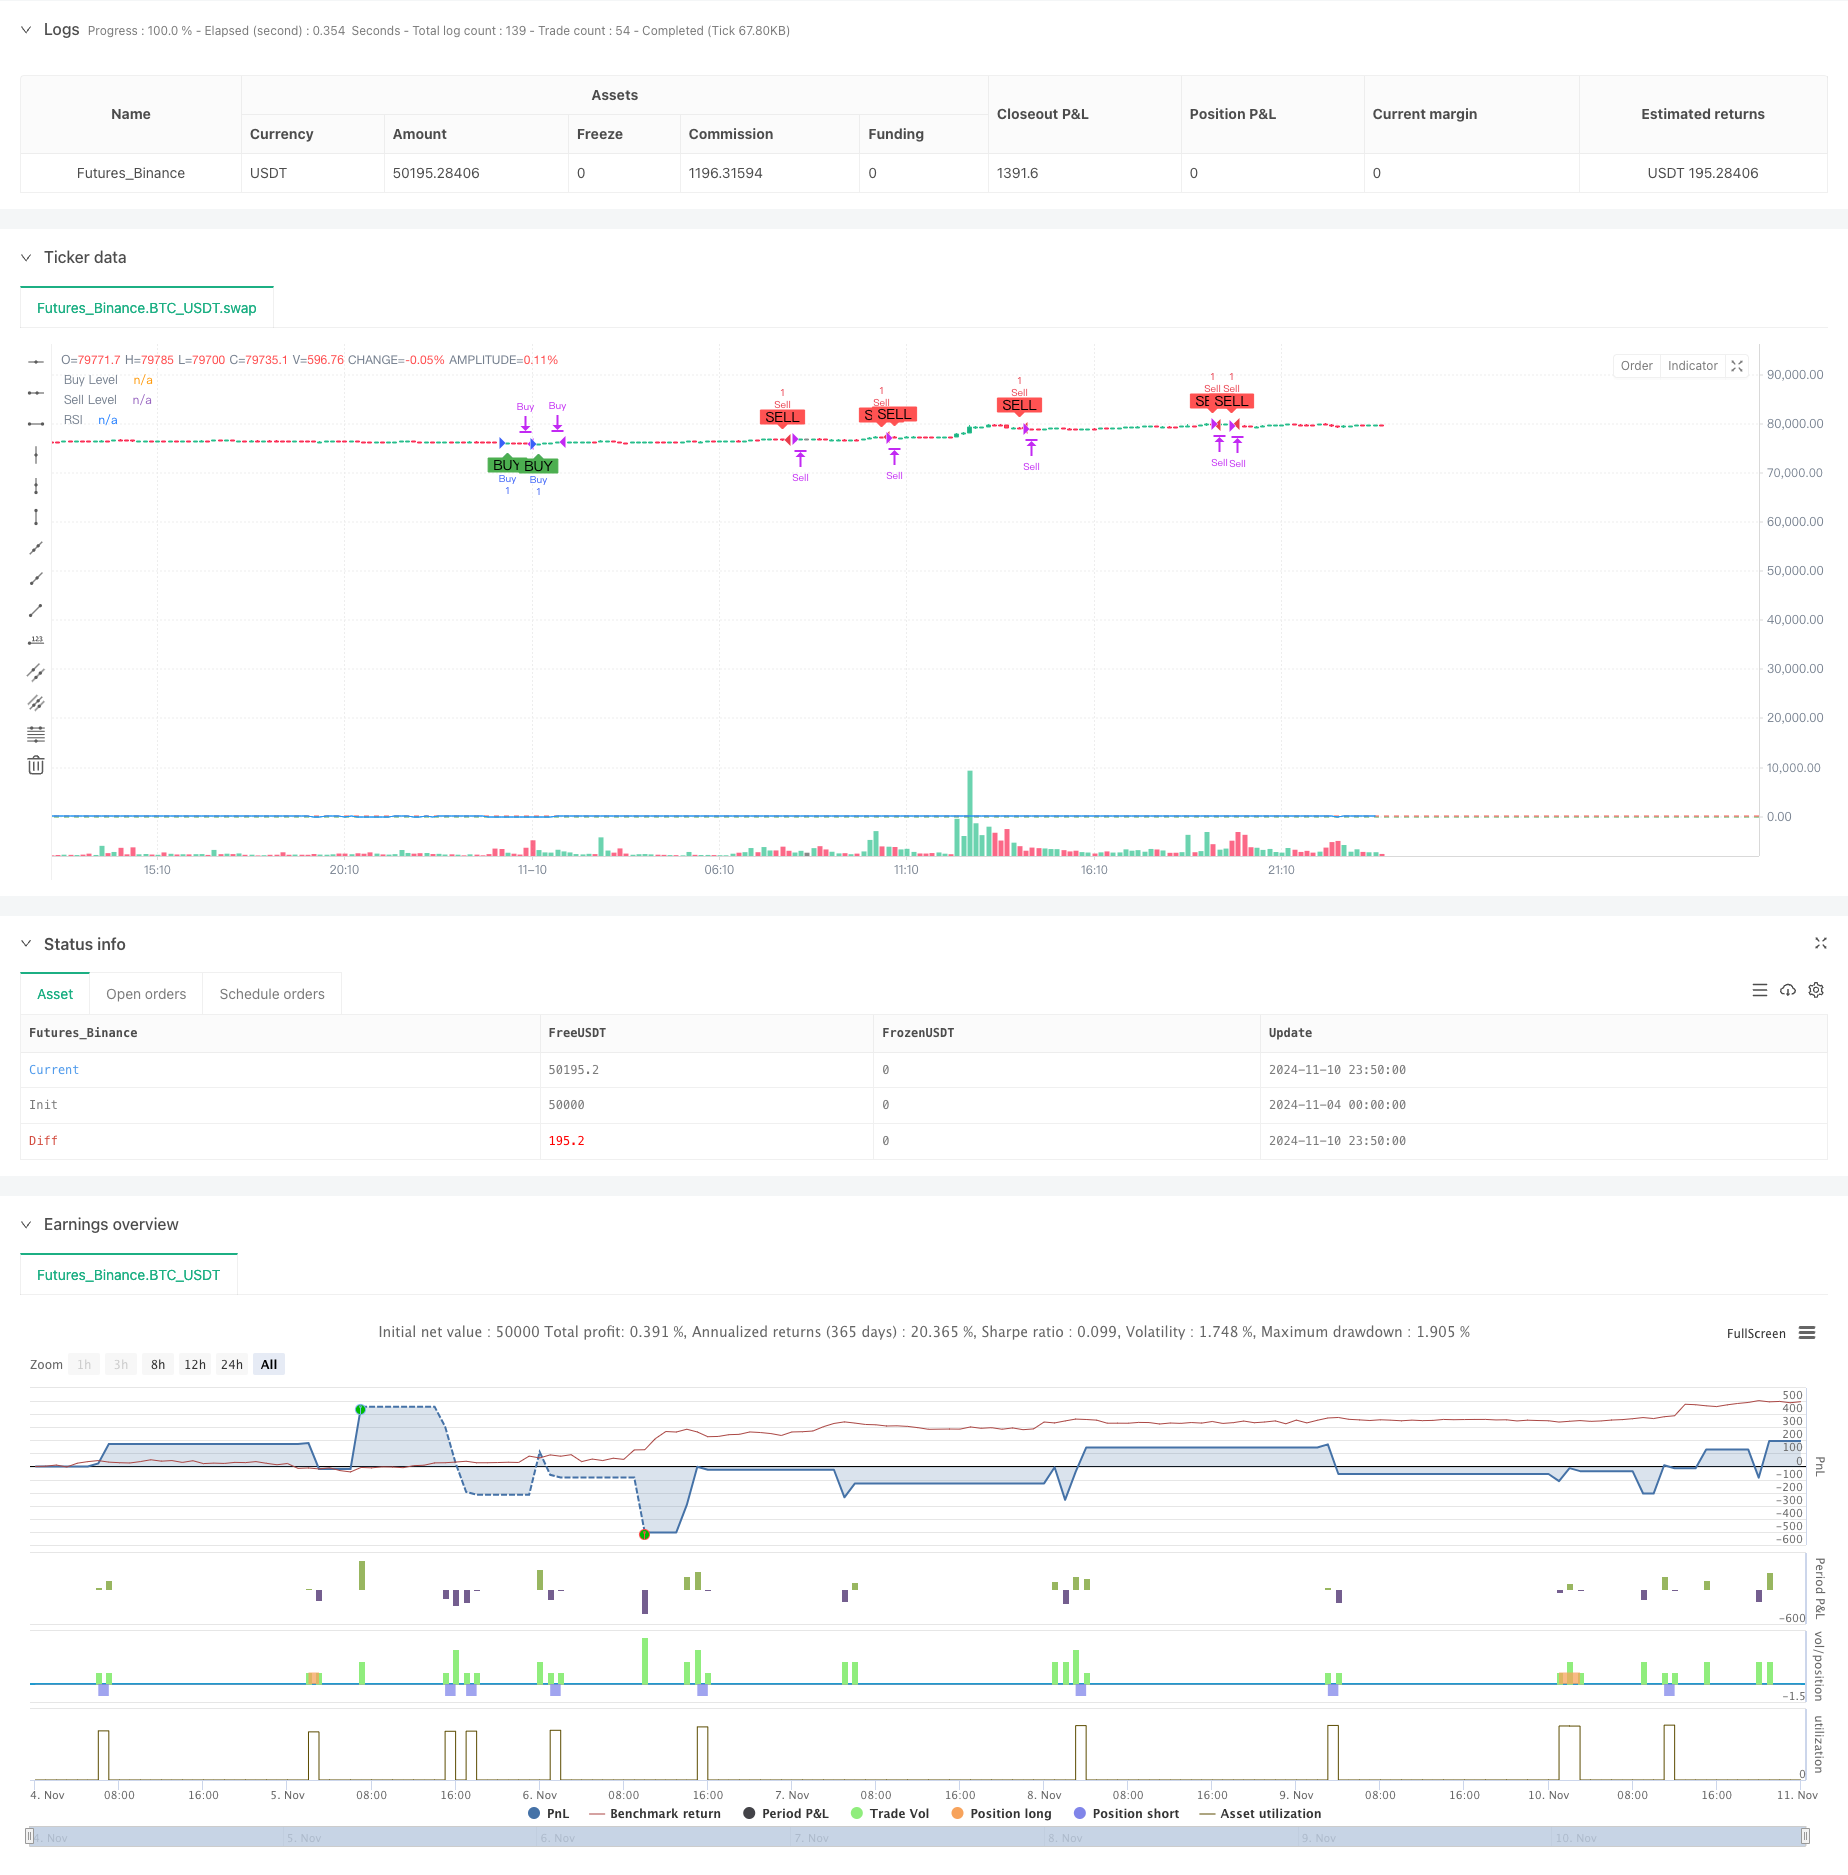
Overview
This strategy is an adaptive trading system based on the Relative Strength Index (RSI), designed to capture market momentum changes by monitoring RSI's overbought and oversold zones. The system integrates intelligent position management mechanisms, including multi-level stop-loss and take-profit controls, as well as automatic position closing functionality, aiming to achieve a robust risk-reward ratio.
Strategy Principles
The core strategy is based on RSI overbought/oversold signals, combined with multiple trading conditions:
- Entry signals: Generate long signals when RSI breaks above 30; generate short signals when RSI falls below 70
- Risk Management:
- Set fixed stop-loss (100 points loss) and profit target (150 points gain)
- Real-time position tracking ensuring one-directional positions
- Automatic position closing at 15:25 daily to avoid overnight risk
- Trade Execution: System automatically executes trading orders through strategy.entry and strategy.close functions
Strategy Advantages
- Clear Signals: RSI-based crossover signals are clear, easy to understand and execute
- Comprehensive Risk Control: Integrated multi-level risk control mechanisms
- High Automation: Fully automated from signal generation to trade execution
- Good Visualization: Clear display of buy/sell signals and RSI levels on charts
- High Adaptability: Parameters can be adjusted for different market characteristics
Strategy Risks
- RSI signal lag may cause delayed entry timing
- Fixed stop-loss and take-profit levels may not suit all market conditions
- Single indicator dependency might miss other important market signals
- Frequent trading may incur high transaction costs Suggestions:
- Combine with other technical indicators for signal confirmation
- Dynamically adjust stop-loss and take-profit levels
- Add trading frequency limitations
Strategy Optimization Directions
- Indicator Optimization:
- Add moving averages and other trend indicators
- Include volume indicators for signal confirmation
- Risk Control Optimization:
- Implement dynamic stop-loss and take-profit
- Add maximum drawdown control
- Execution Optimization:
- Add position size management
- Optimize trading time management
- Parameter Optimization:
- Develop adaptive parameter system
- Implement dynamic RSI thresholds
Summary
The strategy captures market momentum changes through the RSI indicator, coupled with a comprehensive risk management system, achieving a fully automated trading system. While certain limitations exist, improvements through the suggested optimization directions could lead to more stable trading performance. The core advantages lie in the system's completeness and automation level, making it suitable as a basic framework for further development and optimization.
Source Pine Script
/*backtest
start: 2024-11-04 00:00:00
end: 2024-11-11 00:00:00
period: 10m
basePeriod: 10m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Harmony Signal Flow By Arun", overlay=true)

// RSI settings
rsiLength = 14
rsiSource = close
rsiValue = ta.rsi(rsiSource, rsiLength)

// Define RSI levels
buyLevel = 30
sellLevel = 70

// Buy signal: RSI crosses above 30
buyCondition = ta.crossover(rsiValue, buyLevel)

// Sell signal: RSI crosses below 70
sellCondition = ta.crossunder(rsiValue, sellLevel)

// Ensure only one order at a time
if (strategy.position_size == 0) // No open positions
    if (buyCondition)
        strategy.entry("Buy", strategy.long)
    else if (sellCondition)
        strategy.entry("Sell", strategy.short)

// Stop-loss and target conditions
var float stopLossBuy = na
var float targetBuy = na
var float stopLossSell = na
var float targetSell = na

if (strategy.position_size > 0) // If there's an open buy position
    stopLossBuy := strategy.position_avg_price - 100 // Set stop-loss for buy
    targetBuy := strategy.position_avg_price + 150 // Set target for buy

    if (close <= stopLossBuy)
        strategy.close("Buy", comment="Stoploss Hit")
    else if (close >= targetBuy)
        strategy.close("Buy", comment="Target Hit")

if (strategy.position_size < 0) // If there's an open sell position
    stopLossSell := strategy.position_avg_price + 100 // Set stop-loss for sell
    targetSell := strategy.position_avg_price - 150 // Set target for sell

    if (close >= stopLossSell)
        strategy.close("Sell", comment="Stoploss Hit")
    else if (close <= targetSell)
        strategy.close("Sell", comment="Target Hit")

// Close all positions by 3:25 PM
if (hour(timenow) == 15 and minute(timenow) == 25)
    strategy.close_all(comment="Close all positions at 3:25 PM")

// Plot buy/sell signals on the chart
plotshape(buyCondition, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
plotshape(sellCondition, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")

// Plot RSI and levels
hline(buyLevel, "Buy Level", color=color.green)
hline(sellLevel, "Sell Level", color=color.red)
plot(rsiValue, "RSI", color=color.blue)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/RSI-Momentum-based-Smart-Adaptive-Trading-System-with-Multi-level-Risk-Management.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Cross Momentum Trend Following Strategy SMA RSI Cross Momentum SystemPine Script · Momentum · 1h
- Cross Period Momentum EMA Strategy with RSI and Dynamic ATR Stop LossPine Script · Momentum · 1d
- Dual EMA Crossover with RSI Momentum Enhanced Trading StrategyPine Script · Momentum · 1d