Strategy vault / Trend following
SuperTrend Strategy
This strategy uses the Supertrend indicator to determine price trends and enters long or short positions when the trends change. The strategy allows adjusting the ATR period and multiplier to optimize parameters. It…
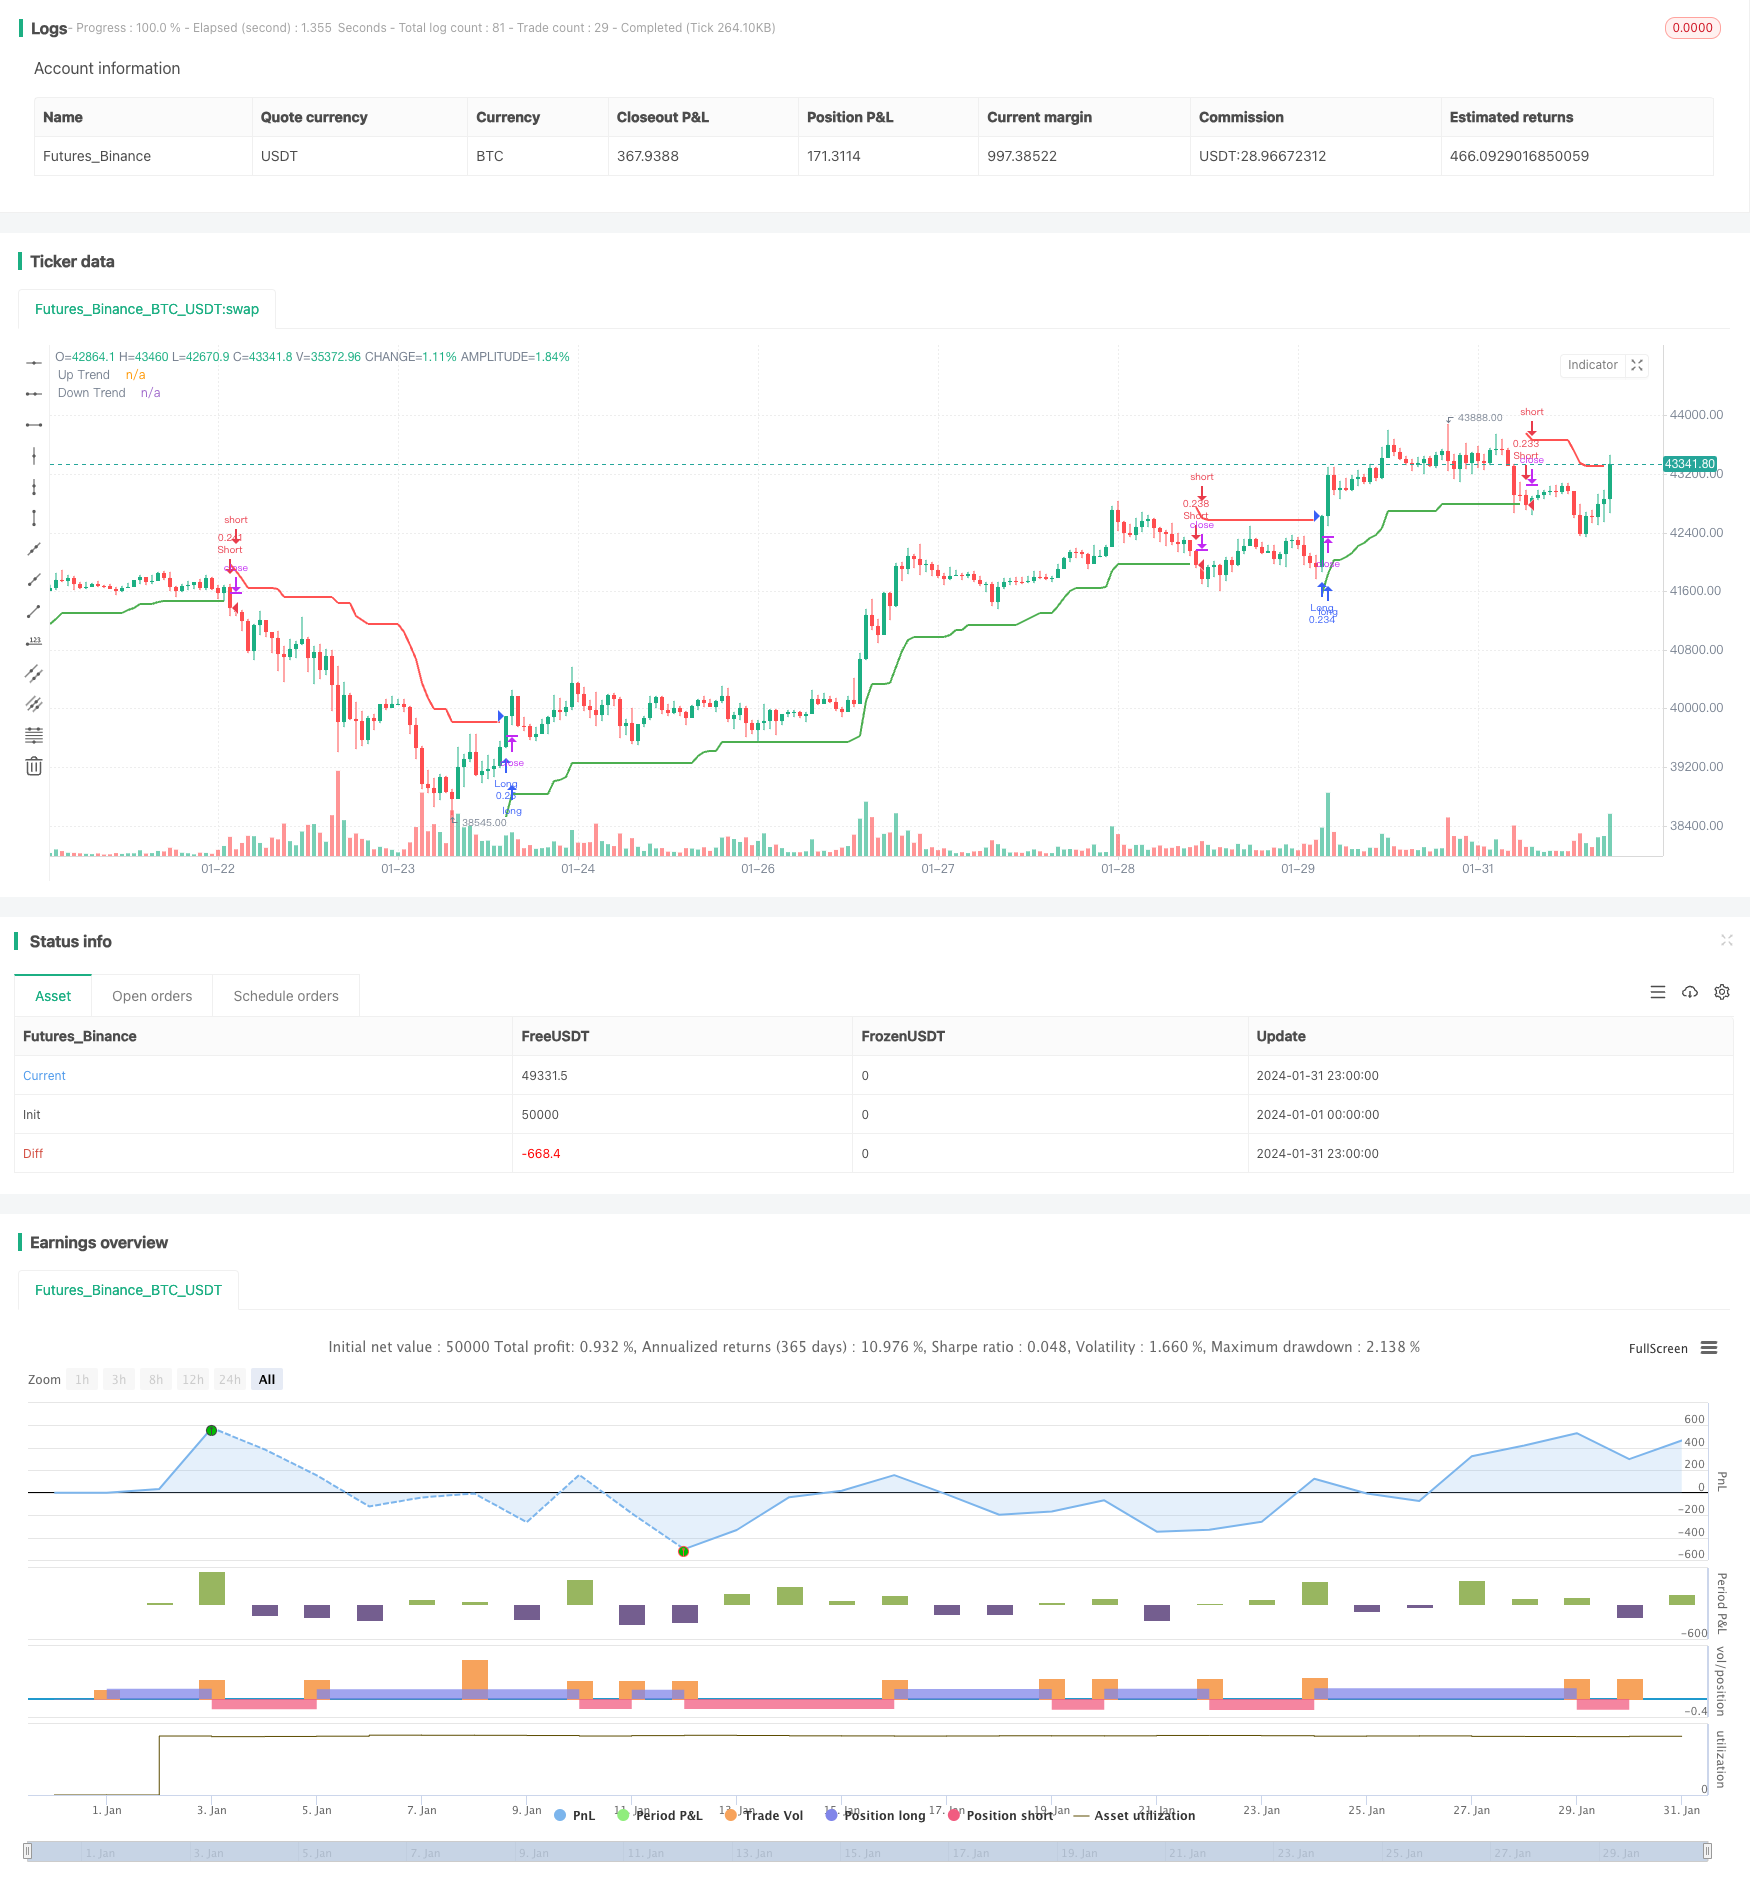
Overview
This strategy uses the Supertrend indicator to determine price trends and enters long or short positions when the trends change. The strategy allows adjusting the ATR period and multiplier to optimize parameters. It also provides the option to change the ATR calculation method for slightly different results.
The strategy has built-in backtesting date ranges and the ability to trade only within certain times of the day and close all trades at the end of that timeframe. This is especially useful for day trading stocks. When the timeframe option is enabled, you can choose to enter the current position immediately when the timeframe starts, or wait for a trend change to enter the first position.
The strategy also allows you to specify percentage based stop loss and take profit levels. In most cases, the ATR based stop provided by Supertrend itself makes an additional stop loss unnecessary. So you could enable only take profit to optimize the exit mechanism.
Finally, there are custom alert fields for entry and exit messages to be used with automated trading services.
Strategy Logic
The Supertrend strategy is based on the following key principles:
Calculate the ATR value: Can choose between SMA calculation or built-in ATR indicator. SMA formula:
atr2 = sma(tr, Periods)Calculate upper and lower bands. Upper band is close minus ATR multiplier times ATR. Lower band is close plus multiplier times ATR.
up = close - (Multiplier * atr)
dn = close + (Multiplier * atr)
Determine trend direction by comparing price to bands. Uptrend when price crosses above lower band. Downtrend when price crosses below upper band.
trend := trend == -1 and close > dn ? 1 : trend == 1 and close < up ? -1 : trendGenerate trading signals on trend change, e.g. sell signal when changing from uptrend to downtrend:
sellSignal = trend == -1 and trend[1] == 1Filter entry based on signals and additional conditions.
Use stop loss and take profit to lock in profits or limit risks.
These are the key working principles behind the Supertrend strategy. Combined with parameter optimization, it can produce good trading results.
Advantages
The Supertrend strategy has several advantages:
Supertrend itself effectively identifies trends and is commonly used for trailing stops.
Customizable ATR parameters can be optimized across products for best fit. SMA calculation provides another option.
Configurable backtest and live trading time ranges suit different trading sessions.
Option to enter first trade immediately or wait for signal caters to different products.
Built-in stop loss and take profit helps improve risk management or lock in more profits.
Customizable trade alerts for integration with automated trading systems and bots.
Risks
There are also some risks to consider:
Supertrend can produce false signals which need to be filtered with additional conditions.
Improper ATR parameters may lead to over-trading or missing trends. Requires optimization for best balance.
Stop loss too close may prematurely exit profitable trades. Take profit too loose may leave money on the table.
Poor timeframe configuration can miss trading sessions or tie up margin unnecessarily.
These risks can be addressed through appropriate adjustments to parameters or additional filters to improve robustness.
Optimization Opportunities
Some ways the strategy can be further optimized:
Test different ATR periods to find the right balance, typically 10-20 works well.
Try different ATR multiplier values, generally 2-5 is appropriate, adjust to find optimum.
Add filters like MACD, RSI etc. to reduce false signals.
Optimize stop loss and take profit levels for best results. Consider dynamic trailing mechanisms.
Test different trading time ranges. Shorter durations suit intraday and high frequency strategies.
Implement auto symbol selection to track high momentum or volatility.
Conclusion
Overall this is a fairly common and practical trend following strategy. It efficiently tracks trends with customizable parameters, but also has inherent risks to manage. With optimization and additional conditions, it can be refined into a robust quant trading system with consistent alpha.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | ATR Period |
| v_input_2_hl2 | 0 | Source: hl2 | high | low | open | close | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | 3 | ATR Multiplier |
| v_input_4 | true | Change ATR Calculation Method ? |
| v_input_5 | true | Enter First Trade ASAP |
| v_input_6 | false | Wait To Enter First Trade |
| v_input_7 | timestamp(2021-01-01T00:00:00) | Backtesting Start Date |
| v_input_8 | timestamp(2021-12-31T00:00:00) | Backtesting End Date |
| v_input_9 | Time Frame To Enter Trades | |
| v_input_10 | false | Enable Close Trade At End Of Time Frame |
| v_input_11 | false | Enable Stop Loss |
| v_input_12 | false | Enable Take Profit |
| v_input_13 | 5 | Stop Loss % |
| v_input_14 | 10 | Take Profit % |
| v_input_15 | Long Entry message | |
| v_input_16 | Short Entry message | |
| v_input_17 | Close Long message | |
| v_input_18 | Close Short message |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © REV0LUTI0N

//@version=4

// Strategy
strategy("Supertrend Strategy", overlay=true, initial_capital = 10000, default_qty_value = 10000, default_qty_type = strategy.cash)
Periods = input(title="ATR Period", type=input.integer, defval=10)
src = input(hl2, title="Source")
Multiplier = input(title="ATR Multiplier", type=input.float, step=0.1, defval=3.0)
changeATR= input(title="Change ATR Calculation Method ?", type=input.bool, defval=true)
enableentry = input(true, title="Enter First Trade ASAP")
waitentry = input(false, title="Wait To Enter First Trade")

atr2 = sma(tr, Periods)
atr= changeATR ? atr(Periods) : atr2
up=src-(Multiplier*atr)
up1 = nz(up[1],up)
up := close[1] > up1 ? max(up,up1) : up
dn=src+(Multiplier*atr)
dn1 = nz(dn[1], dn)
dn := close[1] < dn1 ? min(dn, dn1) : dn
trend = 1
trend := nz(trend[1], trend)
trend := trend == -1 and close > dn1 ? 1 : trend == 1 and close < up1 ? -1 : trend

upPlot = plot(trend == 1 ? up : na, title="Up Trend", style=plot.style_linebr, linewidth=2, color=color.green)
Long = (trend == 1 ? up : na)
buySignal = trend == 1 and trend[1] == -1

dnPlot = plot(trend == 1 ? na : dn, title="Down Trend", style=plot.style_linebr, linewidth=2, color=color.red)
Short = (trend == 1 ? na : dn)
sellSignal = trend == -1 and trend[1] == 1

// Strategy Backtesting
startDate  = input(timestamp("2021-01-01T00:00:00"), type = input.time, title='Backtesting Start Date')
finishDate = input(timestamp("2021-12-31T00:00:00"), type = input.time, title='Backtesting End Date')

time_cond  = true

//Time Restriction Settings
startendtime = input("", title='Time Frame To Enter Trades')
enableclose = input(false, title='Enable Close Trade At End Of Time Frame')
timetobuy = (time(timeframe.period, startendtime))
timetoclose = na(time(timeframe.period, startendtime))

// Stop Loss & Take Profit % Based
enablesl = input(false, title='Enable Stop Loss')
enabletp = input(false, title='Enable Take Profit')
stopTick = input(5.0, title='Stop Loss %', type=input.float, step=0.1) / 100
takeTick = input(10.0, title='Take Profit %', type=input.float, step=0.1) / 100

longStop = strategy.position_avg_price * (1 - stopTick)
shortStop = strategy.position_avg_price * (1 + stopTick)
shortTake = strategy.position_avg_price * (1 - takeTick)
longTake = strategy.position_avg_price * (1 + takeTick)

plot(strategy.position_size > 0 and enablesl ? longStop : na, style=plot.style_linebr, color=color.red, linewidth=1, title="Long Fixed SL")
plot(strategy.position_size < 0 and enablesl ? shortStop : na, style=plot.style_linebr, color=color.red, linewidth=1, title="Short Fixed SL")
plot(strategy.position_size > 0 and enabletp ? longTake : na, style=plot.style_linebr, color=color.green, linewidth=1, title="Long Take Profit")
plot(strategy.position_size < 0 and enabletp ? shortTake : na, style=plot.style_linebr, color=color.green, linewidth=1, title="Short Take Profit")

// Alert messages
message_enterlong  = input("", title="Long Entry message")
message_entershort = input("", title="Short Entry message")
message_closelong = input("", title="Close Long message")
message_closeshort = input("", title="Close Short message")

// Strategy Execution
if Long and time_cond and timetobuy and enableentry
    strategy.entry("Long", strategy.long, alert_message = message_enterlong)

if Short and time_cond and timetobuy and enableentry
    strategy.entry("Short", strategy.short, alert_message = message_entershort)

if buySignal and time_cond and timetobuy and waitentry
    strategy.entry("Long", strategy.long, alert_message = message_enterlong)

if sellSignal and time_cond and timetobuy and waitentry
    strategy.entry("Short", strategy.short, alert_message = message_entershort)

if strategy.position_size > 0 and timetoclose and enableclose
    strategy.close_all(alert_message = message_closelong)
if strategy.position_size < 0 and timetoclose and enableclose
    strategy.close_all(alert_message = message_closeshort)

if strategy.position_size > 0 and enablesl and time_cond
    strategy.exit(id="Close Long", stop=longStop, limit=longTake, alert_message = message_closelong)
if strategy.position_size < 0 and enablesl and time_cond
    strategy.exit(id="Close Short", stop=shortStop, limit=shortTake, alert_message = message_closeshort)

if strategy.position_size > 0 and enabletp and time_cond
    strategy.exit(id="Close Long", stop=longStop, limit=longTake, alert_message = message_closelong)
if strategy.position_size < 0 and enabletp and time_cond
    strategy.exit(id="Close Short", stop=shortStop, limit=shortTake, alert_message = message_closeshort)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/SuperTrend-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Super trend BPine Script · Trend following · 4h
- SuperTrend Dual Direction StrategyPine Script · Trend following · 3d
- Supertrend Advance StrategyPine Script · Trend following · 5m
- Supertrend and Moving Average Crossover StrategyPine Script · Trend following · 2h
- Trading the Equity Curve Position Sizing ExamplePine Script · Trend following · 15m