Support and Resistance Strategy with Volume Breakout and Trailing Stop Loss
The main idea of this strategy is to combine support/resistance levels and volume breakouts to determine entry signals, and use the ATR indicator to dynamically adjust stop loss for profit taking, in order to capture…
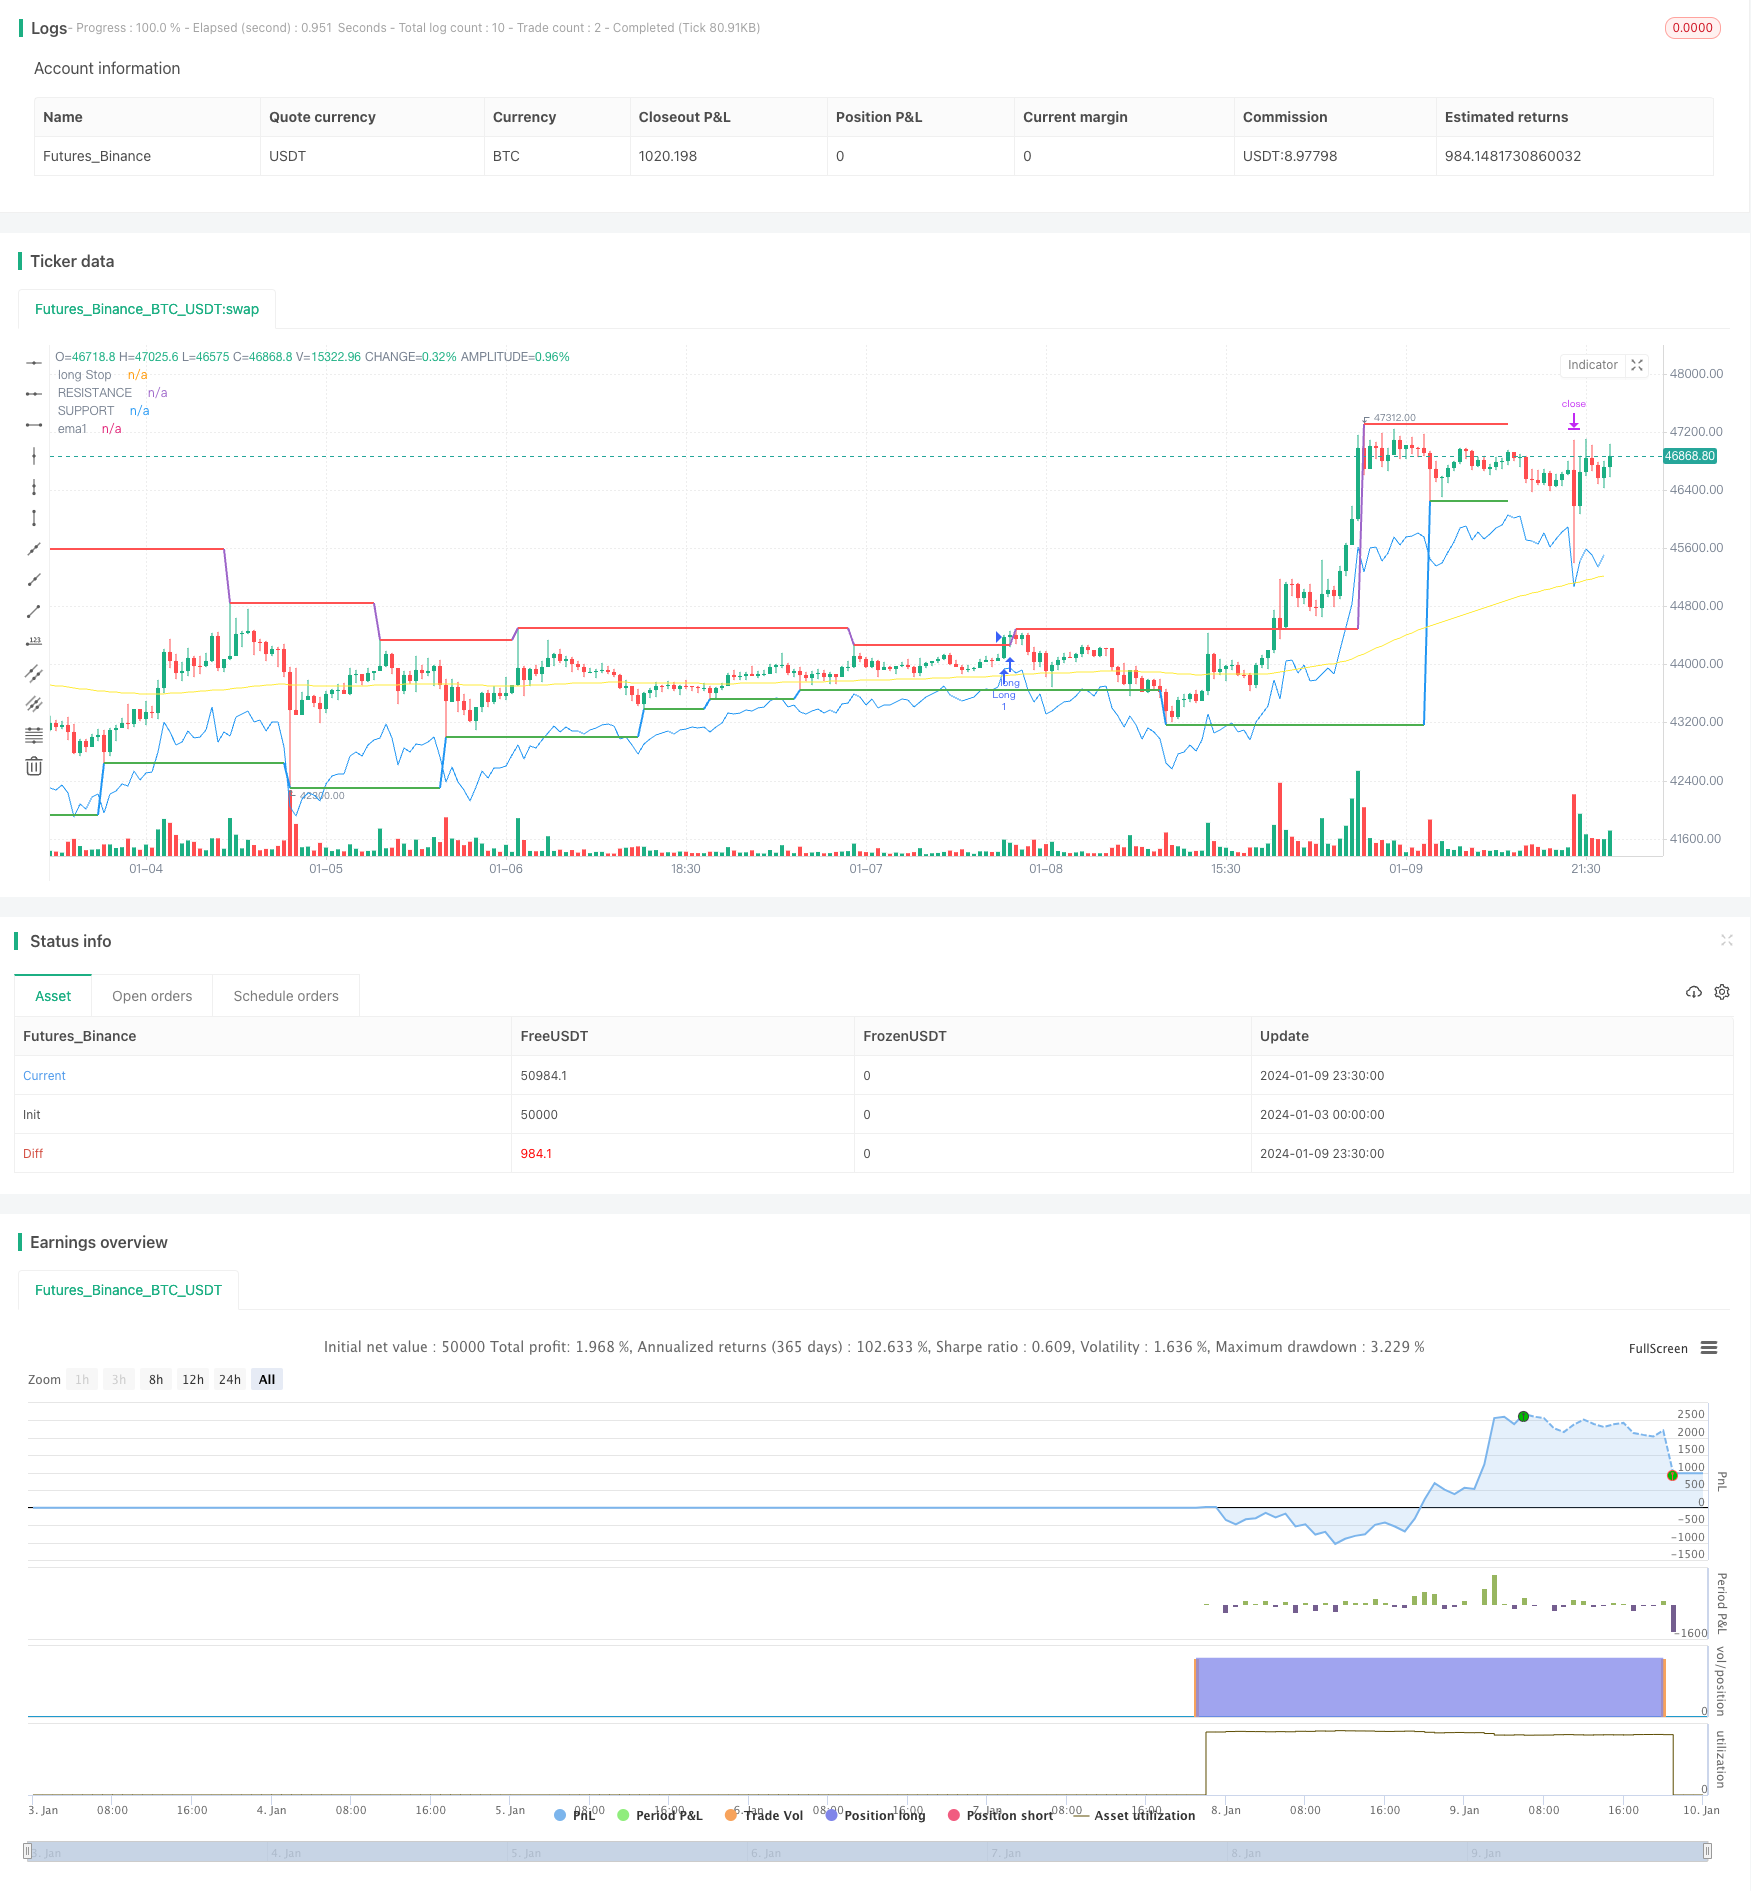
Overview
The main idea of this strategy is to combine support/resistance levels and volume breakouts to determine entry signals, and use the ATR indicator to dynamically adjust stop loss for profit taking, in order to capture more potential profits.
Strategy Logic
The strategy consists of the following main logics:
Use ta.pivothigh and ta.pivotlow to calculate the highest price of previous L_Bars candles and the lowest price of previous R_Bars candles, as resistance and support levels.
When close price crosses above resistance level and volume breaks above the volumeRange threshold, go long. When close price crosses below support level and volume breaks above the volumeRange threshold, go short.
After long entry, set stop loss at close-ATR_LO. After short entry, set stop loss at close+ATR_SH. This realizes dynamic trailing stop loss adjustment.
Only take the first signal within trading hours (0915-1445) each day. No new orders after reaching the daily risk limit defined by risk input.
Advantage Analysis
Use support/resistance theory combined with volume indicator to improve entry accuracy.
Trailing stop loss based on ATR can flexibly adjust stop level based on market volatility, lowering the chance of profit retracement.
Appropriate control over daily trade times and per trade risk helps to catch the trend and avoid excessive stop loss.
Risk Analysis
Support/resistance levels may fail and unable to provide effective entry signals.
ATR multiplier set too high may lead to stop loss being too far away, increasing loss risk.
Volume threshold set too low may miss opportunities, too high may cause false signals.
Solutions:
Adjust support/resistance parameters based on different products' characteristics.
Optimize ATR multiplier and volume threshold parameters.
Add other indicators to confirm entry signals.
Optimization Directions
Add other indicators like moving averages to assist in determining entry signals.
Optimize parameters like ATR multiplier and volume threshold.
Use machine learning algorithms to realize dynamic parameter optimization.
Expand strategy to other products to find parameter patterns.
Summary
The strategy integrates various analytical tools, applying support/resistance, volume, and stop loss methods, and achieved good backtest results. But more uncertainties may exist in live trading, requiring further enhancements like parameter optimization and additional entry confirmation indicators to improve real-world performance. Overall, the strategy has clear logic and easy understanding, providing a good reference case for quantitative trading strategies.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 10 | L_Bars |
| v_input_int_2 | 15 | R_Bars |
| v_input_int_3 | 20 | Volume Break [threshold] |
| v_input_int_4 | 150 | PRICE CROSS EMA |
| v_input_float_1 | 3.2 | _ATR LONG |
| v_input_float_2 | 3.2 | _ATR SHORT |
| v_input_float_3 | 200 | RISK |
Source Pine Script
/*backtest
start: 2024-01-03 00:00:00
end: 2024-01-10 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//   ____________                _________                      _____________
//  |____________|             ||________|                      ||__________|
//       ||            ____    ||        ||                     ||                    ______ ________    _____ ________
//       ||    |   || ||       ||________|| |   || ||    ||     ||     |   ||   /\\   |   // |______| || ||    |______|
//       ||    |===|| |===     ||__________ |   || ||    ||     ||     |===||  /__\\  |===      ||    ||   \\     ||
//       ||    |   || ||___    ||        || |___|| ||___ ||___  ||     |   || /    \\ |   \\    ||    || ___||    ||
//       ||                    ||________||                     ||__________
//       ||                    ||________|                      ||__________|

//@version=5
strategy("SUPPORT RESISTANCE STRATEGY [5MIN TF]",overlay=true )
L_Bars = input.int(defval = 10, minval = 1 , maxval = 50, step =1)
R_Bars = input.int(defval = 15, minval = 1 , maxval = 50, step =1)
volumeRange = input.int(20, title='Volume Break [threshold]', minval = 1)

// ═══════════════════════════ //
// ----------> INPUT <------- //
// ═══════════════════════════ //

EMA1 = input.int(title='PRICE CROSS EMA', defval = 150, minval = 10 ,maxval = 400)
factor1 = input.float(title='_ATR LONG',defval = 3.2 , minval = 1 , maxval = 5 , step = 0.1, tooltip = "ATR TRAIL LONG")
factor2 = input.float(title='_ATR SHORT',defval = 3.2 , minval = 1 , maxval = 5 , step = 0.1, tooltip = "ATR TRAIL SHORT")
risk = input.float(title='RISK',defval = 200 , minval = 1 , maxval = 5000 , step = 50, tooltip = "RISK PER TRADE")


var initialCapital = strategy.equity
t = time(timeframe.period, '0915-1445:1234567')
time_cond = not na(t)

// ══════════════════════════════════ //
// -----------> EMA DATA <----------- //
// ══════════════════════════════════ //
ema1 = ta.ema(close, EMA1)

plot(ema1, color=color.new(color.yellow, 0), style=plot.style_linebr, title='ema1')

// ══════════════════════════════════ //
// --------> TRAIL DATA <------------ //
// ══════════════════════════════════ //
// *******Calculate LONG TRAIL data*****
ATR_LO = ta.atr(14)*factor1

// *******Calculate SHORT TRAIL data*****
ATR_SH = ta.atr(14)*factor2

long_trail = close - ATR_LO
short_trail = close + ATR_SH

// Plot atr data
//plot(longStop, color=color.new(color.green, 0), style=plot.style_linebr, title='Long Trailing Stop')
//plot(shortStop , color=color.new(color.red, 0), style=plot.style_linebr, title='Short Trailing Stop')

// ══════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════ //
// --------------------------------------------------------> RESISTANCE/SUPPORT LEVELS DATA <--------------------------------------------------------------------------------------------- //
// ══════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════════ //

Resistance_pi = fixnan(ta.pivothigh(L_Bars, R_Bars)[1])
Support_pi = fixnan(ta.pivotlow(L_Bars, R_Bars)[1])
r1 = plot(Resistance_pi, color=ta.change(Resistance_pi) ? na : color.red,  offset=-(R_Bars + 1),linewidth=2, title='RESISTANCE')
s1 = plot(Support_pi, color=ta.change(Support_pi) ? na : color.green, offset=-(R_Bars + 1),linewidth=2, title='SUPPORT')

//Volume
vol_1 = ta.ema(volume, 5)
vol_2 = ta.ema(volume, 10)
osc_vol = 100 * (vol_1 - vol_2) / vol_2

// ══════════════════════════════════//
// --------> LONG POSITIONS <--------//
// ══════════════════════════════════//
//******barinstate.isconfirmed used to avoid repaint in real time*******

if ( ta.crossover(close, Resistance_pi) and osc_vol > volumeRange and not(open - low > close - open) and strategy.opentrades==0 and barstate.isconfirmed and time_cond and close >= ema1 )
    strategy.entry(id= "Long" ,direction = strategy.long, comment = "BUY")

plot(long_trail , color=color.new(color.blue, 0), style=plot.style_linebr, title='long Stop')

if strategy.position_size > 0
    strategy.exit("long tsl", "Long" , stop = long_trail ,comment='SELL')

// ═════════════════════════════════════//
// --------> SHORT POSITIONS <--------- //
// ═════════════════════════════════════//
if ( ta.crossunder(close, Support_pi) and osc_vol > volumeRange and not(open - close < high - open)  and strategy.opentrades==0 and barstate.isconfirmed and time_cond and close <= ema1 )
    strategy.entry(id = "Short" ,direction = strategy.short,  comment = "SELL")

if strategy.position_size < 0
    strategy.exit("short tsl", "Short" ,  stop = short_trail ,comment='BUY')

// ════════════════════════════════════════════════//
// --------> CLOSE ALL POSITIONS BY 3PM <--------- //
// ════════════════════════════════════════════════//
strategy.close_all(when = hour == 14 and minute == 55)

// ════════════════════════════════════════//
// --------> MAX INTRADAY LOSS  <--------- //
// ════════════════════════════════════════//
// strategy.risk.max_intraday_loss(type = strategy.cash, value = risk)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Support-and-Resistance-Strategy-with-Volume-Breakout-and-Trailing-Stop-Loss.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Kana Candle Breakout Strategy Based on Moving Average and Support ResistancePine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Quantitative Trading Strategy Based on Ichimoku with Multiple SignalsPine Script · Breakout · 1h
- Honey Trend ATR Breakout StrategyPine Script · Breakout · 1h