Swing Points Breakouts Long term strategy
The Swing Points Breakouts strategy is a long-term trend fluctuation strategy based on swing high and swing low identification. The strategy enters long positions when prices break through the highest price in the…
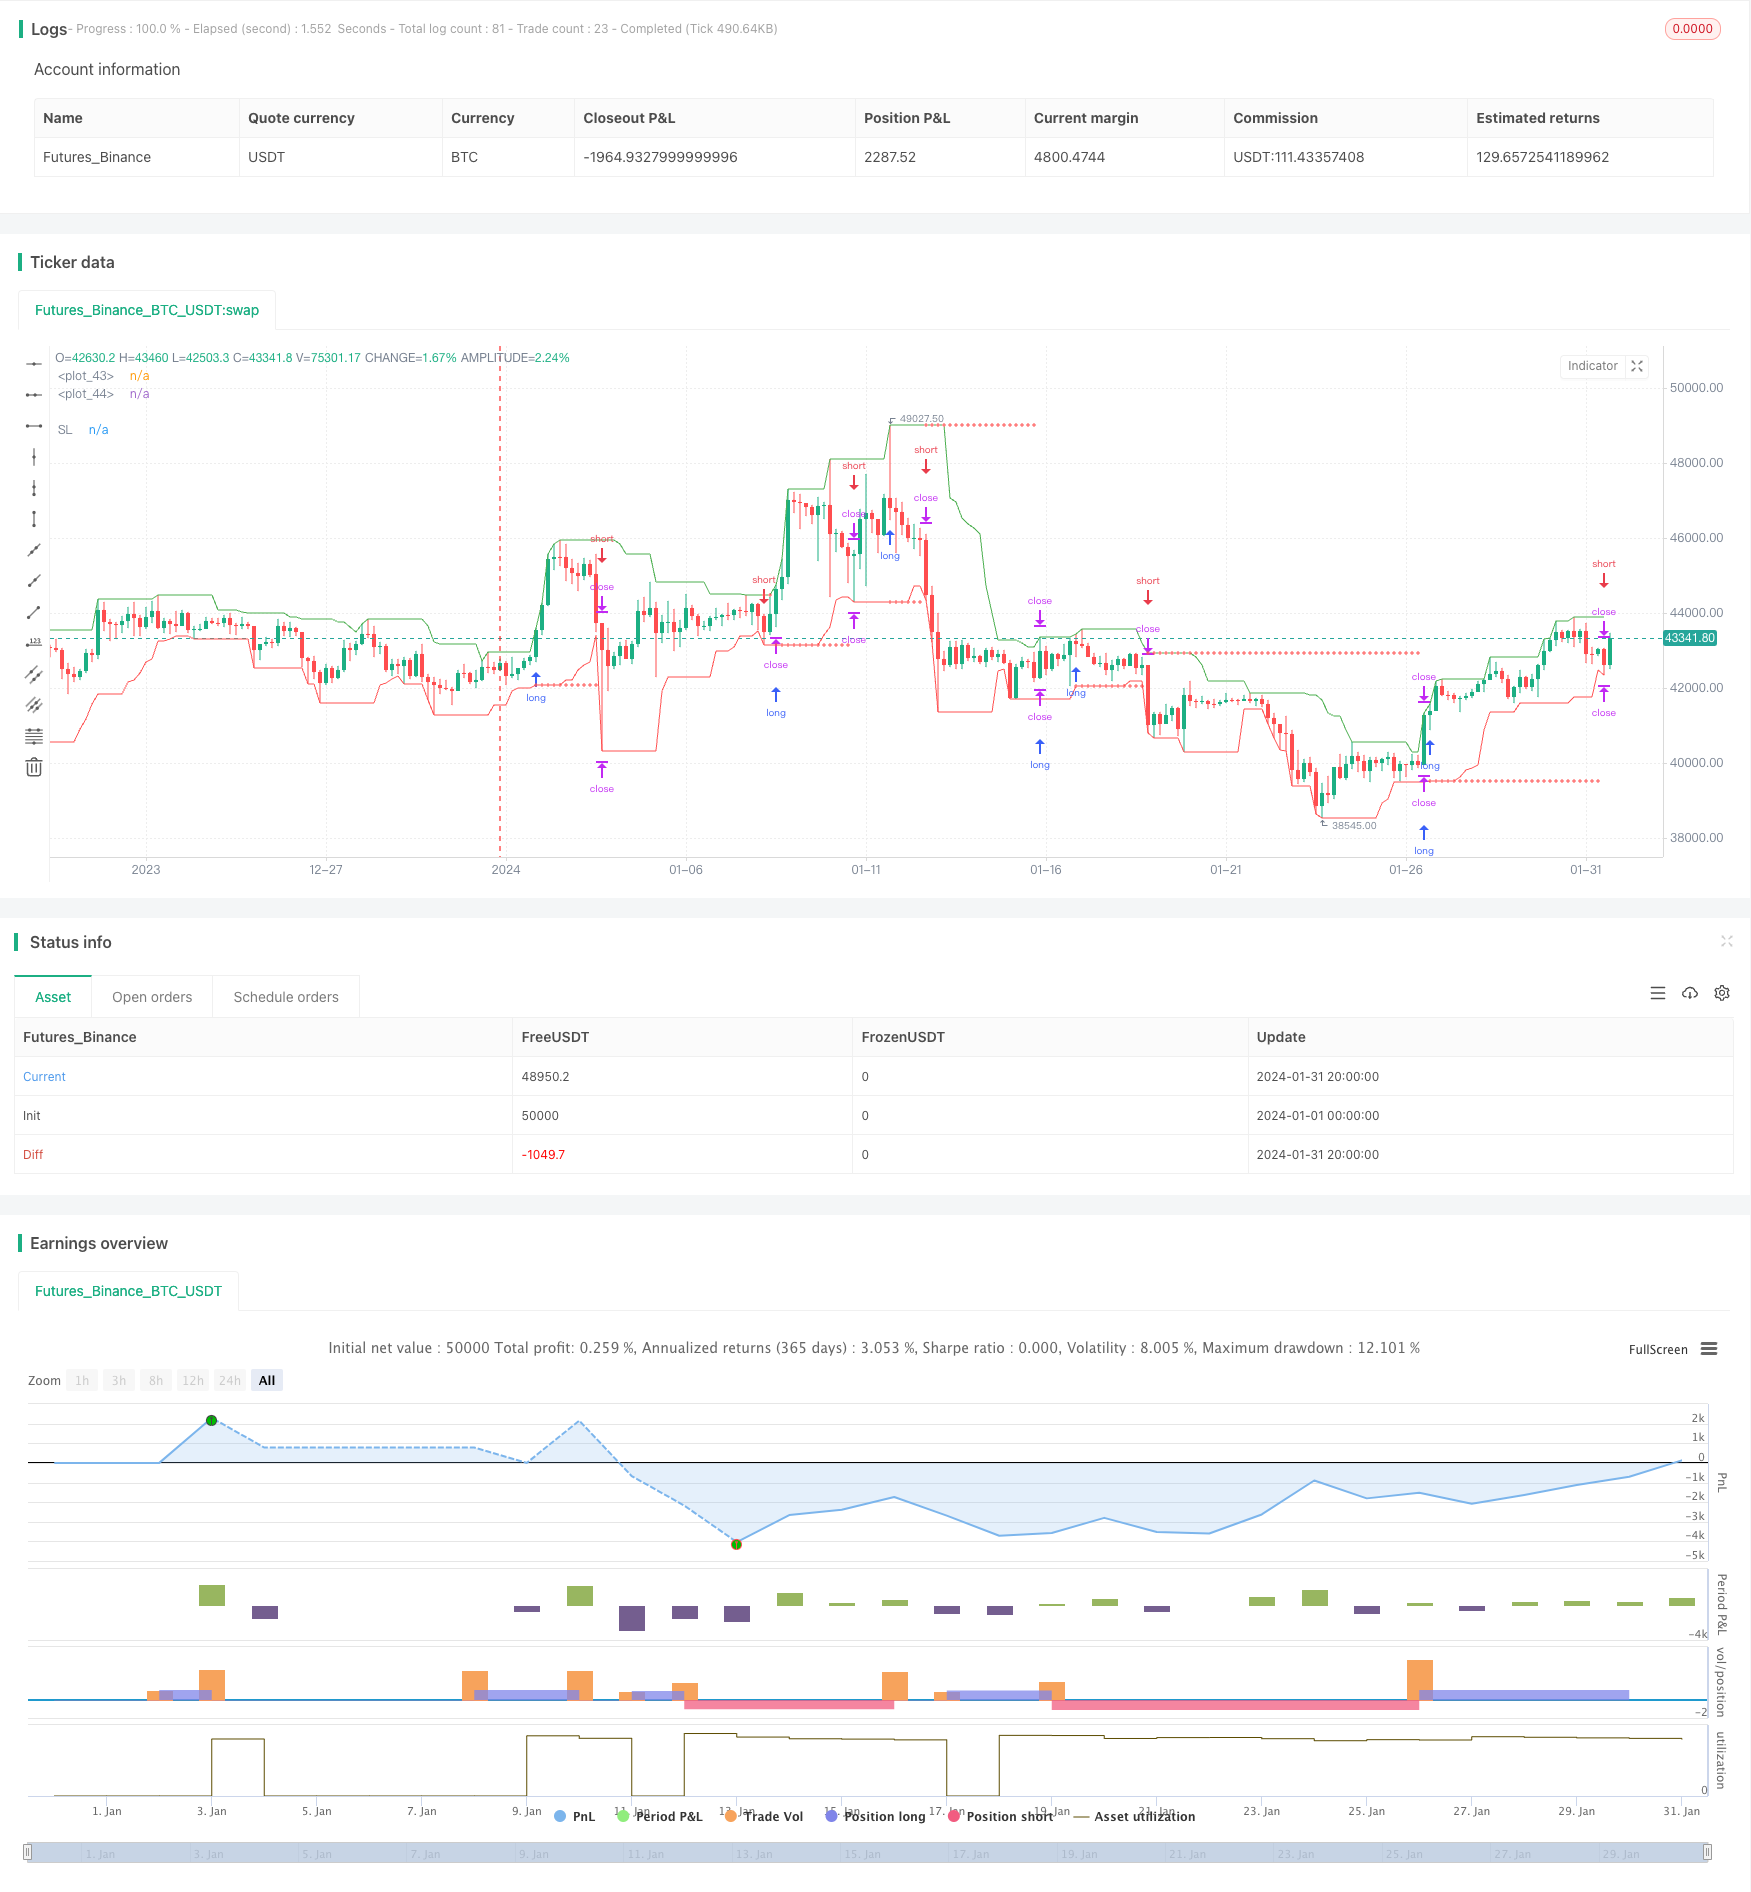
Overview
The Swing Points Breakouts strategy is a long-term trend fluctuation strategy based on swing high and swing low identification. The strategy enters long positions when prices break through the highest price in the most recent period specified by input parameters, and enters short positions when prices break through the lowest price in the most recent period.
Strategy Logic
The strategy defines the most recent N bar's highest price and lowest price as the swing high and swing low through input parameters. It determines the entry and exit based on the direction parameter. When going long, it enters long positions with an OCO stop order when prices break through the swing high. When going short, it enters short positions with an OCO stop order when prices break through the swing low.
In addition, the strategy sets up stop losses. After opening long positions, the stop loss is set near the recent lowest price. After opening short positions, the stop loss is set near the most recent highest price. This effectively avoids huge losses in a trending market.
Advantage Analysis
The biggest advantage of this strategy is that it captures key fluctuations around swing highs and lows and profits accordingly. Setting stop losses also effectively controls risks.
Specifically the advantages are:
The strategy logic is clear, with entries and exits based on swing high/low breakouts.
It utilizes swing highs/lows to identify reversal opportunities, a classic technical analysis approach.
There are stop losses set to control risks and avoid huge losses in trending markets.
The code has clear structure and is easy to understand and modify.
Parameters can be adjusted to optimize the strategy, like tuning the swing high/low period.
Risk Analysis
The main risk of this strategy comes from inaccurate swing high/low identification leading to wrong trades. The specific risks include:
False breakout of swing highs/lows resulting in wrong entries.
Huge stop loss hit near the breakout points.
Trending symbols tend to need huge costs determining swing points.
Improper parameter tuning also affects strategy performance.
The solutions include:
Optimizing parameters like swing high/low period.
Increasing stop loss distance.
Avoiding using it on trending symbols.
Adopting machine learning to dynamically optimize parameters.
Optimization Directions
The strategy can be optimized in the following directions:
Dynamic optimization of swing high/low periods instead of fixed values to avoid overfitting.
Introducing dynamic stop loss/take profit based on ATR and volatility.
Combining multiple time frames, using higher TFs to define trend and lower TFs for entry.
Incorporating machine learning models to predict potential swing points and improve performance.
Optimizing the stop loss algorithms to avoid unnecessary hits while keeping effective stop loss.
Conclusion
The Swing Points Breakouts strategy is a practical long-term quantitative strategy overall. By capturing reversal opportunities around swing points and setting stop losses to control risks, it ensures profits while also controlling drawdowns. With flexible parameter tuning and clear logic, it is a recommended strategy paradigm worth utilizing. Further improvements can be made by introducing dynamic optimization and machine learning.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Strategy Direction |
| v_input_2 | true | Use Swing Lo/Hi Stop Loss & Take Profit |
| v_input_3 | 10 | Swing Low Lookback |
| v_input_4 | 10 | Swing High Lookback |
| v_input_5 | false | Reverse Trades |
| v_input_6 | false | SL Expander |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 4h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © tweakerID

// Long term strategy for managing a Crypto investment with Swing Trades of more than 1 day. The strategy buys with a
// stop order at the Swing High price (green line) and sells with a stop order at the Swing Low price (red line).
// The direction of the strategy can be adjusted in the Inputs panel.

//@version=4
strategy("Swing Points Breakouts", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100, initial_capital=10000, commission_value=0.04)

direction = input(0, title = "Strategy Direction", type=input.integer, minval=-1, maxval=1)
strategy.risk.allow_entry_in(direction == 0 ? strategy.direction.all : (direction < 0 ? strategy.direction.short : strategy.direction.long))

//Inputss
i_SL=input(true, title="Use Swing Lo/Hi Stop Loss & Take Profit")
i_SwingLow=input(10, title="Swing Low Lookback")
i_SwingHigh=input(10, title="Swing High Lookback")
i_reverse=input(false, "Reverse Trades")
i_SLExpander=input(defval=0, step=1, title="SL Expander")

//Strategy Calculations
SwingLow=lowest(i_SwingLow)
SwingHigh=highest(i_SwingHigh)

//SL & TP Calculations
bought=strategy.position_size != strategy.position_size[1]
LSL=valuewhen(bought, SwingLow, 0)-((valuewhen(bought, atr(14), 0)/5)*i_SLExpander)
SSL=valuewhen(bought, SwingHigh, 0)+((valuewhen(bought, atr(14), 0)/5)*i_SLExpander)
islong=strategy.position_size > 0
isshort=strategy.position_size < 0
SL= islong ? LSL : isshort ? SSL : na

//Entries and Exits
strategy.entry("long", true, stop=i_reverse?na:SwingHigh, limit=i_reverse?SwingLow:na)
strategy.entry("short", false, stop=i_reverse?na:SwingLow, limit=i_reverse?SwingHigh:na)

if i_SL
    strategy.exit("longexit", "long", stop=LSL)
    strategy.exit("shortexit", "short", stop=SSL)

//Plots
plot(i_SL ? SL : na, color=color.red, style=plot.style_cross, title="SL")
plot(SwingLow, color=color.red)
plot(SwingHigh, color=color.green)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Swing-Points-Breakouts-Long-term-strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d