Strategy vault / Trend following
T3 Moving Average Trend Following Strategy with Trailing Stop Loss
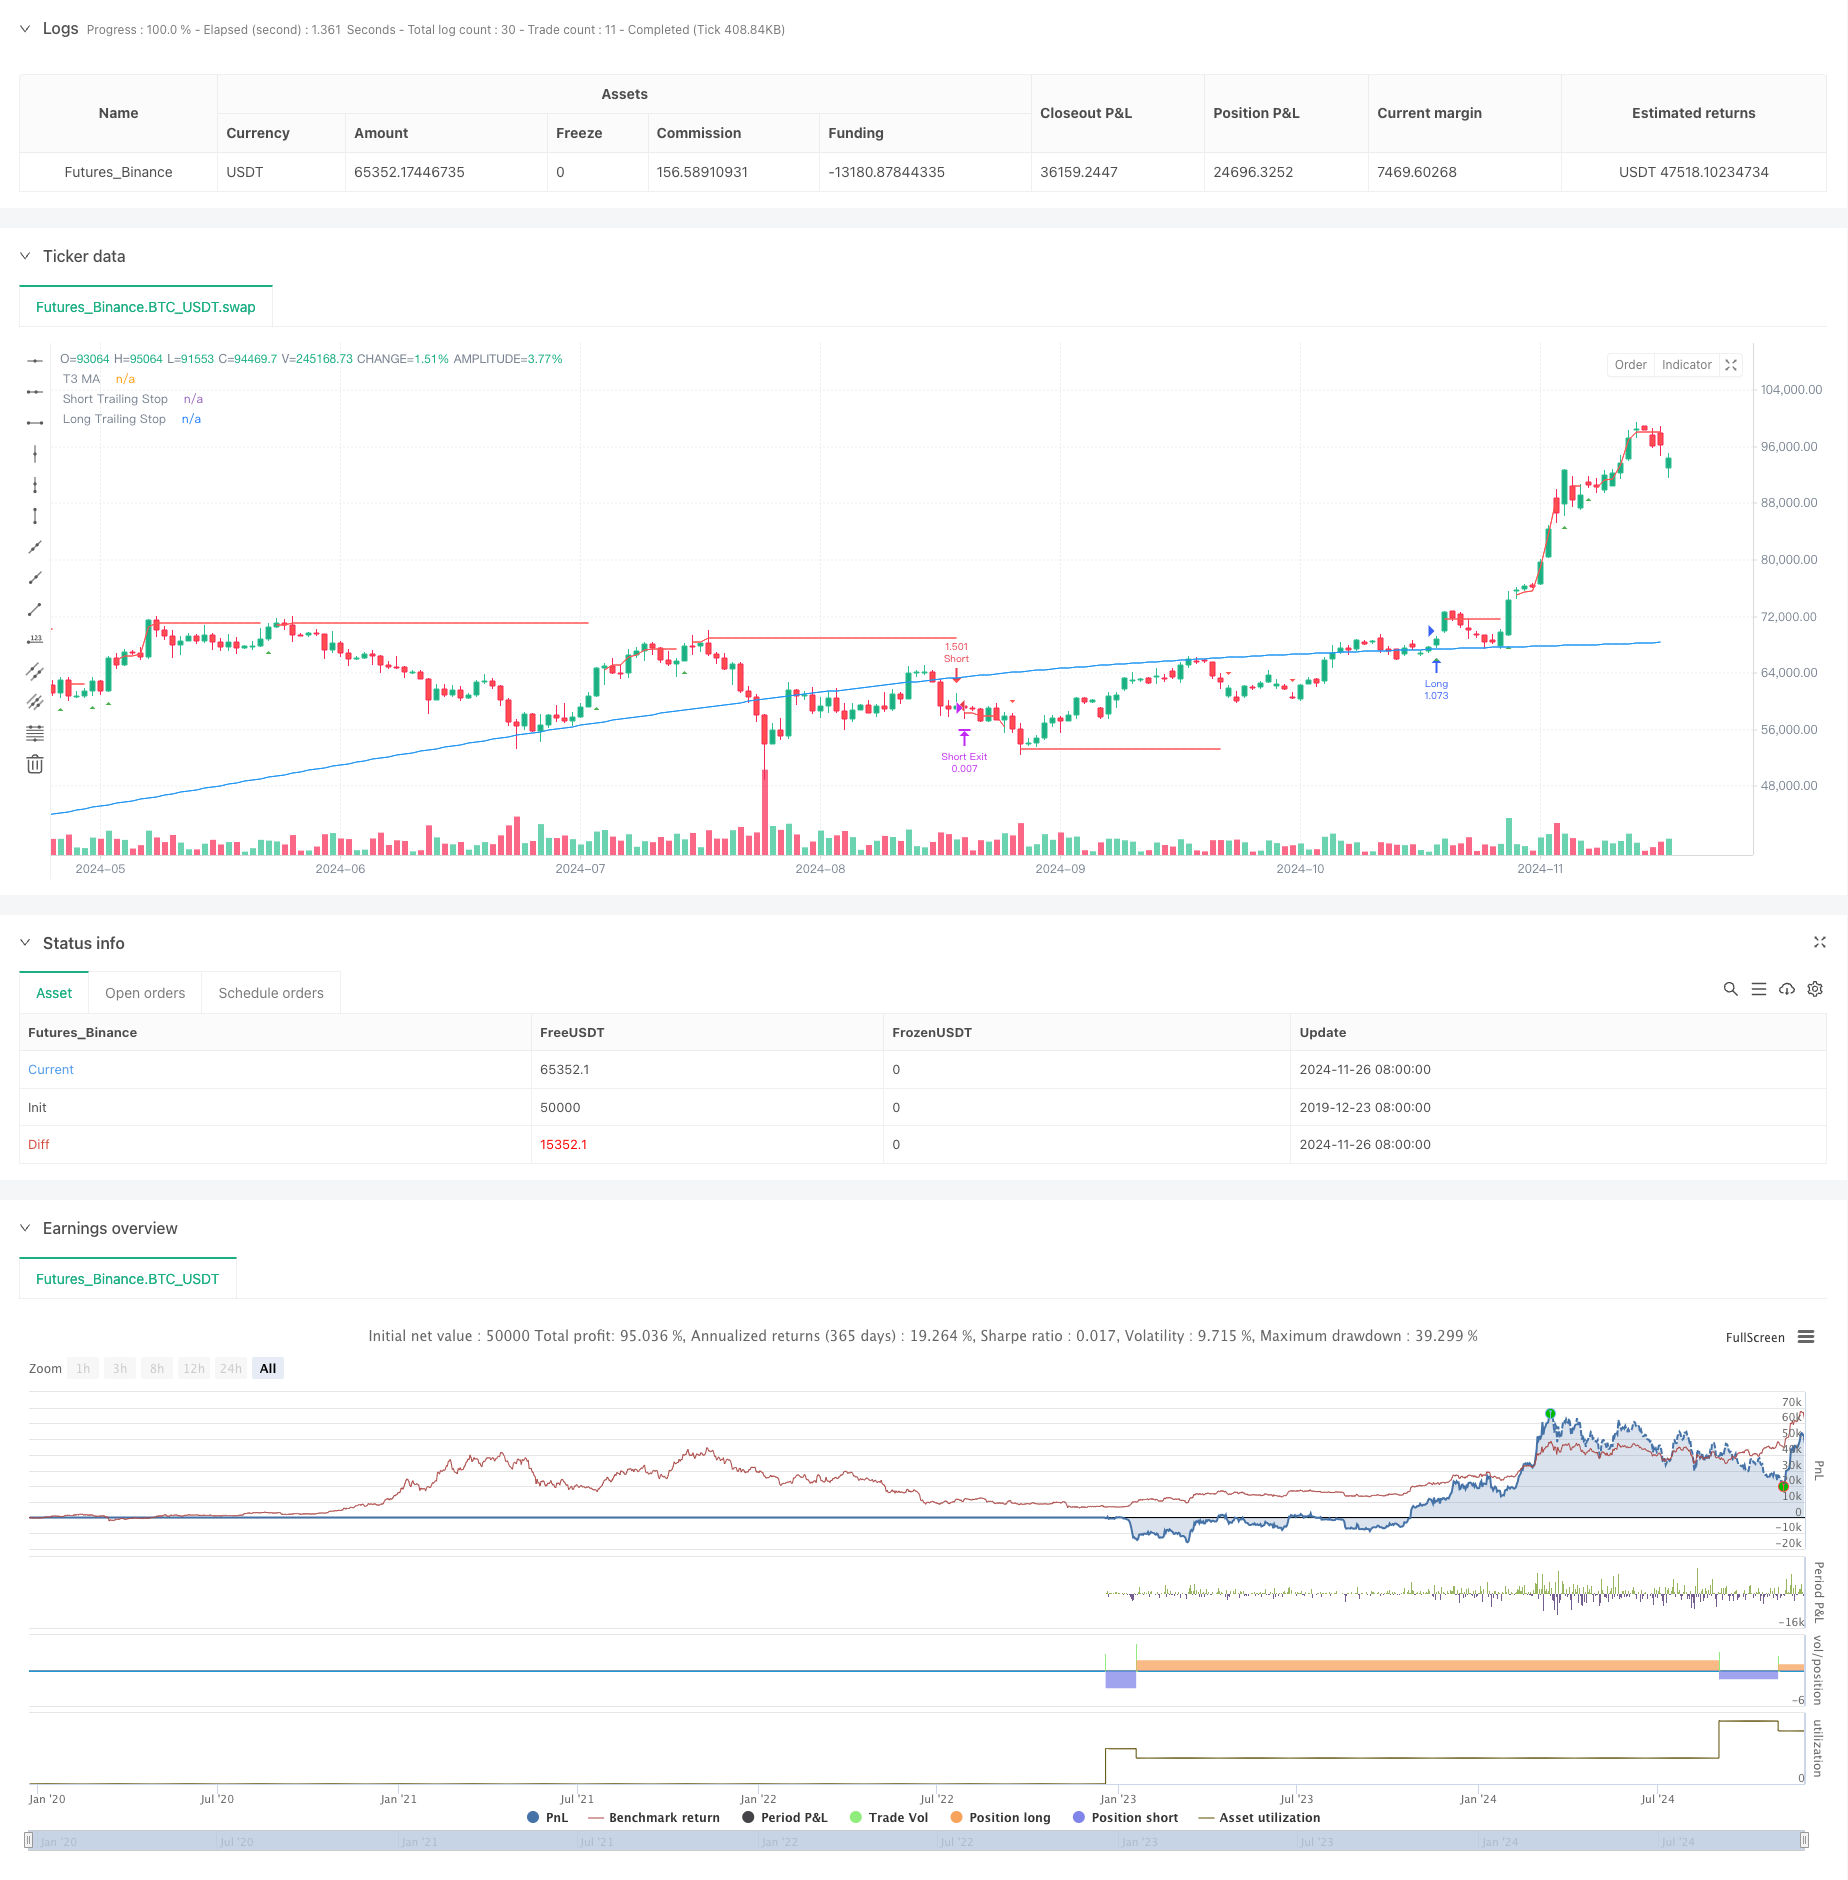
This strategy is a comprehensive quantitative trading system that combines T3 Moving Average, trend following, and trailing stop loss mechanisms. The strategy identifies market trend direction using T3 Moving…
Overview
This strategy is a comprehensive quantitative trading system that combines T3 Moving Average, trend following, and trailing stop loss mechanisms. The strategy identifies market trend direction using T3 Moving Average, confirms signals using Lemon Trend Indicator and TDFI indicator, and incorporates a risk management system that combines trailing stops with fixed stops to capture trends and effectively control risks.
Strategy Principles
The strategy consists of three main components: trend identification, signal confirmation, and risk management. First, it uses T3 Moving Average as the primary trend identification tool, which reduces lag while maintaining smoothness through six-fold exponential moving average calculations. Second, it calculates price volatility ranges using the Lemon Trend Indicator and filters signals with the TDFI indicator, generating trade signals only when price breaks through the volatility range and TDFI confirms. Finally, the strategy employs a combination of trailing and fixed stops for risk management, with trailing stops activating after price reaches threshold levels while maintaining fixed stops as protection.
Strategy Advantages
- Multiple signal confirmation mechanisms improve trading accuracy
- T3 Moving Average reduces the impact of false breakouts
- Flexible risk management system that protects profits while allowing trends to develop
- Supports partial position exits for staged profit realization
- Highly adjustable parameters for optimization in different market conditions
Strategy Risks
- Complex T3 Moving Average calculations may introduce computational delays
- Multiple signal confirmations might cause missed trading opportunities
- Trailing stops may trigger prematurely during volatile market conditions
- Requires significant price movements to generate effective signals
- May generate frequent false signals in ranging markets
Optimization Directions
- Introduce volatility indicators to adjust trailing stop parameters
- Add market environment recognition module for different parameter sets
- Optimize TDFI indicator calculation periods for improved signal timing
- Consider incorporating volume factors for signal confirmation
- Research adaptive partial profit-taking ratio mechanisms
Conclusion
This is a comprehensively designed trend-following strategy that ensures reliable trading signals and effective risk management through multiple technical indicators. The strategy's modular design provides good extensibility and optimization potential, making it suitable as a foundation for medium to long-term trend following systems. In practical application, it is recommended to optimize parameters based on specific trading instruments and market conditions.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Lemon Trend Strategy", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// Input parameters
lookbackPeriod = input.int(14, "Lookback Period")
t3Length = input.int(200, "T3 MA Length")
t3Factor = input.float(0.7, "T3 Factor", minval=0, maxval=1)

// Trailing Stop Parameters
trailingStopPct = input.float(1.5, "Trailing stop percentage", minval=0.1, step=0.1)
trailingStopActivationPct = input.float(1.0, "Trailing stop activation percentage", minval=0.1, step=0.1)

// === T3 Moving Average Function ===
t3(src, length, factor) =>
    // First EMA
    e1 = ta.ema(src, length)
    // Second EMA
    e2 = ta.ema(e1, length)
    // Third EMA
    e3 = ta.ema(e2, length)
    // Fourth EMA
    e4 = ta.ema(e3, length)
    // Fifth EMA
    e5 = ta.ema(e4, length)
    // Sixth EMA
    e6 = ta.ema(e5, length)

    c1 = -factor * factor * factor
    c2 = 3 * factor * factor + 3 * factor * factor * factor
    c3 = -6 * factor * factor - 3 * factor - 3 * factor * factor * factor
    c4 = 1 + 3 * factor + factor * factor * factor + 3 * factor * factor

    t3 = c1 * e6 + c2 * e5 + c3 * e4 + c4 * e3

// Calculate T3 MA
t3ma = t3(close, t3Length, t3Factor)
plot(t3ma, "T3 MA", color=color.blue)

// === Lemon Trend Indicator ===
highLowDiff = high - low
normalizedDiff = ta.sma(highLowDiff, lookbackPeriod)
upperBand = ta.highest(high, lookbackPeriod)
lowerBand = ta.lowest(low, lookbackPeriod)
buySignal = ta.crossover(close, upperBand - normalizedDiff)
sellSignal = ta.crossunder(close, lowerBand + normalizedDiff)

// === TDFI Indicator ===
tdfiLength = input.int(14, "TDFI Length")
tdfi = ta.ema(close - close[1], tdfiLength)
tdfiSignal = ta.ema(tdfi, 9)

// Plot signals
plotshape(buySignal and tdfi > tdfiSignal and close > t3ma, "Buy Signal", location=location.belowbar, color=color.green, style=shape.triangleup, size=size.small)
plotshape(sellSignal and tdfi < tdfiSignal and close < t3ma, "Sell Signal", location=location.abovebar, color=color.red, style=shape.triangledown, size=size.small)

// === Strategy Logic ===
longCondition = buySignal and tdfi > tdfiSignal and close > t3ma
shortCondition = sellSignal and tdfi < tdfiSignal and close < t3ma

// Calculate trailing stop price
var float longTrailingStop = na
var float shortTrailingStop = na

// Update trailing stop price
if (strategy.position_size > 0)
    threshold = strategy.position_avg_price * (1 + trailingStopActivationPct / 100)
    if (high > threshold)
        stopPrice = high * (1 - trailingStopPct / 100)
        if (na(longTrailingStop) or stopPrice > longTrailingStop)
            longTrailingStop := stopPrice

if (strategy.position_size < 0)
    threshold = strategy.position_avg_price * (1 - trailingStopActivationPct / 100)
    if (low < threshold)
        stopPrice = low * (1 + trailingStopPct / 100)
        if (na(shortTrailingStop) or stopPrice < shortTrailingStop)
            shortTrailingStop := stopPrice

// Entry orders
if (longCondition)
    strategy.entry("Long", strategy.long)
    longTrailingStop := na

if (shortCondition)
    strategy.entry("Short", strategy.short)
    shortTrailingStop := na

// Calculate stop loss and take profit levels
longStopLoss = ta.lowest(low, lookbackPeriod)
shortStopLoss = ta.highest(high, lookbackPeriod)

// Exit conditions with fixed R:R
fixedRR = input.float(1.8, "Fixed Risk:Reward Ratio")
partialExitPct = input.float(50.0, "Partial Exit Percentage", minval=0, maxval=100) / 100

// Comprehensive trailing stop loss and fixed stop loss
if (strategy.position_size > 0)
    longTakeProfit = strategy.position_avg_price + (strategy.position_avg_price - longStopLoss) * fixedRR
    stopPrice = na(longTrailingStop) ? longStopLoss : math.max(longStopLoss, longTrailingStop)
    strategy.exit("Long Exit", "Long", qty_percent=partialExitPct, stop=stopPrice, limit=longTakeProfit)

if (strategy.position_size < 0)
    shortTakeProfit = strategy.position_avg_price - (shortStopLoss - strategy.position_avg_price) * fixedRR
    stopPrice = na(shortTrailingStop) ? shortStopLoss : math.min(shortStopLoss, shortTrailingStop)
    strategy.exit("Short Exit", "Short", qty_percent=partialExitPct, stop=stopPrice, limit=shortTakeProfit)

// Draw trailing stop line
plot(strategy.position_size > 0 ? longTrailingStop : na, "Long Trailing Stop", color=color.red, style=plot.style_linebr)
plot(strategy.position_size < 0 ? shortTrailingStop : na, "Short Trailing Stop", color=color.red, style=plot.style_linebr)Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/T3-Moving-Average-Trend-Following-Strategy-with-Trailing-Stop-Loss.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d