Strategy vault / Mean reversion
The Multi Timeframe Bottom Reversal Strategy
This strategy combines multiple bottom pattern indicators to identify major reversal opportunities, adopting a trend following stop loss strategy to target profits exceeding stop loss.
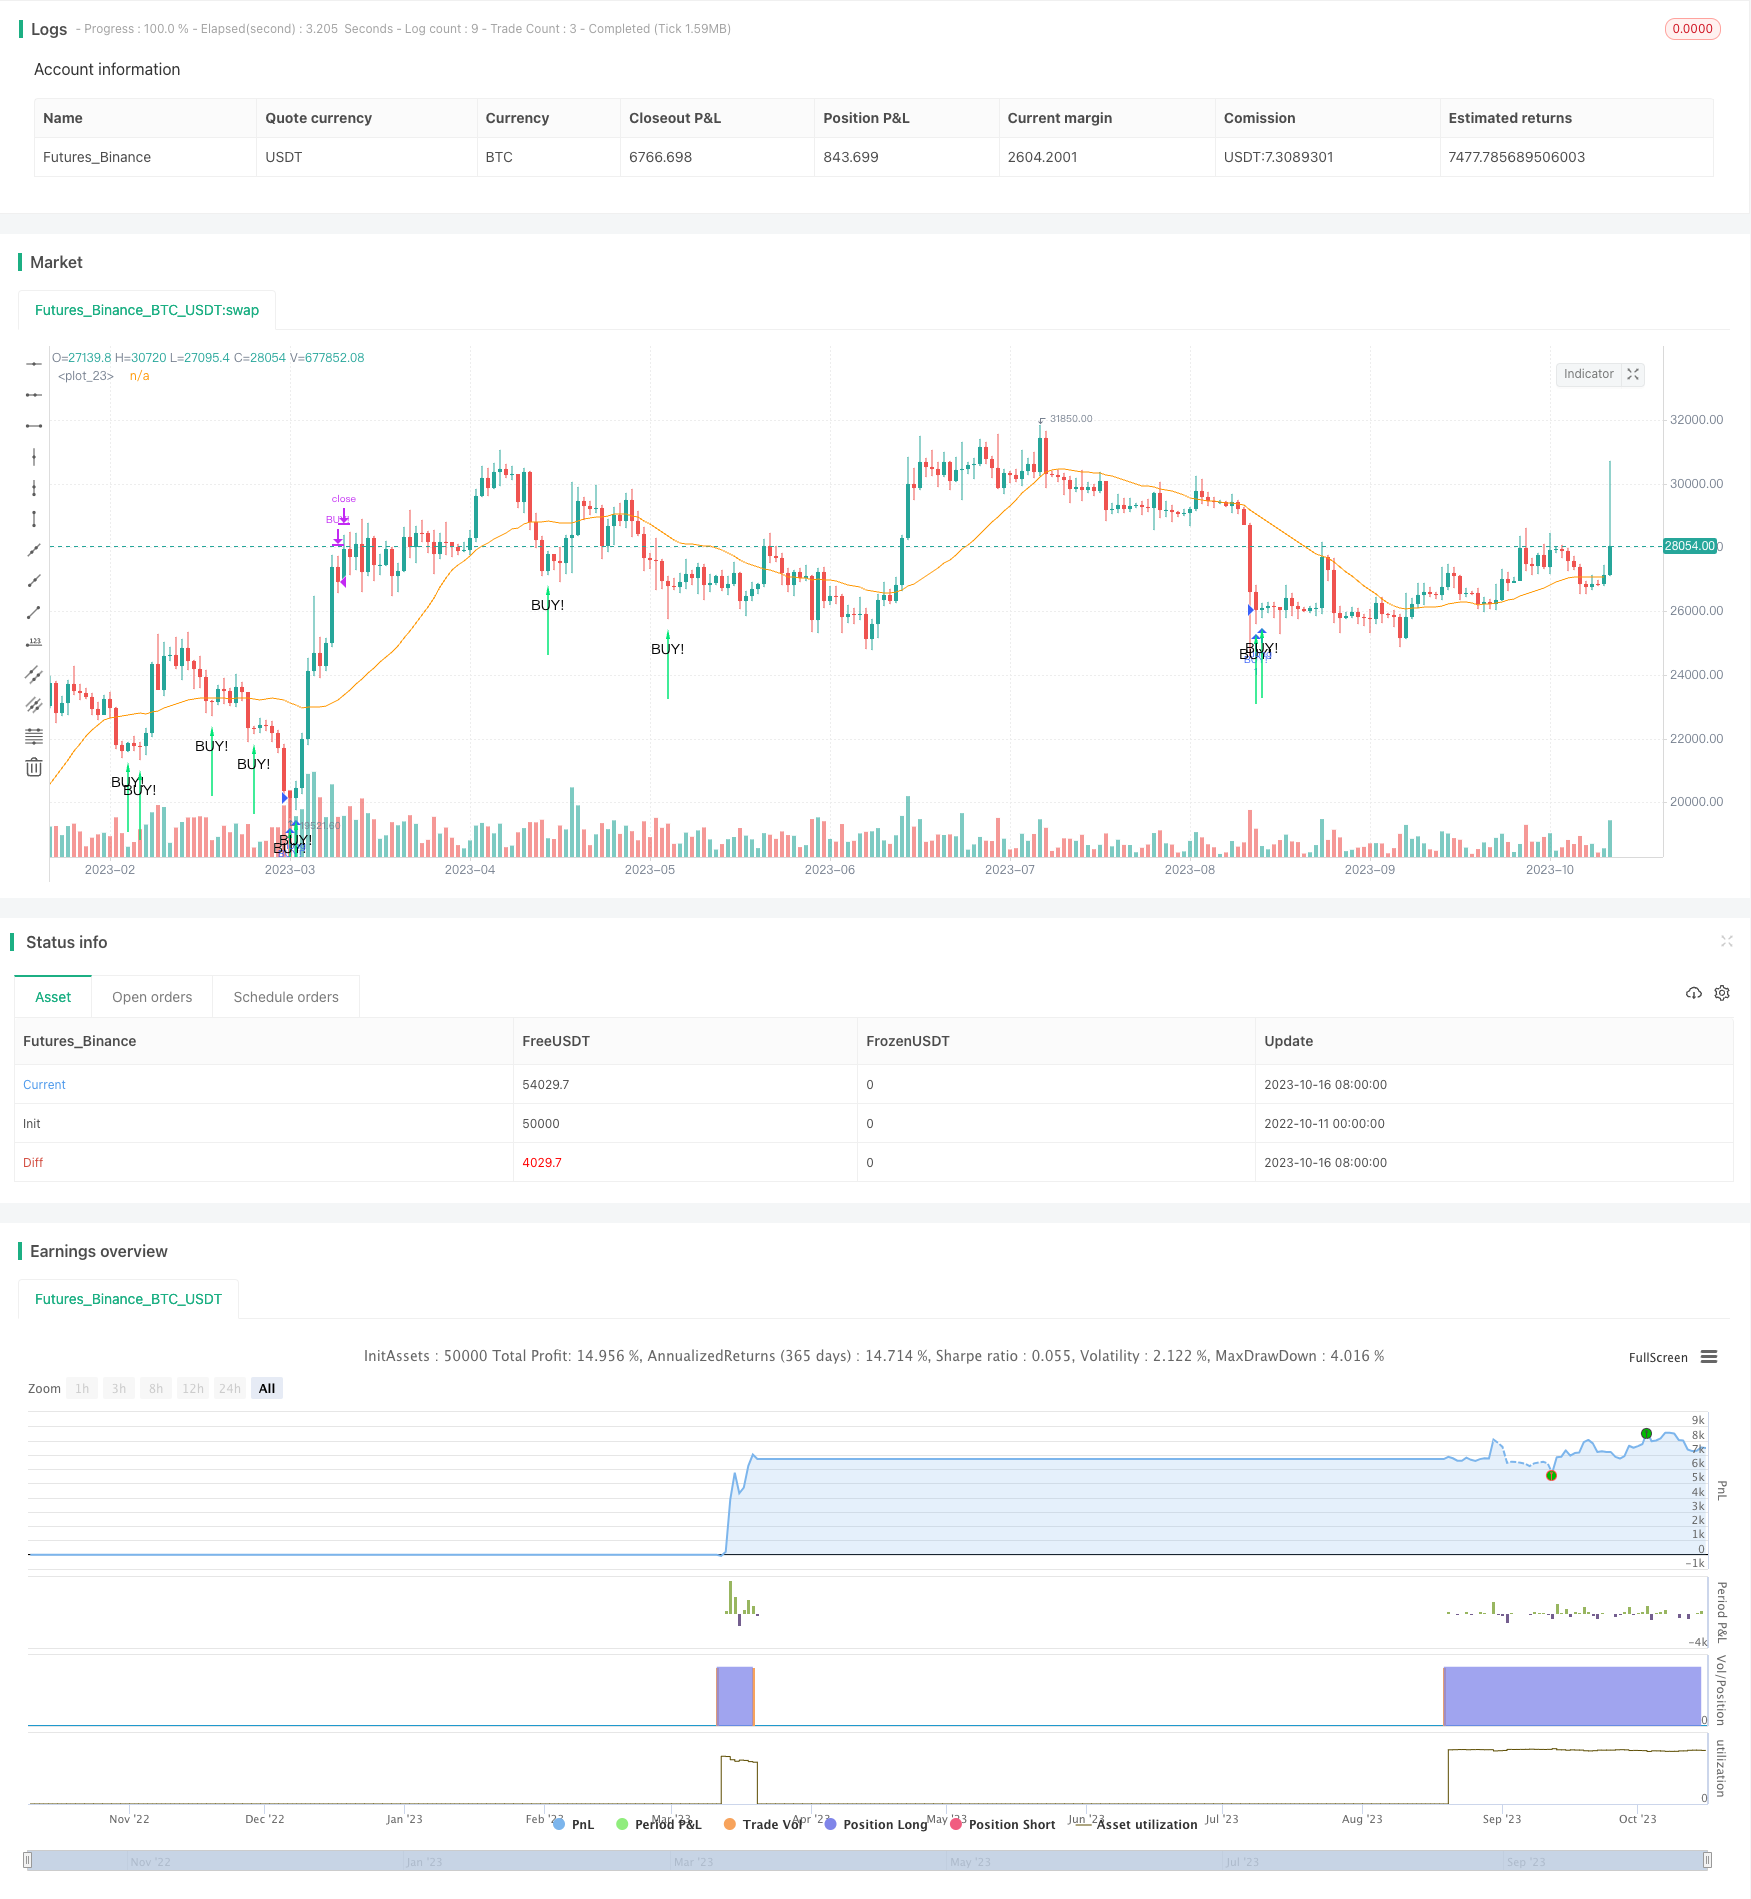
Overview
This strategy combines multiple bottom pattern indicators to identify major reversal opportunities, adopting a trend following stop loss strategy to target profits exceeding stop loss.
Principle
The strategy mainly uses the following indicators to determine bottom reversal:
Bottom Sensivity Indicator (Noro's BottomSensivity): Detect specific bottom patterns on the candlestick chart.
Certainty of Volition Index (CVI): Determine the shift in bullish/bearish sentiment.
Ultimate Cycle Signal (UCS): Detect oversold below the moving average.
Relative Strength Index (RSI): Identify oversold conditions.
Pattern Combination: Including candlestick, pin bar and other bottom patterns.
The strategy combines multiple bottom indicators, generating buy signals when the number of bottom patterns meets the parameter settings. To filter false breaks, RSI is also used to trigger buy only in oversold conditions.
Users can customize the usage and parameters of each bottom indicator, providing high flexibility. The SMA filter avoids buying into a downtrend.
Advantages
Improved accuracy using multiple indicators
Customizable parameters suit different products
SMA filter prevents buying tops
Optional red candles only reduce risk
Alerts allow realtime monitoring
Risks
Multiple indicators may miss bottoms
Bottom patterns do not always reverse
Need to watch if volume supports reversal
Enhancement
Optimize parameters for different products
Add position sizing to lower cost basis
Implement stop loss to lock in profits
Summary
The strategy effectively identifies bottoms with multiple indicators, controlling risk with trend following stop loss. But volume support needs monitoring. Users can optimize parameters per product characteristics.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 35 | overSold |
| v_input_2 | 70 | overBought |
| v_input_3 | 3 | Bottom-Sensivity |
| v_input_4 | 25 | SMA Length |
| v_input_5 | 3 | Bars of Locomotive |
| v_input_6 | true | Use bottom-pattern Locomotive? |
| v_input_7 | true | Use bottom-pattern Pin-bar? |
| v_input_8 | true | Use bottom-indicator CVI? |
| v_input_9 | true | Use bottom-indicator UCS? |
| v_input_10 | true | Use bottom-indicator WVF? |
| v_input_11 | true | Use bottom-indicator RSI? |
| v_input_12 | false | Only red candles? |
| v_input_13 | true | Use SMA Filter? |
| v_input_14 | false | Show SMA Filter? |
Source Pine Script
/*backtest
start: 2022-10-11 00:00:00
end: 2023-10-17 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// the original indicator is Noro's BottomSensivity v0.6
//@version=4
strategy("Noro's BottomSensivity v0.6 strategy + rsi + Alarm", shorttitle="Bottom 0.6 StRsiAlarm", overlay=true)

overSold = input(35)
overBought = input(70)
botsens = input(defval = 3, minval = 1, maxval = 4, title = "Bottom-Sensivity")
smalen = input(defval = 25, minval = 20, maxval = 200, title = "SMA Length")
bars = input(defval = 3, minval = 2, maxval = 4, title = "Bars of Locomotive")
useloc = input(true, title = "Use bottom-pattern Locomotive?")
usepin = input(true, title = "Use bottom-pattern Pin-bar?")
usecvi = input(true, title = "Use bottom-indicator CVI?")
useucs = input(true, title = "Use bottom-indicator UCS?")
usevix = input(true, title = "Use bottom-indicator WVF?")
usersi = input(true, title = "Use bottom-indicator RSI?")
usered = input(false, title = "Only red candles?")
usesma = input(true, title = "Use SMA Filter?")
showsma = input(false, title = "Show SMA Filter?")

//SMA Filter
sma = sma(close, smalen)
colsma = showsma == true ? red : na
plot(sma, color = colsma)

//VixFix method
//Start of ChrisMoody's code
pd = 22
bbl = 20
mult = 2
lb = 50
ph = .85
pl = 1.01
hp = false
sd = false
wvf = ((highest(close, pd)-low)/(highest(close, pd)))*100
sDev = mult * stdev(wvf, bbl)
midLine = sma(wvf, bbl)
lowerBand = midLine - sDev
upperBand = midLine + sDev
rangeHigh = (highest(wvf, lb)) * ph
rangeLow = (lowest(wvf, lb)) * pl
//End of ChrisMoody's code

//Locomotive mmethod
bar = close > open ? 1 : close < open ? -1 : 0
locob = bar == 1 and bar[1] == -1 and bar[2] == -1 and (bar[3] == -1 or bars < 3) and (bar[4] == -1 or bars < 4) ? 1 : 0

//PIN BAR
body = abs(close - open)
upshadow = open > close? (high - open) : (high - close)
downshadow = open > close ? (close - low) : (open - low)
pinbar = open[1] > close[1] ? (body[1] > body ? (downshadow > 0.5 * body ? (downshadow > 2 * upshadow ? 1 : 0 ) : 0 ) : 0 ) : 0

//CVI method
//Start of LazyBear's code
ValC=sma(hl2, 3)
bull=-.51
bear=.43
vol=sma(atr(3), 3)
cvi = (close-ValC) / (vol*sqrt(3))
cb= cvi <= bull ? green : cvi >=bear ? red : cvi > bull ? blue : cvi < bear ? blue : na
bull1 = cvi <= bull
bear1 = cvi >= bear
bull2 = bull1[1] and not bull1
bear2 = bear1[1] and not bear1
//End of LazyBear's code

//UCS method
//Start of UCS's code
ll = lowest(low, 5)
hh = highest(high, 5)
diff = hh - ll
rdiff = close - (hh+ll)/2
avgrel = ema(ema(rdiff,3),3)
avgdiff = ema(ema(diff,3),3)
mom = ((close - close[3])/close[3])*1000
SMI = avgdiff != 0 ? (avgrel/(avgdiff/2)*100) : 0
SMIsignal = ema(SMI,3)
ucslong = SMI < -35  and mom > 0 and mom[1] < 0 ? 1 : 0
//End of UCS's code

//RSI method
//Chris Moody's code
up = rma(max(change(close), 0), 2)
down = rma(-min(change(close), 0), 2)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
rsib = rsi < 10 ? 1 : 0
//Chris Moody's code

//sum
locobot = useloc == false ? 0 : locob
vixfixbot = usevix == false ? 0 : wvf >= upperBand or wvf >= rangeHigh ? 1 : 0
cvibot = usecvi == false ? 0 : bull2 == true ? 1 : 0
ucsbot = useucs == false ? 0 : ucslong == 1 ? 1 : 0
rsibot = usersi == false ? 0 : rsib
pinbot = usepin == false ? 0 : pinbar
score = vixfixbot + locobot + cvibot + ucsbot + rsibot + pinbot

//arrows
bottom = usered == false ? usesma == false ? score >= botsens ? 1 : 0 : high < sma and score >= botsens ? 1 : 0 : usesma == false ? score >= botsens and close < open ? 1 : 0 : high < sma and score >= botsens and close < open ? 1 : 0
plotarrow(bottom == 1 ? 1 : na, title="Buy arrow", colorup=lime, maxheight=60, minheight=50, transp=0)
data = bottom == 1
plotchar(data, char=" ", text="BUY!", location=location.belowbar, color=green, size=size.small)


//Market buy and exit
strategy.entry("BUY!", strategy.long, when =(bottom == 1) and(rsi(close,14)<overSold))
strategy.close("BUY!", when = (crossunder(rsi(close,14), overBought)))
alarm = bottom == 1 and(rsi(close,14)<overSold)
alertcondition(alarm == 1,title="BUY+RSI",message="BUY+RSI")Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/The-Multi-Timeframe-Bottom-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- MACD Cross Period Trading StrategyPine Script · Mean reversion · 1d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- Reversal Trading Strategy with Bollinger Bands RSI ADX and ATRPine Script · Mean reversion · 1h