The Oscillating Breakthrough Strategy
The Oscillating Breakthrough Strategy is an active trading strategy for mainstream cryptocurrencies using a 15-minute timeframe. It utilizes technical indicators to identify market trends, discover potential…
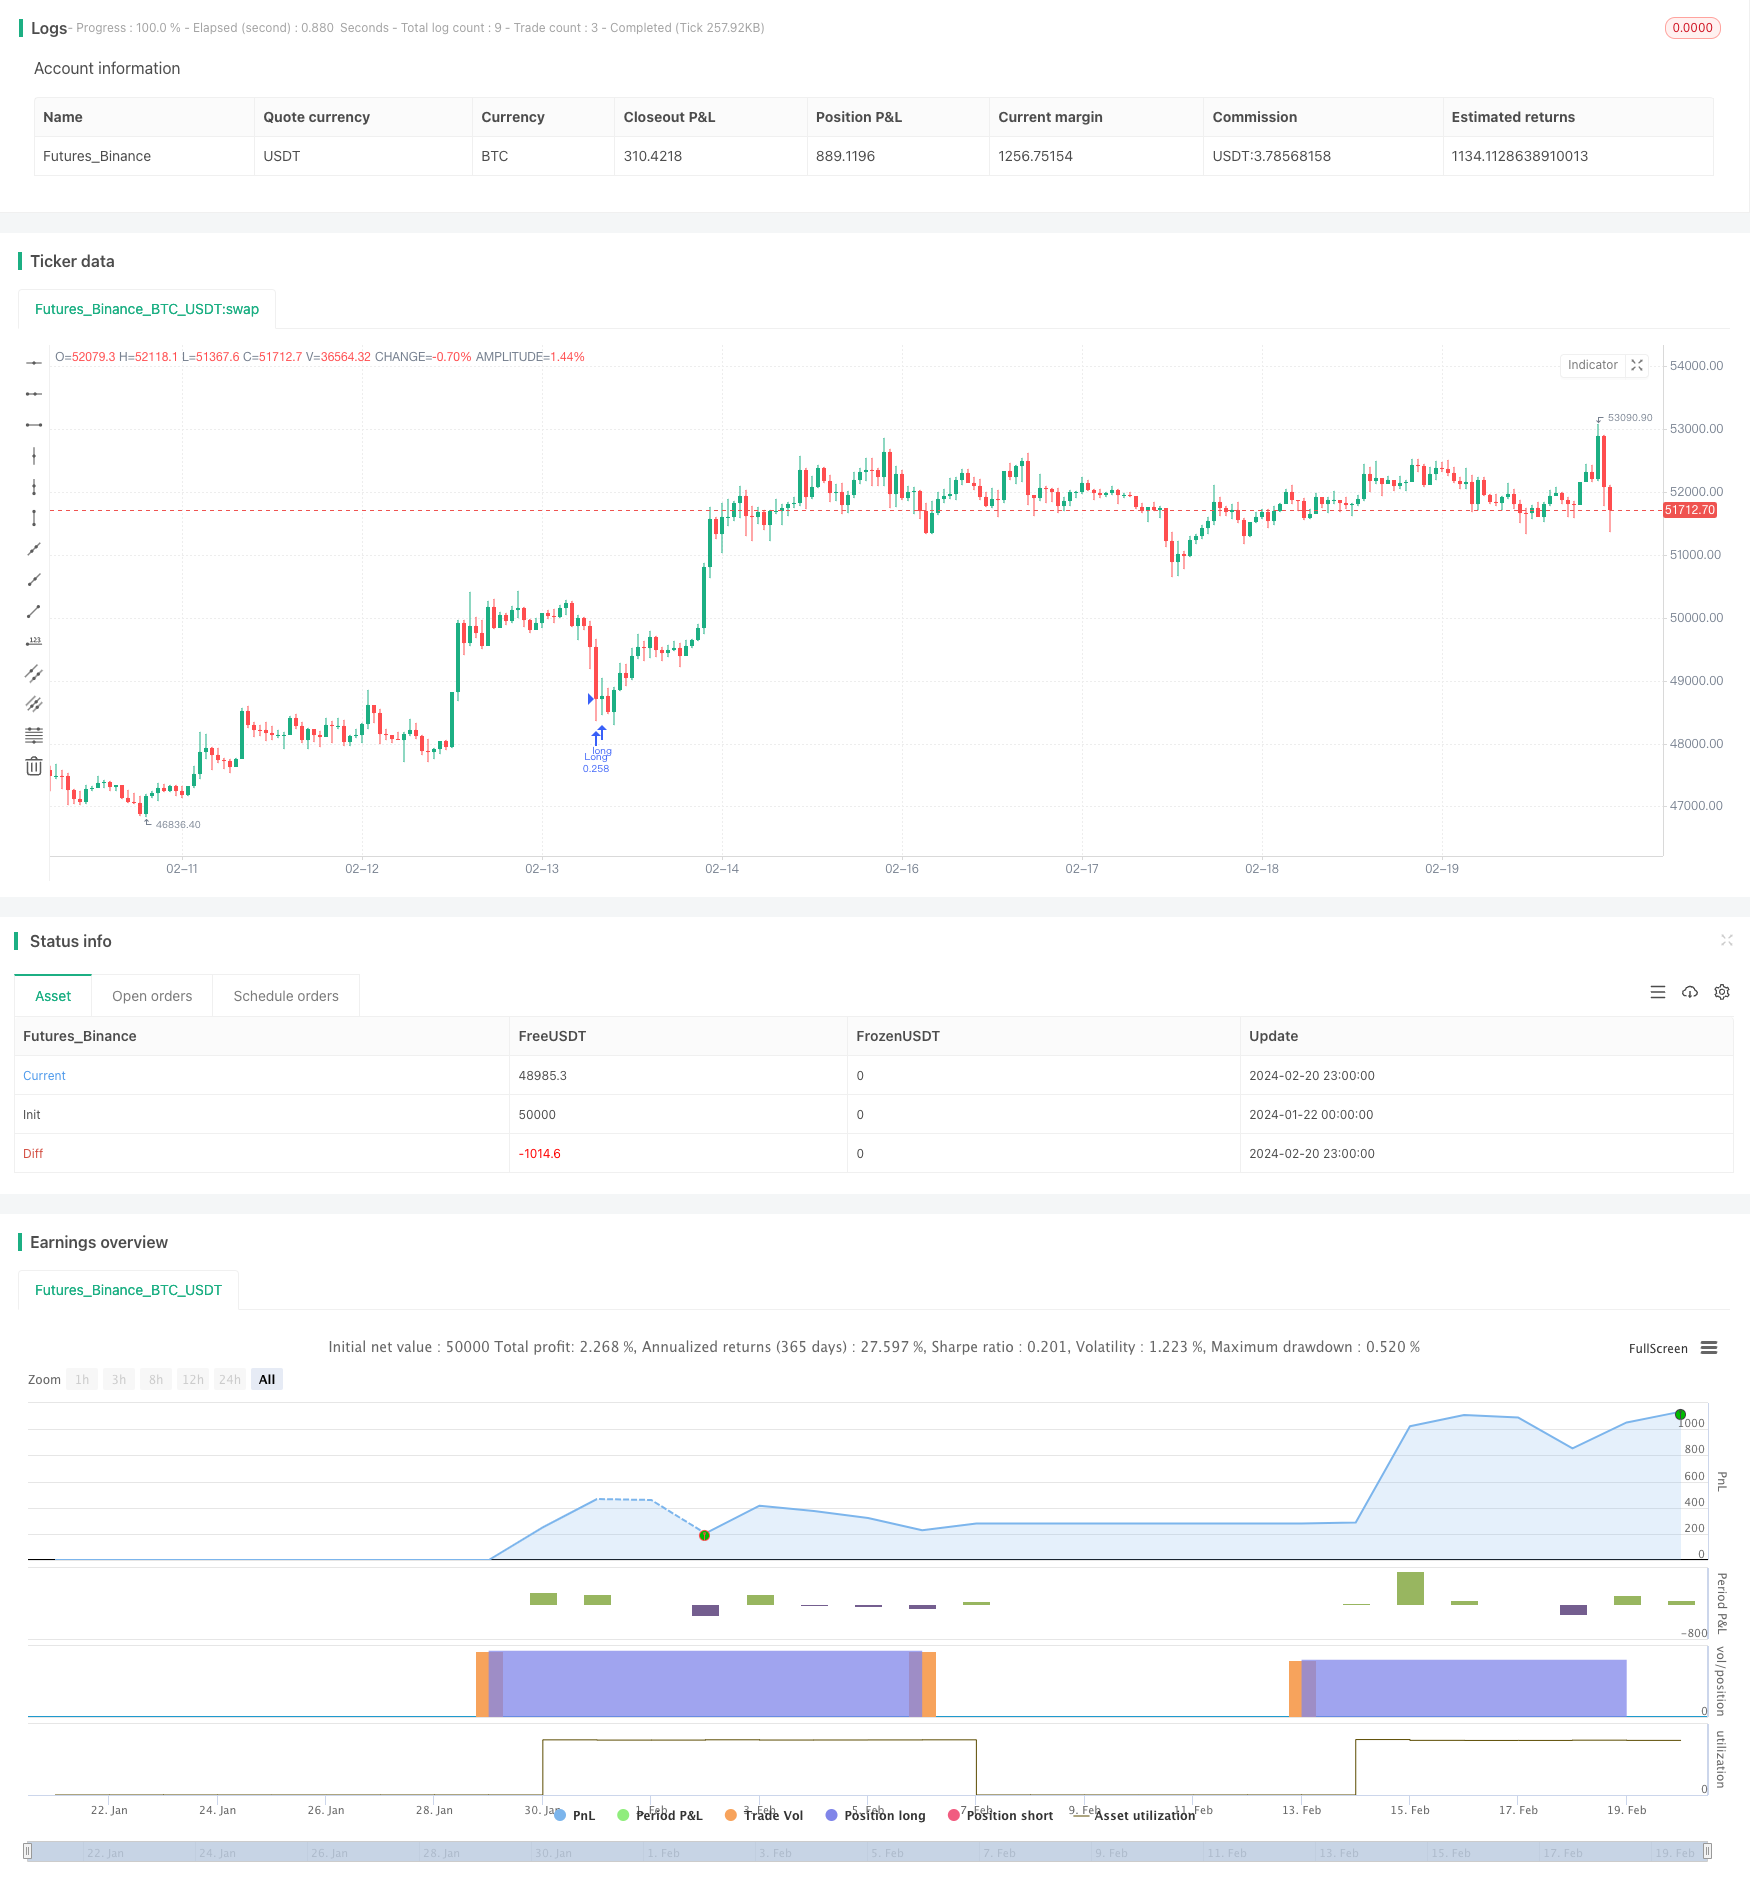
Overview
The Oscillating Breakthrough Strategy is an active trading strategy for mainstream cryptocurrencies using a 15-minute timeframe. It utilizes technical indicators to identify market trends, discover potential breakthrough points, and effectively manage risks through stop-loss settings.
Strategy Principles
The strategy employs two Simple Moving Averages (SMA50 and SMA200) to determine the market trend direction. When SMA50 crosses above SMA200, it's a bullish signal, and vice versa for bearish signals.
The Relative Strength Index (RSI) is used to judge overbought/oversold conditions. When the RSI falls below the set oversold region (default 40), it indicates a potential buy signal.
The specific trading logic is:
- RSI below 40 and close price above SMA200 constitutes the buy condition;
- Enter long position;
- Set stop loss at 5% below entry price;
- If SMA50 crosses below SMA200 and RSI goes above 50, close position to lock in profits.
The strategy is simple and straightforward, seeking potential breakthrough points through dual confirmation. The stop loss prevents losing positions from getting out of hands, while SMA crossovers act as exit signals.
Advantage Analysis
The strategy has the following advantages:
- Simple to implement;
- False breakouts filtered through dual moving averages, ensuring validity;
- RSI identifies oversold conditions for opportunities;
- Embedded stop loss to actively control risks;
- SMA crossovers as exit mechanism.
Risk Analysis
There are also some risks:
- Stop loss could be penetrated during violent market swings;
- Improper SMA periods may cause missing trends;
- Excessive time spent out of trades in bull markets impacts profits.
Improvements can be made via:
- Dynamic stop loss levels;
- SMA optimization;
- Considering more factors for holding decisions.
Summary
In summary, the Oscillating Breakthrough Strategy is a simple and practical short-term strategy. With easy operation, controllable risks etc., it suits novice crypto traders. Further optimizations can enable stable profits across more market environments.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 5 | % Stop Loss |
| v_input_1 | 90 | (?Simple Moving Average) SMA50 Length |
| v_input_2 | 170 | SMA200 Length |
| v_input_3 | 14 | (?Relative Strenght Index) RSI Length |
| v_input_4 | 40 | Oversold Level |
Source Pine Script
/*backtest
start: 2024-01-22 00:00:00
end: 2024-02-21 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Wielkieef


//@version=5
strategy("Crypto Sniper [15min]", shorttitle="ST Strategy", overlay=true, pyramiding=1, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=25, calc_on_order_fills=false, slippage=0, commission_type=strategy.commission.percent, commission_value=0.03)

sma50Length = input(90, title=" SMA50 Length", group="Simple Moving Average")
sma200Length = input(170, title=" SMA200 Length", group="Simple Moving Average")
rsiLength = input(14, title=" RSI Length", group="Relative Strenght Index")
overSoldLevel = input(40, title=" Oversold Level", group="Relative Strenght Index")
sl = input.float(5.0, '% Stop Loss', step=0.1)

rsi = ta.rsi(close, rsiLength)
sma50 = ta.sma(close, sma50Length)
sma200 = ta.sma(close, sma200Length)

longCondition = rsi < overSoldLevel and close > sma200

if (longCondition)
    strategy.entry("Long", strategy.long)

stopLossPrice = strategy.position_avg_price * (1 - sl / 100)
strategy.exit("Stop Loss", stop=stopLossPrice)

if (ta.crossunder(sma200, sma50) and rsi >= 50)
    strategy.close("Long")

Bar_color = ta.crossunder(sma200, sma50) and rsi >= 50 ? color.orange : rsi < overSoldLevel ? color.maroon : strategy.position_avg_price != 1 ? color.green : color.gray

barcolor(color=Bar_color)


//by wielkieef
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/The-Oscillating-Breakthrough-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h