Strategy vault / Trend following
Three Exponential Moving Averages and Stochastic Relative Strength Index Trading Strategy
This is a trend following strategy that combines triple exponential moving average (EMA) and Stochastic Relative Strength Index (Stoch RSI) to generate trading signals. It goes long when the fast EMA crosses above…
Overview
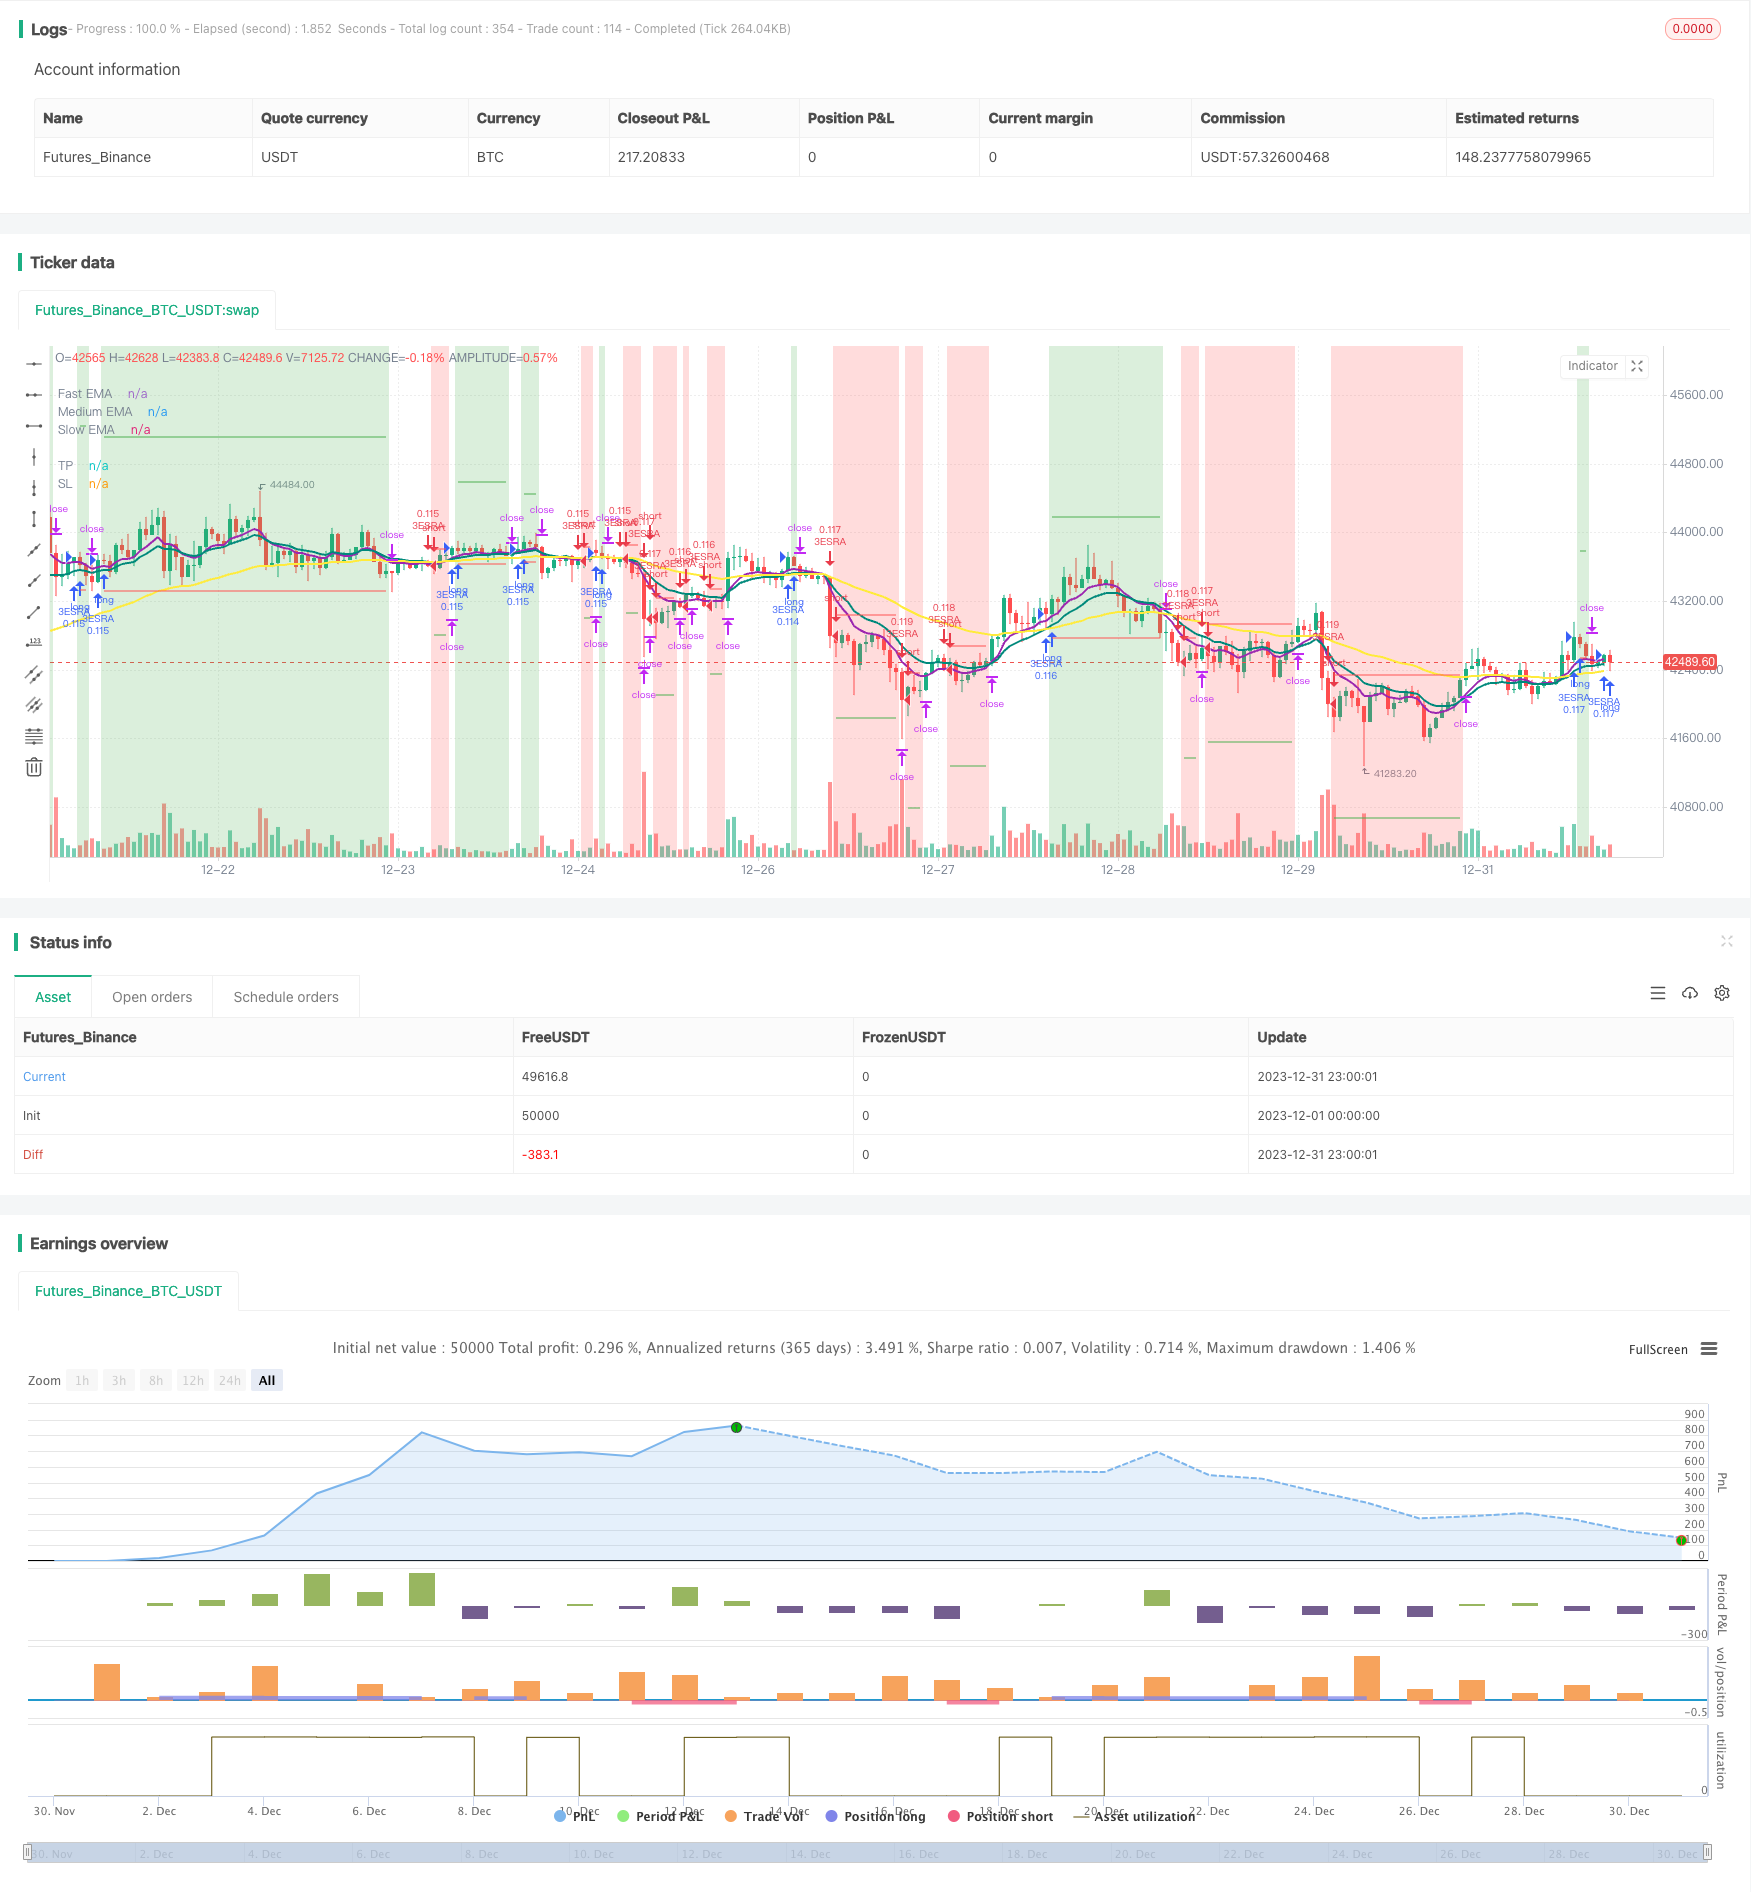
This is a trend following strategy that combines triple exponential moving average (EMA) and Stochastic Relative Strength Index (Stoch RSI) to generate trading signals. It goes long when the fast EMA crosses above the medium EMA and the medium EMA crosses above the slow EMA. It goes short when the reverse happens. The strategy also uses Stoch RSI as an auxiliary indicator.
Principles
Use 8, 14, 50 days EMAs. Going long when 8 day EMA > 14 day EMA > 50 day EMA. Going short when it's the opposite.
Use Stochastic RSI as auxiliary indicator. Calculate 14 days RSI first, then calculate Stochastics on RSI, finally calculate 3 days SMA as K line and 3 days SMA on K line as D line. K crossing over D gives long signal.
Enter long trades when close > 8 day EMA on long signal. Enter short trades when close < 8 day EMA on short signal.
Stop loss sets at 1 ATR distance below/above entry price. Take profit sets at 4 ATR distance above/below entry price.
Strengths
EMA as base indicator can track trends effectively. Triple EMA captures both short and long term trends by combing multi periods.
Adding Stoch RSI can filter false signals and increase entry accuracy.
ATR based stop loss and take profit can dynamically track market volatility, avoiding improper placement.
This strategy has well tuned parameters and performs great during trending periods. Drawdown is smaller and profit is consistent for long term trades.
Risks
Combination of multiple indicators increases whipsaw risk. Conflicting signals between EMA and Stoch RSI may cause entering at bad levels. Prices trend itself needs monitoring in such cases.
Conservative stop loss and take profit settings could be violated by huge market swings, causing premature exits missing further trends. Adjusting ATR parameters or increasing SL/TP multiples may help.
Triple EMA setup has certain lag when fast and medium lines reversing. Prices trend itself needs monitoring to decide entries.
This strategy favors trending market. Sideway markets would not perform well. Adjusting MA periods or adding other auxiliary indicators may help.
Enhancements
Add indicators like MACD for better entries. Testing different periods combination of MAs.
Optimizing long/short testing parameters on ATR. Such as adjusting stop loss from 1 ATR to 1.5 ATR, take profit from 4 ATR to 3 ATR for better results.
Removing Stoch RSI and keeping just MAs for filtering noises and more stable profits.
Adding more criteria judging the trend, like trading volumes, to operate under significant levels.
Conclusion
This strategy combines triple EMA and Stoch RSI to determine trends. Strict entry signals reduce unnecessary trades. Dynamic SL and TP based on ATR makes parameters adaptive. Backtests show great results during trending periods with smaller drawdowns and consistent profits. Further optimizations could lead to even better results.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_10_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_1 | true | (?Backtesting range)Start Date |
| v_input_2 | true | Start Month |
| v_input_3 | 1900 | Start Year |
| v_input_4 | true | End Date |
| v_input_5 | true | End Month |
| v_input_6 | 2040 | End Year |
| v_input_7 | 8 | (?EMAs)Fast EMA |
| v_input_8 | 14 | Medium EMA |
| v_input_9 | 50 | Slow EMA |
| v_input_11 | 3 | (?Stoch-RSI)K |
| v_input_12 | 3 | D |
| v_input_13 | 14 | RSI Length |
| v_input_14 | 14 | Stochastic Length |
| v_input_15_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_16 | 14 | (?ATR)Length |
| v_input_17 | 0 | Smoothing: RMA | SMA | EMA | WMA |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//              3ESRA
//              v0.2a

// Coded by Vaida Bogdan

// 3ESRA consists of a 3 EMA cross + a close above (for longs) the quickest EMA
// or below (for shorts). Note that I've deactivated the RSI Cross Over/Under
// (you can modify the code and activate it). The strategy also uses a stop loss
// that's at 1 ATR distance from the entry price and a take profit that's at
// 4 times the ATR distance from the entry price.

// Feedback:
// Tested BTCUSDT Daily
// 1. Stoch-RSI makes you miss opportunities.
// 2. Changing RR to 4:1 times ATR works better.

//@version=4
strategy(title="3 EMA + Stochastic RSI + ATR", shorttitle="3ESRA", overlay=true, pyramiding=1,
     process_orders_on_close=true, calc_on_every_tick=true,
     initial_capital=1000, currency = currency.USD, default_qty_value=10,
     default_qty_type=strategy.percent_of_equity,
     commission_type=strategy.commission.percent, commission_value=0.1, slippage=2)

startDate = input(title="Start Date", type=input.integer,
     defval=1, minval=1, maxval=31, group="Backtesting range")
startMonth = input(title="Start Month", type=input.integer,
     defval=1, minval=1, maxval=12, group="Backtesting range")
startYear = input(title="Start Year", type=input.integer,
     defval=1900, minval=1800, maxval=2100, group="Backtesting range")
endDate = input(title="End Date", type=input.integer,
     defval=1, minval=1, maxval=31, group="Backtesting range")
endMonth = input(title="End Month", type=input.integer,
     defval=1, minval=1, maxval=12, group="Backtesting range")
endYear = input(title="End Year", type=input.integer,
     defval=2040, minval=1800, maxval=2100, group="Backtesting range")

// Date range filtering
inDateRange = (time >= timestamp(syminfo.timezone, startYear, startMonth, startDate, 0, 0)) and
     (time < timestamp(syminfo.timezone, endYear, endMonth, endDate, 23, 59))

fast = input(8, minval=8, title="Fast EMA", group="EMAs")
medium = input(14, minval=8, title="Medium EMA", group="EMAs")
slow = input(50, minval=8, title="Slow EMA", group="EMAs")
src = input(close, title="Source")

smoothK = input(3, "K", minval=1, group="Stoch-RSI", inline="K&D")
smoothD = input(3, "D", minval=1, group="Stoch-RSI", inline="K&D")
lengthRSI = input(14, "RSI Length", minval=1, group="Stoch-RSI", inline="length")
lengthStoch = input(14, "Stochastic Length", minval=1, group="Stoch-RSI", inline="length")
rsiSrc = input(close, title="RSI Source", group="Stoch-RSI")

length = input(title="Length", defval=14, minval=1, group="ATR")
smoothing = input(title="Smoothing", defval="RMA", options=["RMA", "SMA", "EMA", "WMA"], group="ATR")

// EMAs
fastema = ema(src, fast)
mediumema = ema(src, medium)
slowema = ema(src, slow)

// S-RSI
rsi1 = rsi(rsiSrc, lengthRSI)
k = sma(stoch(rsi1, rsi1, rsi1, lengthStoch), smoothK)
d = sma(k, smoothD)
sRsiCrossOver = k[1] < d[1] and k > d
sRsiCrossUnder = k[1] > d[1] and k < d

// ATR
ma_function(source, length) =>
	if smoothing == "RMA"
		rma(source, length)
	else
		if smoothing == "SMA"
			sma(source, length)
		else
			if smoothing == "EMA"
				ema(source, length)
			else
				wma(source, length)
atr = ma_function(tr(true), length)

// Trading Logic
longCond1 = (fastema > mediumema) and (mediumema > slowema)
longCond2 = true
// longCond2 = sRsiCrossOver
longCond3 = close > fastema
longCond4 = strategy.position_size <= 0
longCond = longCond1 and longCond2 and longCond3 and longCond4 and inDateRange

shortCond1 = (fastema < mediumema) and (mediumema < slowema)
shortCond2 = true
// shortCond2 = sRsiCrossUnder
shortCond3 = close < fastema
shortCond4 = strategy.position_size >= 0
shortCond = shortCond1 and shortCond2 and shortCond3 and shortCond4 and inDateRange

var takeProfit = float(na), var stopLoss = float(na)
if longCond and strategy.position_size <= 0
    takeProfit := close + 4*atr
    stopLoss := close - 1*atr
    // takeProfit := close + 2*atr
    // stopLoss := close - 3*atr

else if shortCond and strategy.position_size >= 0
    takeProfit := close - 4*atr
    stopLoss := close + 1*atr
    // takeProfit := close - 2*atr
    // stopLoss := close + 3*atr

// Strategy calls
strategy.entry("3ESRA", strategy.long, comment="Long", when=longCond and strategy.position_size <= 0)
strategy.entry("3ESRA", strategy.short, comment="Short", when=shortCond and strategy.position_size >= 0)
strategy.exit(id="TP-SL", from_entry="3ESRA", limit=takeProfit, stop=stopLoss)
if (not inDateRange)
    strategy.close_all()

// Plot EMAs
plot(fastema, color=color.purple, linewidth=2, title="Fast EMA")
plot(mediumema, color=color.teal, linewidth=2, title="Medium EMA")
plot(slowema, color=color.yellow, linewidth=2, title="Slow EMA")
// Plot S-RSI
// plotshape((strategy.position_size > 0) ? na : sRsiCrossOver, title="StochRSI Cross Over", style=shape.triangleup, location=location.belowbar, color=color.teal, text="SRSI", size=size.small)
// Plot trade
bgcolor(strategy.position_size > 0 ? color.new(color.green, 75) : strategy.position_size < 0 ? color.new(color.red,75) : color(na))
// Plot Strategy
plot((strategy.position_size != 0) ? takeProfit : na, style=plot.style_linebr, color=color.green, title="TP")
plot((strategy.position_size != 0) ? stopLoss : na, style=plot.style_linebr, color=color.red, title="SL")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-30. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Three-Exponential-Moving-Averages-and-Stochastic-Relative-Strength-Index-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h
- Price Divergence Based Trend Trading StrategyPine Script · Trend following · 2h
- SuperTrend Trading Strategy with Multiple FiltersPine Script · Trend following · 1h
- Three EMA Stochastic RSI Crossover Golden Cross StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m