Strategy vault / Machine learning
Three Line Code Implements Argos Machine Learnings Rapid Interpretation of Industry News with a Counter Pointing Strategy
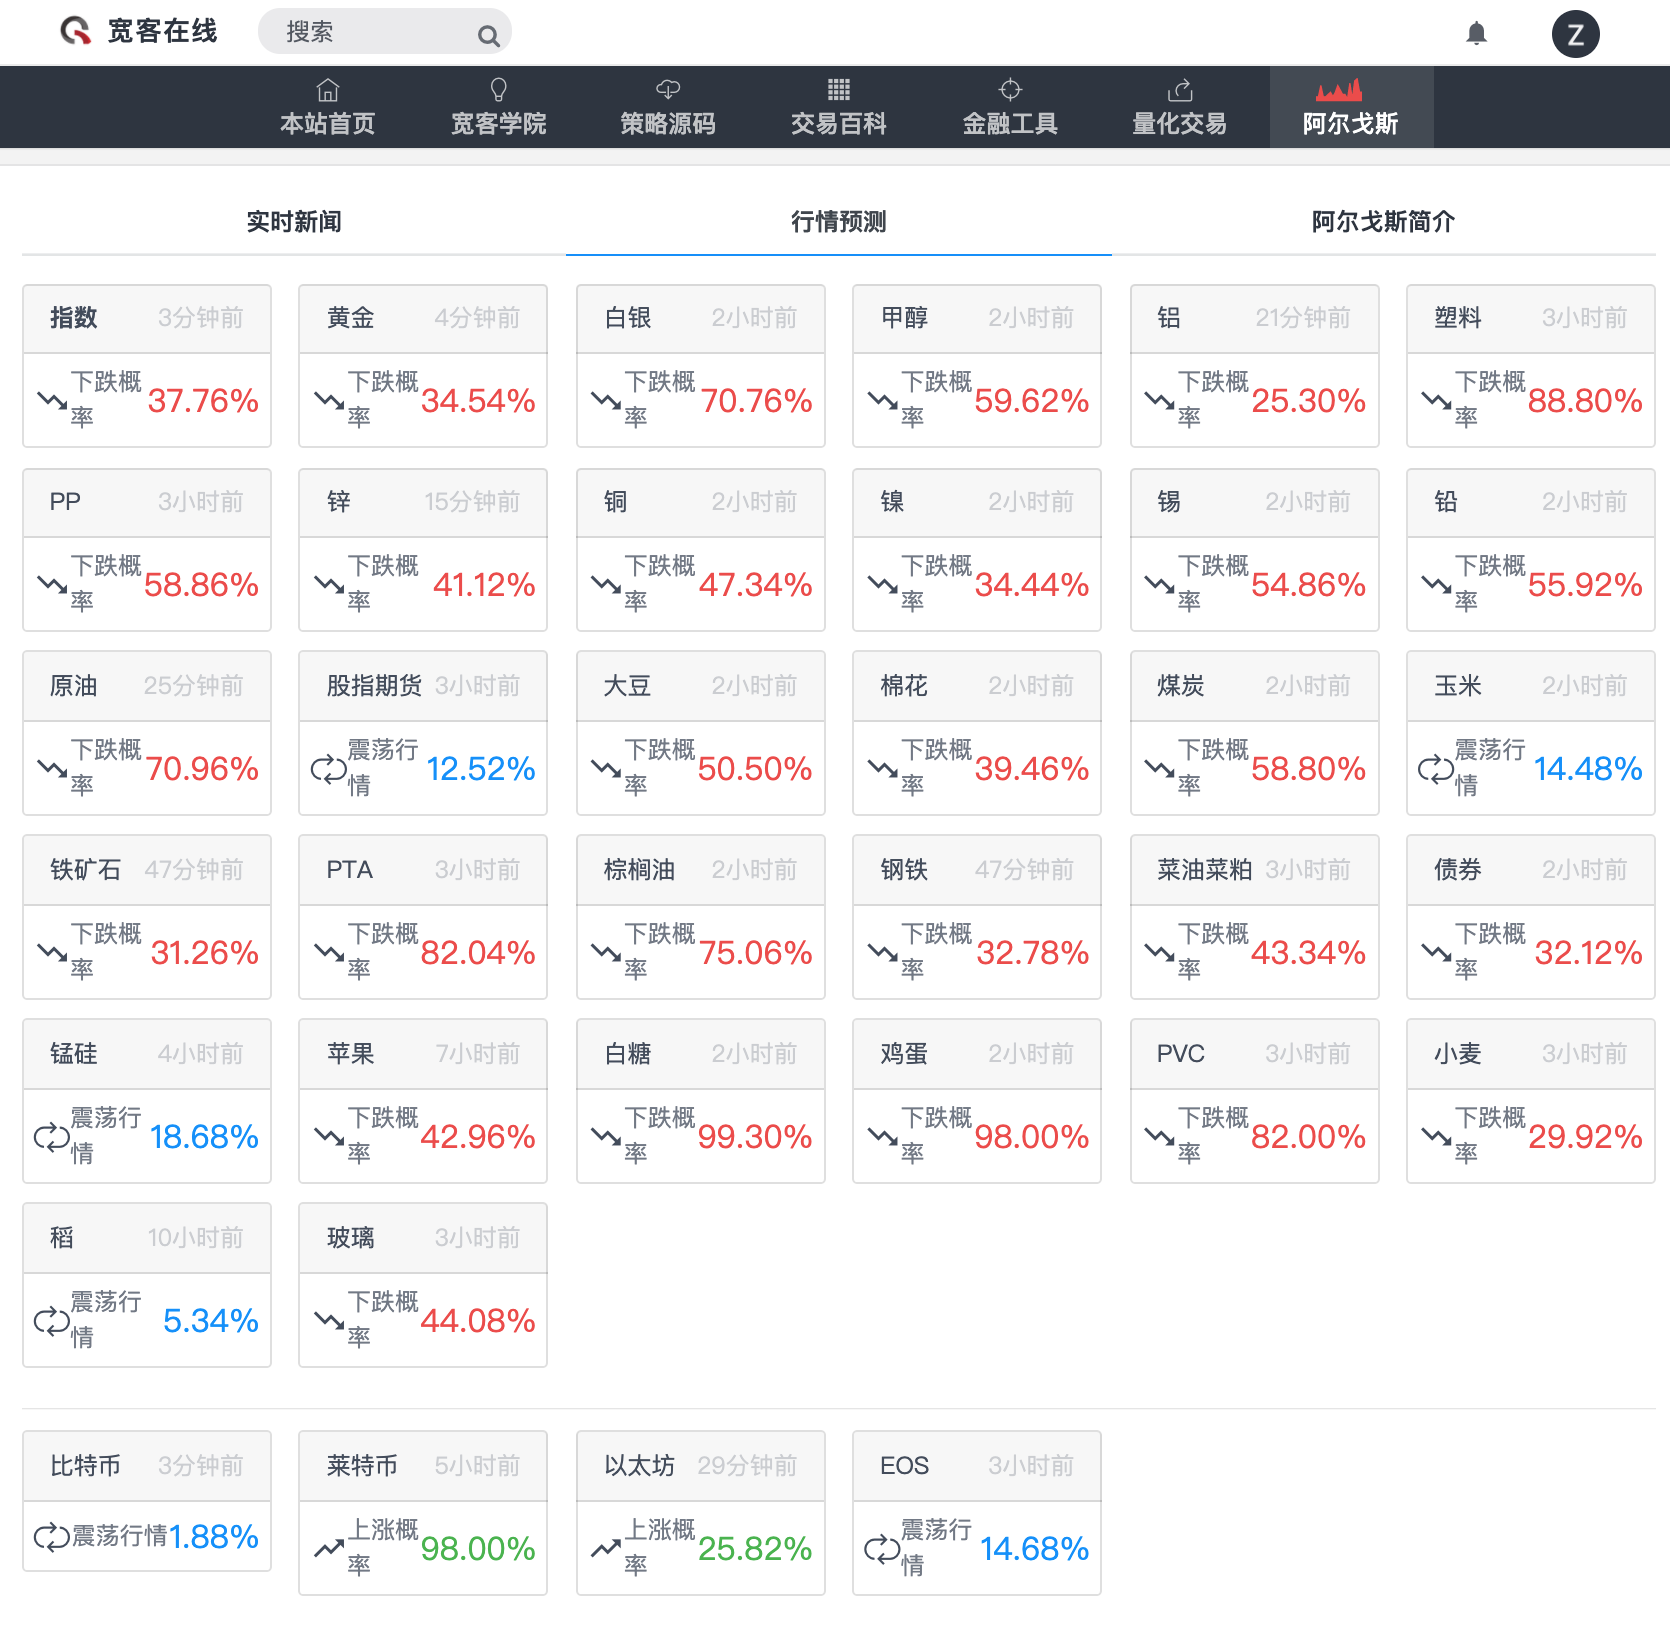
Argos https://www.quantinfo.com/Argus/ Notes Argus (Argus Ἄργος) The hundred-eyed giant from Greek mythology This system is a project of Quant Online, a subsidiary of the inventor. After five years of research and…
Argos
https://www.quantinfo.com/Argus/
Notes
Argus (Argus Ἄργος) The hundred-eyed giant from Greek mythology This system is a project of Quant Online, a subsidiary of the inventor. After five years of research and development, the entire network monitors price fluctuations and related information in futures, stocks, options, commodities, foreign exchange, etc. Uses the most cutting-edge AI neural networks currently in technology, trained hundreds of millions of times It can predict effective stock order quotations, predict financial asset price changes, predict S&P 500 index volatility, optimize investment portfolios, and predict price fluctuations based on news headlines.
Implementation
Although the bullshit is fine, the embarrassing fact proves that it is better to counter-point with Argos, which uses AI technology. If it predicts a rise, we will sell, and if it predicts a fall, we will buy. When others are greedy I am fearful, when others are fearful I am greedy, because it predicts public sentiment; to make money, you have to go against the crowd.
Strategy
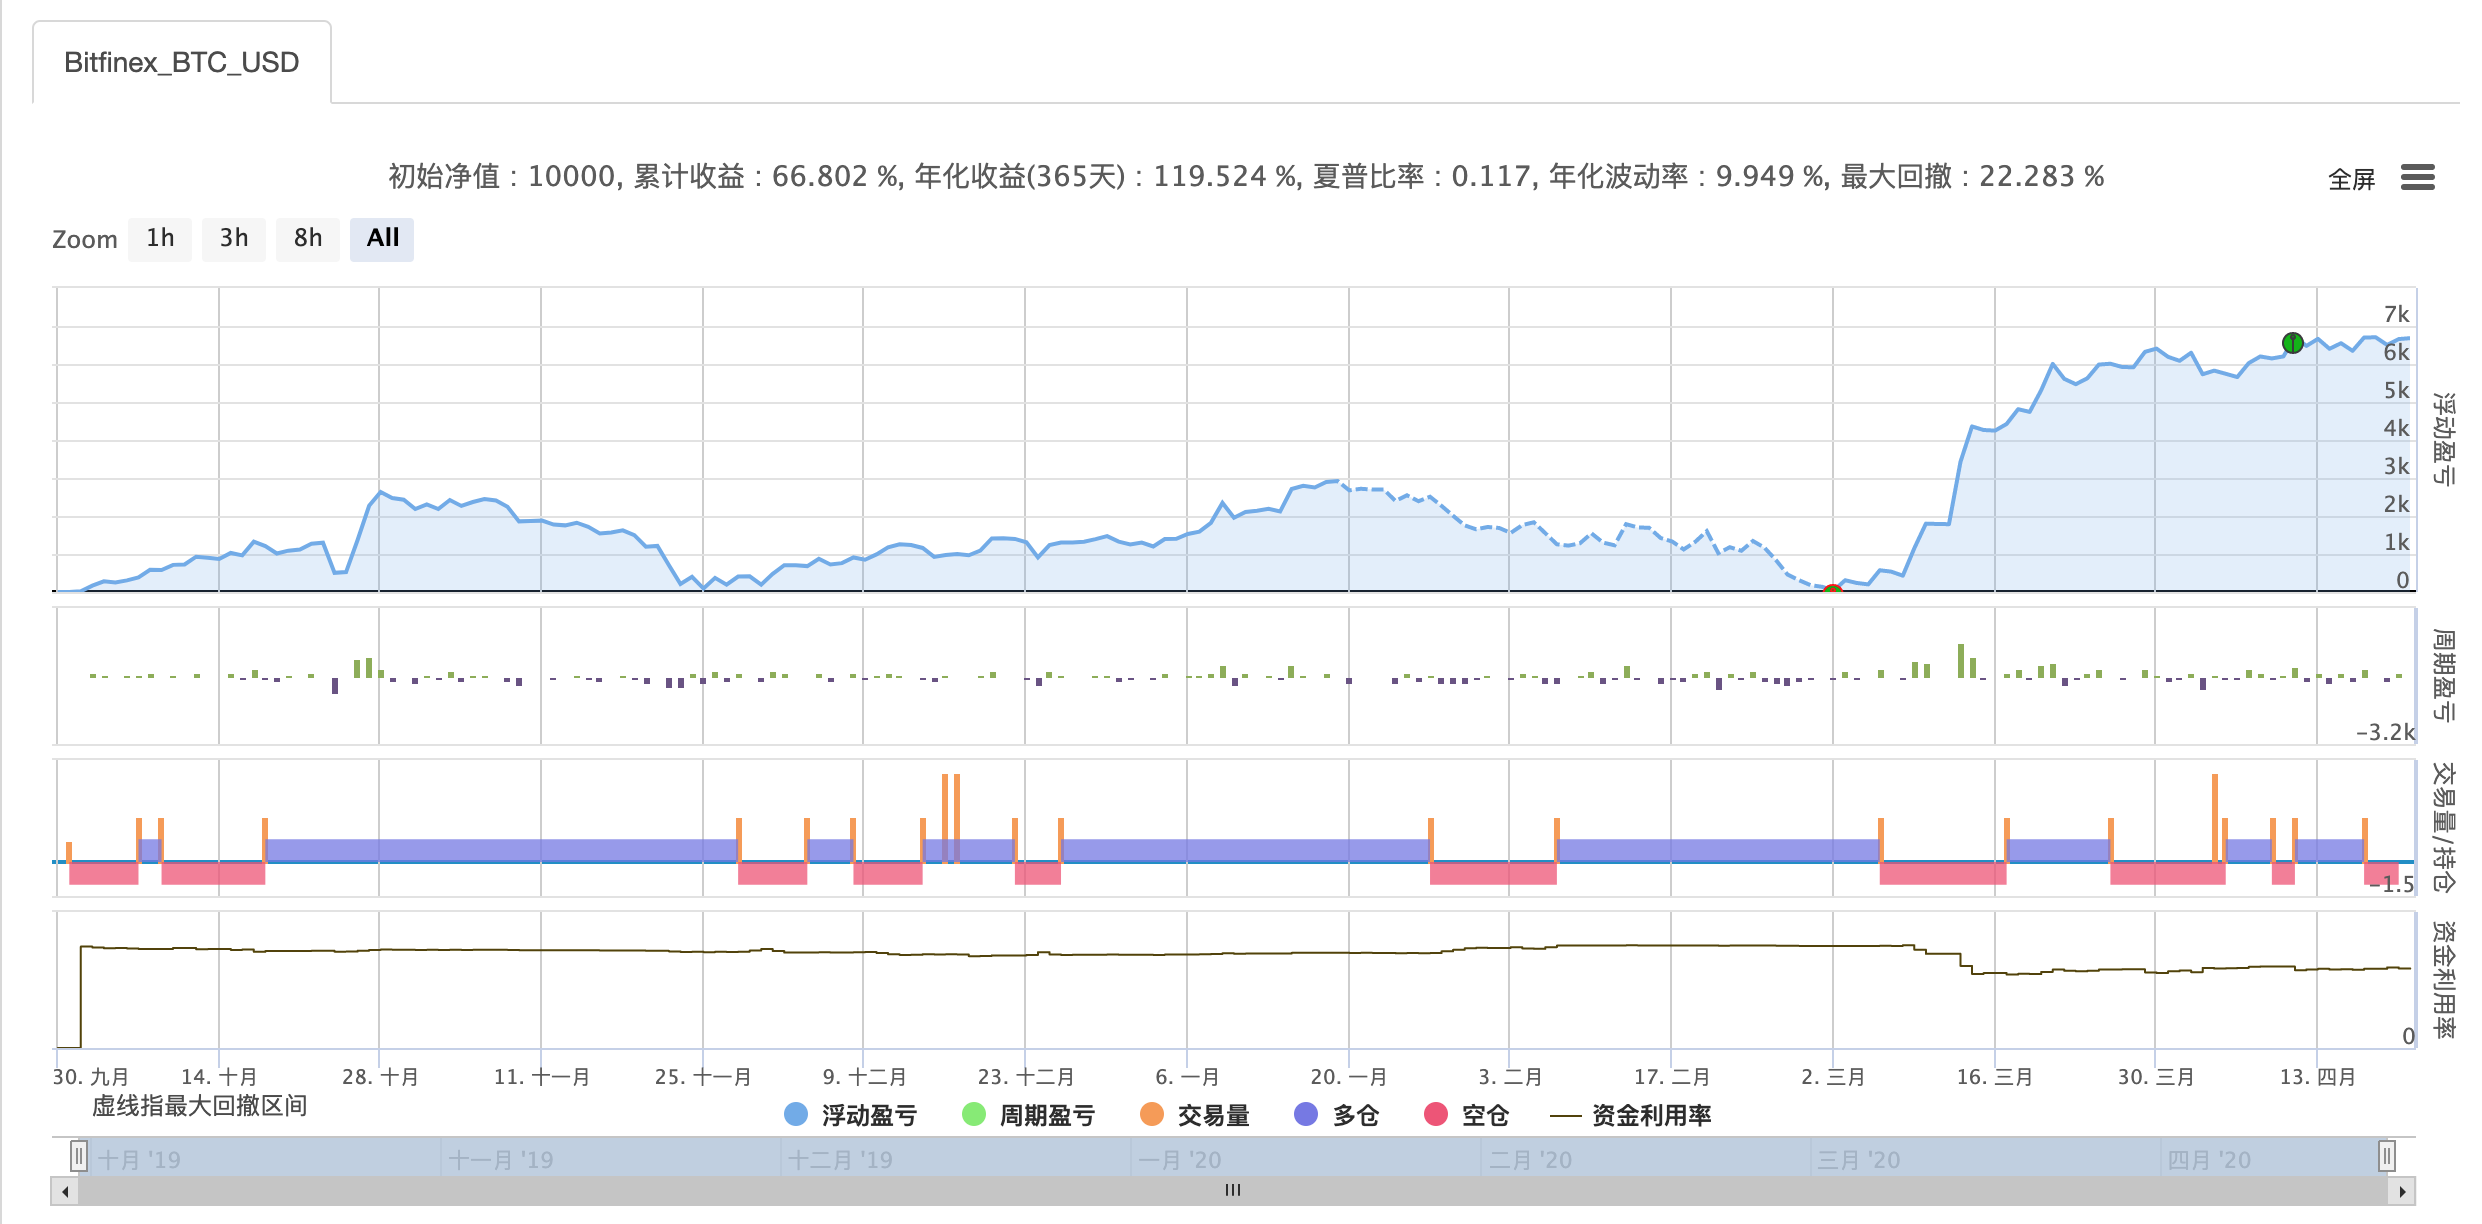
With the help of the powerful syntax support of the inventor platform, in order to display the most intuitive effect, the enhanced version of My language is selected. The data source returns a decimal from 0 to 1 to describe the probability of increase. If the user needs to obtain data of other varieties, just modify the name of the variety in the URL of the strategy code.
Results
Finally
If you want to define your own third-party data source, ReferenceAPI https://www.fmz.com/api#exchange.getdata This strategy only demonstrates how to call third-party data sources for backtesting and verification. Do not conduct live trading!!!
Source MyLanguage
(*backtest
start: 2019-10-01 00:00:00
end: 2020-04-21 23:59:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Bitfinex","currency":"BTC_USD"}]
*)

Predicted value: DATA('https://www.quantinfo.com/API/Argus/history?symbol=Bitcoin');
Predicted value>HV(predicted value, 5)&&predicted value>0.6,SPK;
Predicted value < LV(predicted value, 10) && predicted value<0.4,BPK;
Published by Zero on the FMZ strategy square · last modified 2020-04-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Three-Line-Code-Implements-Argos-Machine-Learnings-Rapid-Interpretation-of-Industry-News-with-a-Counter-Pointing-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- Double Decker RSI Trading StrategyPine Script · Machine learning · 1h
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d