Strategy vault / Machine learning
Trading Strategy Based on Standard Deviation of Trading Volume
This strategy builds a trading volume model using moving average and standard deviation of trading volume, and determines the trend direction with the moving average of price to generate trading signals when volume…
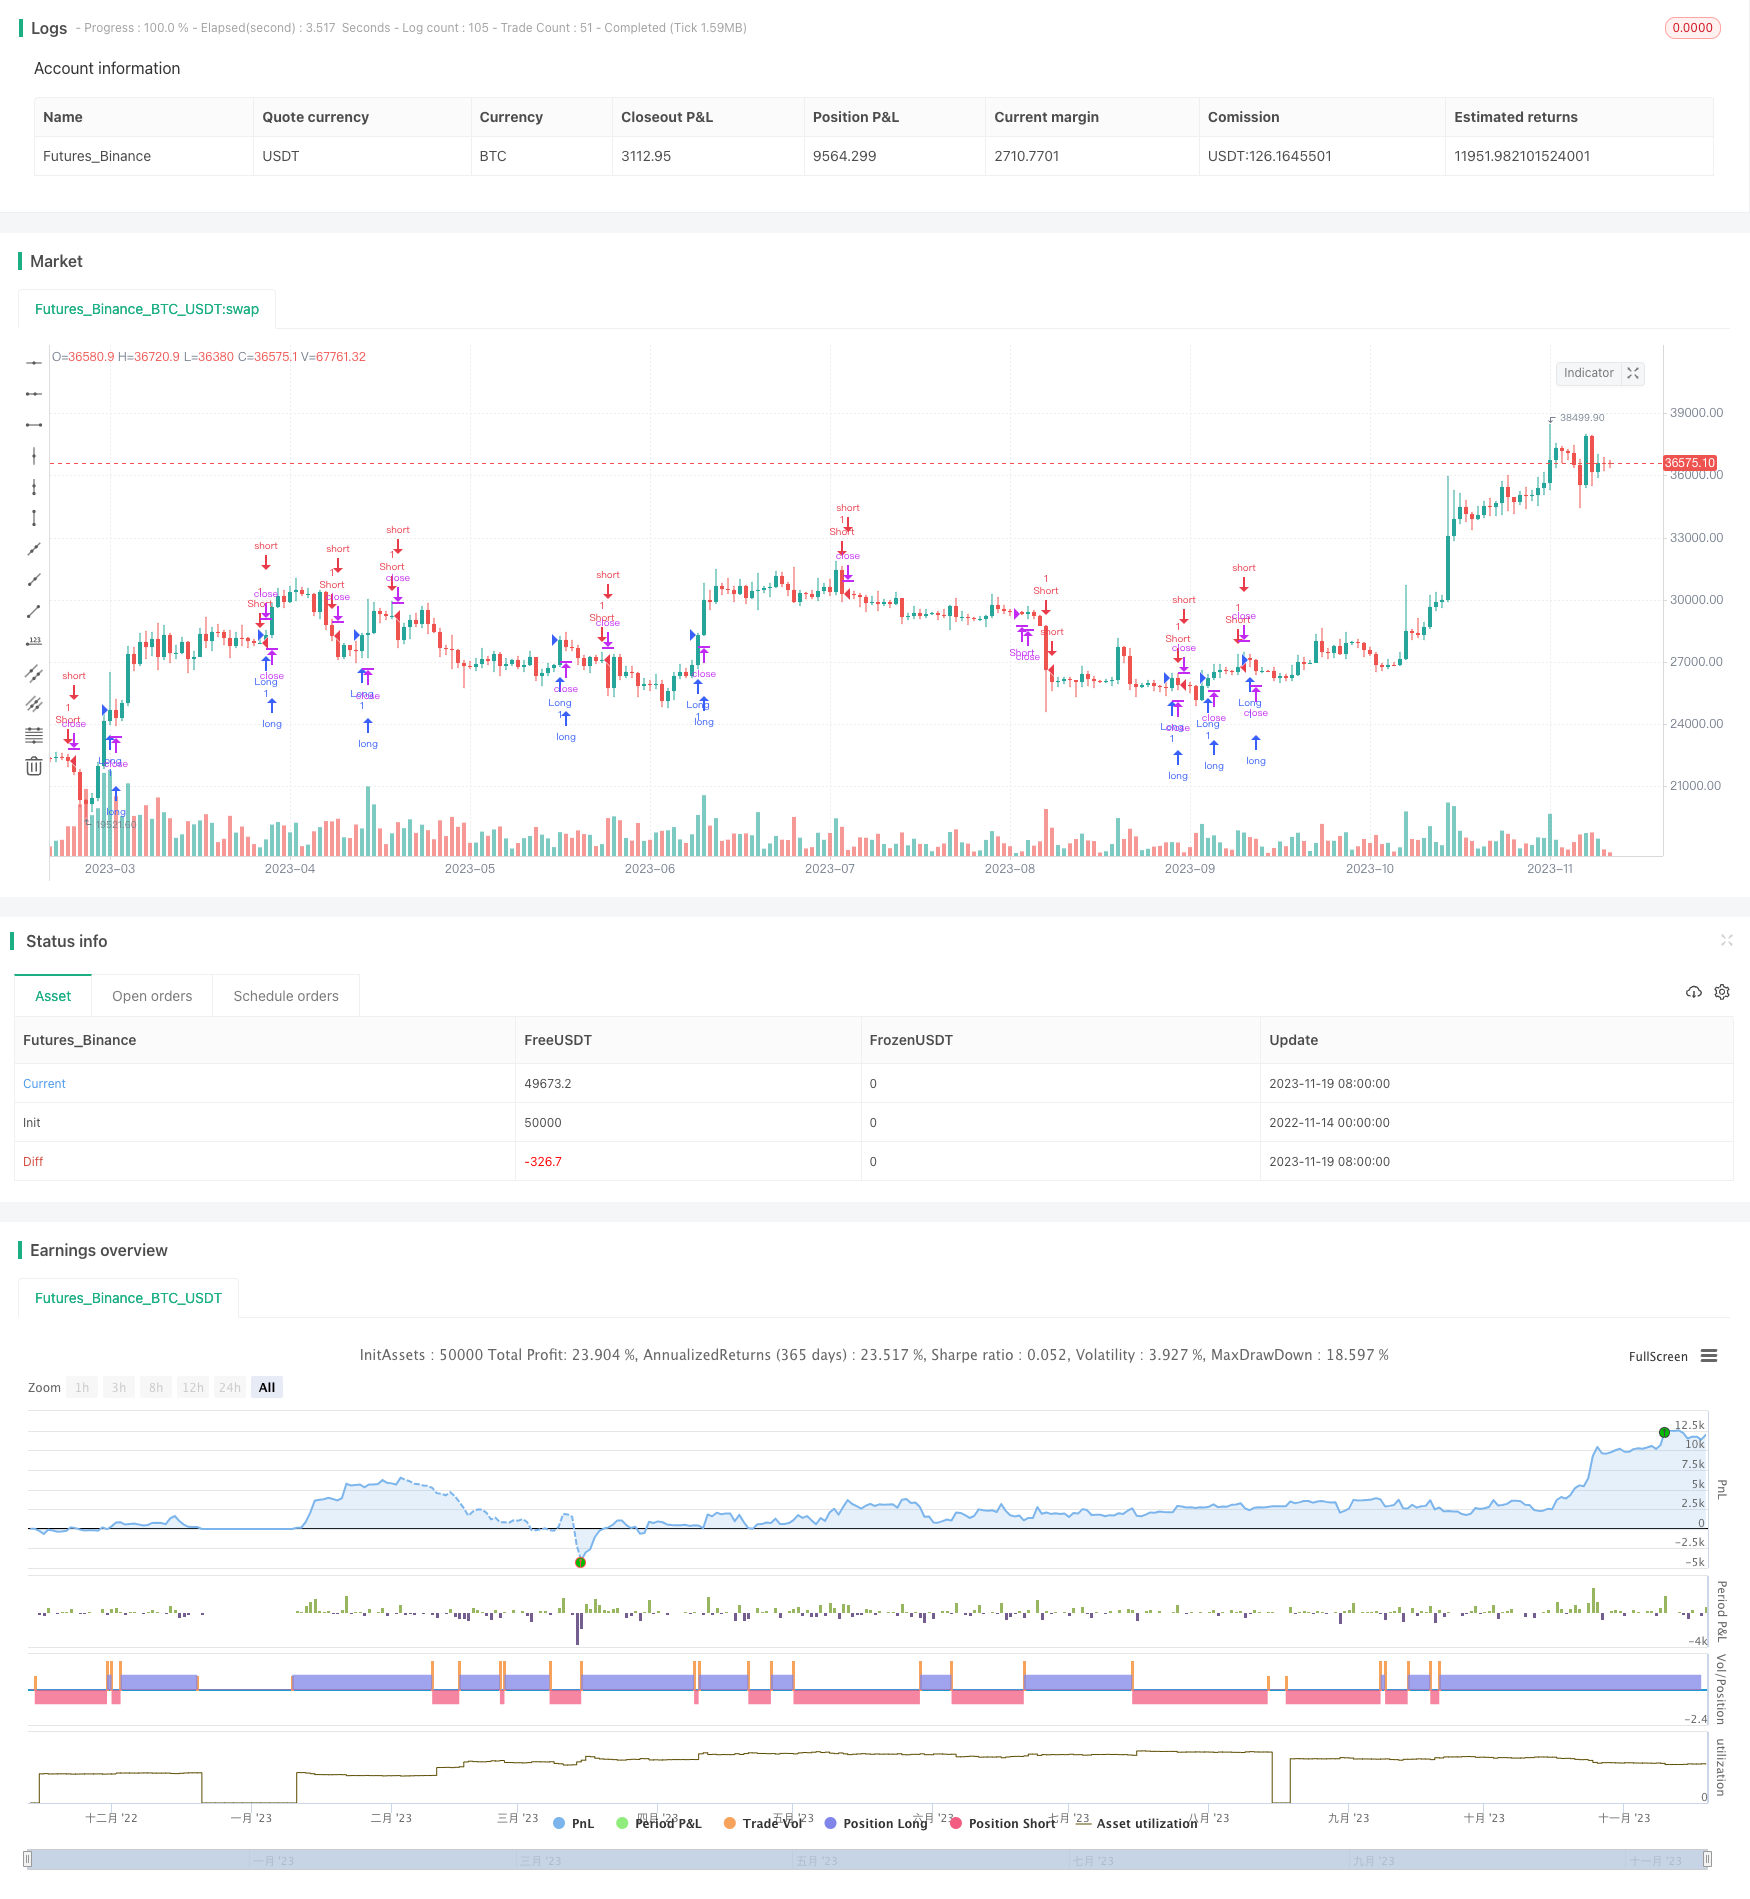
Overview
This strategy builds a trading volume model using moving average and standard deviation of trading volume, and determines the trend direction with the moving average of price to generate trading signals when volume is normal. It also sets upper and lower limits for trading volume to avoid wrong signals when volume is abnormal.
Strategy Logic
The core logic is to build trading volume model and judge price trend.
- Build trading volume model
- Calculate the 40-period moving average of volume vavg as the baseline
- Calculate the 40-period standard deviation of volume vsd as the normal fluctuation range
- Calculate the 5-period moving average of volume vavgn as the latest volume level
- Set lower limit of volume lowlimit as vavg minus 1 times vsd
- Set upper limit of volume uplimit as vavg plus 2 times vsd
- Judge price trend
- Calculate the 20-period moving average of close price mavg as the indicator of price trend
- Generate trading signals
- When mavg crosses above its previous day and vavgn is above lowlimit, go long
- When mavg crosses below its previous day and vavgn is above lowlimit, go short
- Close position when mavg trend reverses
The strategy combines trading volume model and price trend to avoid chasing price trends when volume is abnormal, which can filter out some false signals.
Advantage Analysis
- Combining volume changes to judge price trend can filter out some false signals and make the trading signals more reliable
- Building trading volume model using standard deviation avoids extreme volume impact
- Adjustable parameters of moving average can adapt to price changes in different cycles
Risk Analysis
- Volume and price may diverge in short term, leading to missing price trends
- Improper parameter settings of volume may cause model failure
- No stop loss in the strategy may lead to large losses
Solutions:
- Adjust moving average parameters properly to optimize the model
- Add stop loss logic to control single loss
Optimization Directions
- Add more indicators to judge price trend to make signals more reliable
- Increase machine learning module to train parameters of volume and price models based on data
- Add stop loss logic to prevent excessive single loss
- Optimize entry logic to ensure higher probability of catching trends
- Combine indicators like ATR to automatically adjust stop loss distance
Summary
The overall logic of this strategy is clear, using volume to avoid chasing false trends and the entry signals are relatively reliable. But the strategy itself is simple with large room for expansion. By adding more indicators, machine learning, stop loss and other modules, it can further improve the stability and ability to catch trends. This is a typical trend chasing strategy. After optimization, it can become a very practical quantitative strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | options |
| v_input_2 | 40 | length |
| v_input_3 | 5 | nlow |
| v_input_4 | true | factor |
Source Pine Script
/*backtest
start: 2022-11-14 00:00:00
end: 2023-11-20 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © dongyun

//@version=4
strategy("Volume bottom standard deviation system", overlay=true)

options = input(1,'')
length = input(40,'')
nlow = input(5,'')
factor = input(1.0,'')

vavg = 0.0
vavgn = 0.0
vsd = 0.0
lowlimit = 0.0
uplimit = 0.0
mavg = 0.0
aror = 0.0
adjvol = 0.0
savevol = 0.0


//Find average volume, replacing bad values
adjvol := volume

if (volume != 0)
	savevol := volume
else
	savevol := savevol[1]
	adjvol := savevol


// Replace high volume days because they distort standard deviation
if (adjvol > 2 * factor * nz(vsd[1]))
	adjvol := savevol
else
	adjvol := adjvol[1]

vavg := sma(adjvol,length)
vsd := stdev(adjvol,length)
vavgn := sma(adjvol,nlow)

// Extreme volume limits
lowlimit := vavg - factor * vsd
uplimit := vavg + 2 * factor * vsd

// System rules based on moving average trend
mavg := sma(close,length/2)

// Only enter on new trend signals
if (options == 2)
	if (mavg > mavg[1] and mavg[1] <= mavg[2])
		strategy.entry("Long", strategy.long)
	if (mavg<mavg[1] and mavg[1]>=mavg[2])
		strategy.entry("Short", strategy.short)
else
	if (mavg > mavg[1] and vavgn > lowlimit)
		strategy.entry("Long", strategy.long)
	if (mavg < mavg[1] and vavgn > lowlimit)
		strategy.entry("Short", strategy.short)

// Exit on low volume
if (options != 1)
	if (mavg<mavg[1] or (strategy.position_size > 0 and vavgn<= lowlimit))
		strategy.close("Long")
	if (mavg>mavg[1] or (strategy.position_size > 0 and vavgn<= lowlimit))
		strategy.close("Short")
else
	if (mavg < mavg[1])
		strategy.close("Long")
	if (mavg > mavg[1])
strategy.close("Short")Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trading-Strategy-Based-on-Standard-Deviation-of-Trading-Volume.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- High Frequency Hybrid Technical Analysis Quantitative StrategyPine Script · Machine learning · 15m
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h
- kNN based Trend Following StrategyPine Script · Machine learning · 1h