Strategy vault / Machine learning
Trailing Stop Loss Strategy Based on Price Gaps
This strategy adopts the price gap principle to go long when price breaks recent lows, with stop loss and take profit orders to trail the lowest price for profit taking.
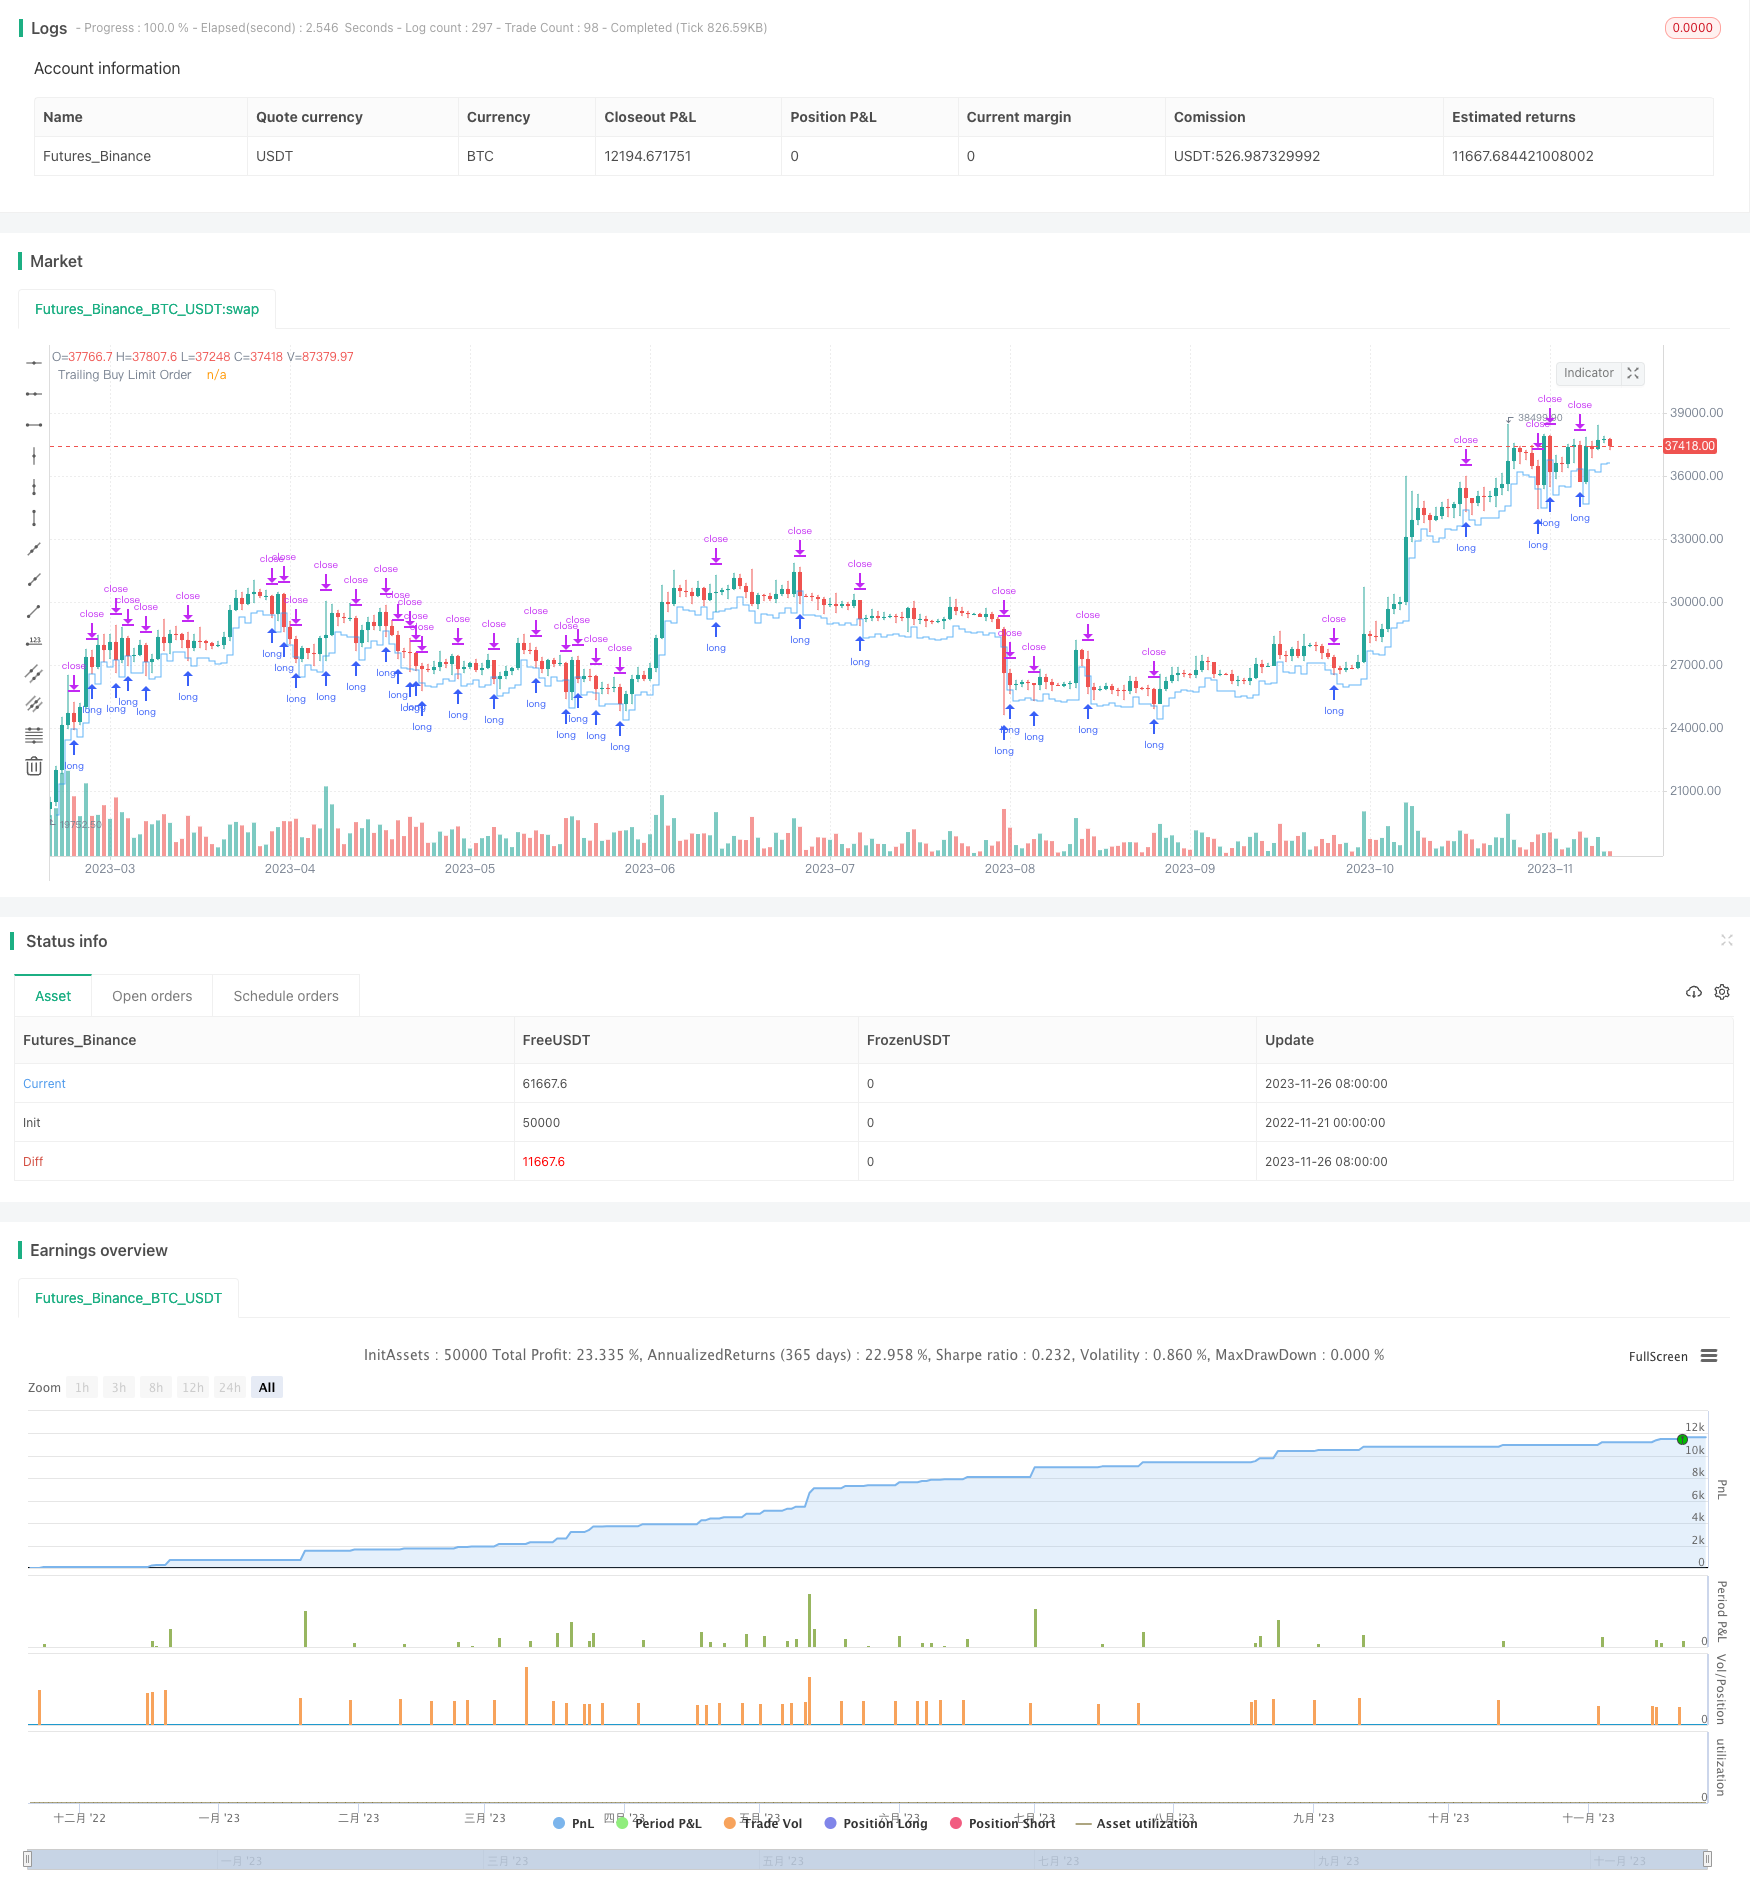
Overview
This strategy adopts the price gap principle to go long when price breaks recent lows, with stop loss and take profit orders to trail the lowest price for profit taking.
Strategy Logic
It identifies gaps when price breaks below the lowest price in recent N hours, goes long based on configured percentage, with stop loss and take profit orders. Stop loss line and take profit line move according to price action. The logic is:
- Calculate lowest price in recent N hours as binding price
- Go long when realtime price is below binding price * buy percent
- Set take profit based on entry price * sell percent
- Set stop loss based on entry price - entry price * stop loss percent
- Position size is percent of strategy equity
- Trail stop loss line with lowest price
- Close position when take profit or stop loss is triggered
Advantage Analysis
The advantages of this strategy:
- Utilize price gap concept, improve winning rate
- Automatic trailing stop loss to lock in most profits
- Customizable stop loss and take profit percentage for different markets
- Works well for instruments with obvious rebounds
- Simple logic and easy to implement
Risk Analysis
There are also some risks:
- Breakout of gaps may fail with lower lows
- Improper stop loss or take profit settings may cause premature exit
- Require periodic parameter tuning for market changes
- Limited applicable instruments, may not work for some
- Manual intervention needed from time to time
Optimization Directions
The strategy can be improved in the following aspects:
- Add machine learning models for automatic parameter tuning
- Add more types of stop loss/take profit, e.g. trailing stop loss, bracket orders
- Optimize stop loss/take profit logic for smarter exits
- Incorporate more indicators to filter out false signals
- Expand to more instruments to improve universality
Conclusion
In conclusion, this is a simple and effective trailing stop loss strategy based on price gaps. It reduces false entries and locks in profits effectively. There is still much room for improvements in parameters tuning and signal filtering. It is worth further research and refinement.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 3 | (?Squeeze Settings)Buy, % |
| v_input_2 | true | Sell, % |
| v_input_3 | true | Stop Loss, % |
| v_input_4 | true | Max Bars To Sell |
| v_input_5 | 2 | maxBars |
| v_input_6_close | 0 | Bind: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_7 | true | (?Backtesting Period)Fixed Range |
| v_input_8 | 0 | rangeStart: 1 Week | 12 Hours | 24 Hours | 48 Hours | 6 Hours | 2 Weeks | 1 Month | Maximum |
| v_input_9 | timestamp(01 Aug 2021 00:00 +0000) | Backtesting Start |
| v_input_10 | timestamp(01 Aug 2022 00:00 +0000) | Backtesting End |
Source Pine Script
/*backtest
start: 2022-11-21 00:00:00
end: 2023-11-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

strategy(title="Squeeze Backtest by Shaqi v1.0", overlay=true, pyramiding=0, currency="USD", process_orders_on_close=true, commission_type=strategy.commission.percent, commission_value=0.075, default_qty_type=strategy.percent_of_equity, default_qty_value=100, initial_capital=100, backtest_fill_limits_assumption=0)
strategy.risk.allow_entry_in(strategy.direction.long)

R0 = "6 Hours"
R1 = "12 Hours"
R2 = "24 Hours"
R3 = "48 Hours"
R4 = "1 Week"
R5 = "2 Weeks"
R6 = "1 Month"
R7 = "Maximum"


buyPercent = input( title="Buy, %",         type=input.float,   defval=3,       minval=0.01,                        step=0.01,  inline="Percents",  group="Squeeze Settings") * 0.01
sellPercent = input(title="Sell, %",        type=input.float,   defval=1,       minval=0.01,                        step=0.01,  inline="Percents",  group="Squeeze Settings") * 0.01
stopPercent = input(title="Stop Loss, %",   type=input.float,   defval=1,       minval=0.01,        maxval=100,     step=0.01,  inline="Percents",  group="Squeeze Settings") * 0.01
isMaxBars = input(  title="Max Bars To Sell",               type=input.bool,    defval=true ,                                   inline="MaxBars",   group="Squeeze Settings")
maxBars = input(    title="",       type=input.integer, defval=2,     minval=0,           maxval=1000, step=1,                  inline="MaxBars",   group="Squeeze Settings")
bind = input(       title="Bind",           type=input.source,  defval=close,                                                                       group="Squeeze Settings")
isRange = input(    title="Fixed Range",               type=input.bool,    defval=true,                                         inline="Range",     group="Backtesting Period")
rangeStart = input( title="",                       defval=R4,      options=[R0, R1, R2, R3, R4, R5, R6, R7],                   inline="Range",     group="Backtesting Period")
periodStart = input(title="Backtesting Start", type=input.time,    defval=timestamp("01 Aug 2021 00:00 +0000"),                                     group="Backtesting Period")
periodEnd = input(  title="Backtesting End",   type=input.time,    defval=timestamp("01 Aug 2022 00:00 +0000"),                                     group="Backtesting Period")

int startDate = na
int endDate = na
if isRange
    if rangeStart == R0
        startDate := timenow - 21600000
        endDate := timenow
    else if rangeStart == R1
        startDate := timenow - 43200000
        endDate := timenow
    else if rangeStart == R2
        startDate := timenow - 86400000
        endDate := timenow
    else if rangeStart == R3
        startDate := timenow - 172800000
        endDate := timenow
    else if rangeStart == R4
        startDate := timenow - 604800000
        endDate := timenow
    else if rangeStart == R5
        startDate := timenow - 1209600000
        endDate := timenow
    else if rangeStart == R6
        startDate := timenow - 2592000000
        endDate := timenow
    else if rangeStart == R7
        startDate := time
        endDate := timenow
else
    startDate := periodStart
    endDate := periodEnd

afterStartDate = (time >= startDate)
beforeEndDate = (time <= endDate)
notInTrade = strategy.position_size == 0
inTrade = strategy.position_size > 0

barsFromEntry = barssince(strategy.position_size[0] > strategy.position_size[1])
entry = strategy.position_size[0] > strategy.position_size[1]
entryBar = barsFromEntry == 0
notEntryBar = barsFromEntry != 0
buyLimitPrice = bind - bind * buyPercent
buyLimitFilled = low <= buyLimitPrice
sellLimitPriceEntry = buyLimitPrice * (1 + sellPercent)
sellLimitPrice = strategy.position_avg_price * (1 + sellPercent)

stopLimitPriceEntry = buyLimitPrice - buyLimitPrice * stopPercent
stopLimitPrice = strategy.position_avg_price - strategy.position_avg_price * stopPercent

if afterStartDate and beforeEndDate and notInTrade
    strategy.entry("BUY", true, limit = buyLimitPrice)
    strategy.exit("INSTANT", limit = sellLimitPriceEntry, stop = stopLimitPriceEntry)
strategy.cancel("INSTANT", when = inTrade)
if isMaxBars
    strategy.close("BUY", when = barsFromEntry >= maxBars, comment = "Don't Sell")
strategy.exit("SELL", limit = sellLimitPrice, stop = stopLimitPrice)

showStop = stopPercent <= 0.03

plot(showStop ? stopLimitPrice : na, title="Stop Loss Limit Order", style=plot.style_linebr, color=color.red, linewidth=1)
plot(sellLimitPrice, title="Take Profit Limit Order", style=plot.style_linebr, color=color.purple, linewidth=1)
plot(strategy.position_avg_price, title="Buy Order Filled Price", style=plot.style_linebr, color=color.blue, linewidth=1)
plot(buyLimitPrice, title="Trailing Buy Limit Order", style=plot.style_stepline, color=color.new(color.blue, 30), offset=1)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trailing-Stop-Loss-Strategy-Based-on-Price-Gaps.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- Double Decker RSI Trading StrategyPine Script · Machine learning · 1h
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d