Strategy vault / Trend following
Trend Following RSI and Moving Average Combined Quantitative Trading Strategy
This strategy is a trend following trading system that combines the Relative Strength Index (RSI) and Simple Moving Average (SMA). It identifies market trend direction using moving averages while confirming momentum…
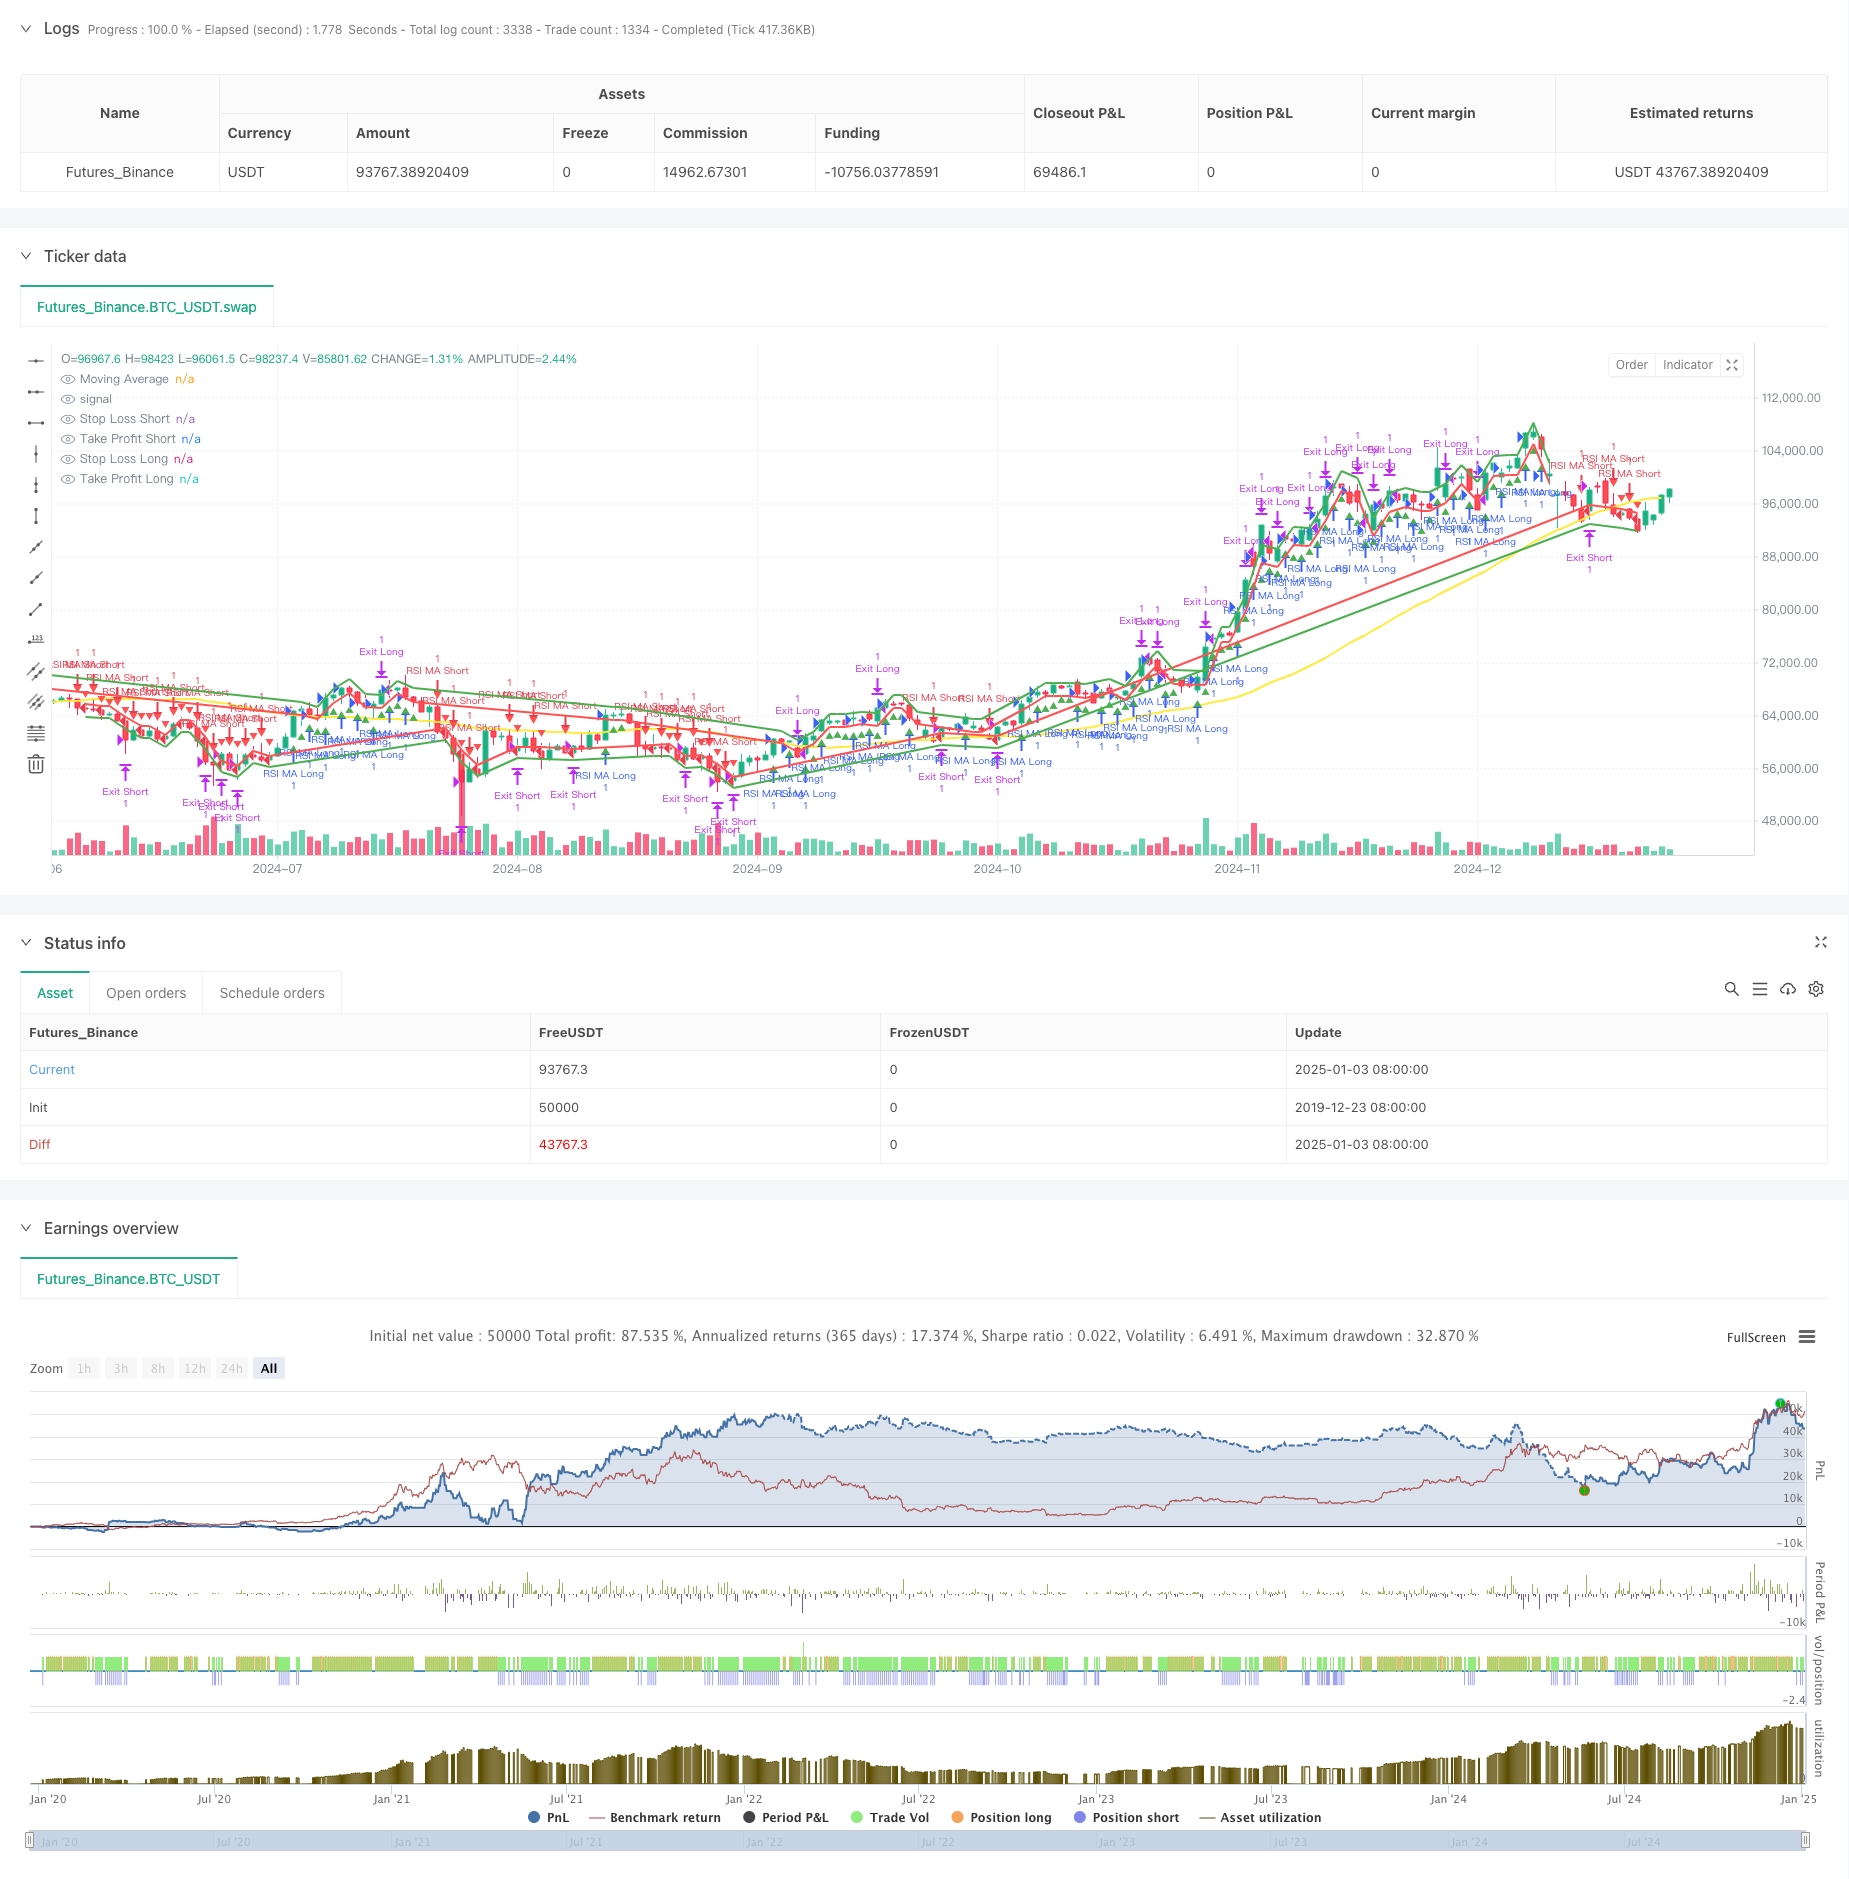
Overview
This strategy is a trend following trading system that combines the Relative Strength Index (RSI) and Simple Moving Average (SMA). It identifies market trend direction using moving averages while confirming momentum with RSI, executing trades when trend and momentum align. The strategy includes comprehensive stop-loss and take-profit mechanisms for effective risk control.
Strategy Principle
The core logic is based on the combination of two technical indicators:
- Moving Average (MA): Used to determine overall trend. A bullish trend is identified when price is above MA, bearish when below.
- Relative Strength Index (RSI): Used to confirm price momentum. Upward momentum is confirmed when RSI exceeds a threshold (e.g., 55), downward momentum when below threshold (e.g., 45).
Trading signal generation logic:
- Long conditions: Price above MA and RSI above buy threshold
- Short conditions: Price below MA and RSI below sell threshold
Risk control employs percentage-based stop-loss and take-profit levels, set as fixed percentages of entry price.
Strategy Advantages
- Signal stability: Reduces false signals through dual confirmation of trend and momentum
- Comprehensive risk management: Fixed percentage stop-loss and take-profit effectively control risk per trade
- Parameter flexibility: Key parameters like MA period and RSI thresholds can be optimized for different market characteristics
- Clear strategy logic: Trading rules are simple and intuitive to understand and execute
- High adaptability: Applicable to various trading timeframes
Strategy Risks
- Trend reversal risk: Consecutive stops may occur at trend turning points
- Range-bound market risk: Frequent trading losses possible in sideways markets
- Parameter dependency: Optimal parameters may vary significantly across market environments
- Slippage risk: Significant slippage possible during high volatility
- Technical indicator lag: MA and RSI have inherent lag, potentially delaying entry timing
Strategy Optimization Directions
- Dynamic parameter optimization: Introduce adaptive parameter mechanisms adjusting MA period and RSI thresholds based on market volatility
- Market environment filtering: Add volatility filtering mechanism to adjust position sizing or pause trading in high volatility
- Multiple timeframe analysis: Incorporate longer timeframe trend confirmation to improve directional accuracy
- Stop-loss optimization: Implement trailing stops for better profit protection
- Signal filtering: Add volume and other auxiliary indicators to improve signal reliability
Summary
This strategy constructs a logically clear and risk-controlled trading system by combining trend and momentum indicators. While inherent risks exist, the strategy demonstrates good practicality through appropriate parameter settings and risk control. Future optimization focuses on dynamic parameter adjustment, market environment recognition, and signal quality improvement, potentially enhancing strategy stability and profitability.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-04 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © raiford87

//@version=6
strategy("RSI + MA Trend Strategy (v6)",
     shorttitle="RSI_MA_Trend_v6",
     overlay=true,
     initial_capital=50000,
     default_qty_type=strategy.fixed,
     default_qty_value=1)

// ─────────────────────────────────────────────────────────────────────────────────────
// 1. USER INPUTS
// ─────────────────────────────────────────────────────────────────────────────────────
maLength       = input.int(50,   "Moving Average Length")
rsiLength      = input.int(14,   "RSI Length")
rsiBuyLevel    = input.int(55,   "RSI > X for Buy",  minval=1, maxval=99)
rsiSellLevel   = input.int(45,   "RSI < X for Sell", minval=1, maxval=99)

stopLossPerc   = input.float(1.0,  "Stop Loss %",    minval=0.1)
takeProfitPerc = input.float(2.0,  "Take Profit %",  minval=0.1)

// ─────────────────────────────────────────────────────────────────────────────────────
// 2. INDICATOR CALCULATIONS
// ─────────────────────────────────────────────────────────────────────────────────────
maValue = ta.sma(close, maLength)
rsiVal  = ta.rsi(close, rsiLength)

// Trend conditions
bullTrend = close > maValue
bearTrend = close < maValue

// RSI conditions
rsiBull   = rsiVal > rsiBuyLevel
rsiBear   = rsiVal < rsiSellLevel

// ─────────────────────────────────────────────────────────────────────────────────────
// 3. ENTRY CONDITIONS
// ─────────────────────────────────────────────────────────────────────────────────────
longCondition  = bullTrend and rsiBull
shortCondition = bearTrend and rsiBear

if longCondition
    strategy.entry("RSI MA Long", strategy.long)
if shortCondition
    strategy.entry("RSI MA Short", strategy.short)

// ─────────────────────────────────────────────────────────────────────────────────────
// 4. STOP LOSS & TAKE PROFIT
// ─────────────────────────────────────────────────────────────────────────────────────
stopLossLevel   = stopLossPerc   * 0.01
takeProfitLevel = takeProfitPerc * 0.01

if strategy.position_size > 0
    stopPriceLong = strategy.position_avg_price * (1 - stopLossLevel)
    tpPriceLong   = strategy.position_avg_price * (1 + takeProfitLevel)
    strategy.exit("Exit Long", from_entry="RSI MA Long", stop=stopPriceLong, limit=tpPriceLong)

if strategy.position_size < 0
    stopPriceShort = strategy.position_avg_price * (1 + stopLossLevel)
    tpPriceShort   = strategy.position_avg_price * (1 - takeProfitLevel)
    strategy.exit("Exit Short", from_entry="RSI MA Short", stop=stopPriceShort, limit=tpPriceShort)

// ─────────────────────────────────────────────────────────────────────────────────────
// 5. PLOT SIGNALS & LEVELS
// ─────────────────────────────────────────────────────────────────────────────────────
plot(maValue, color=color.yellow, linewidth=2, title="Moving Average")

plotchar(longCondition,  title="Long Signal",  char='▲', location=location.belowbar, color=color.green, size=size.tiny)
plotchar(shortCondition, title="Short Signal", char='▼', location=location.abovebar, color=color.red,   size=size.tiny)

// Plot Stop & TP lines
posIsLong  = strategy.position_size > 0
posIsShort = strategy.position_size < 0

plotStopLong = posIsLong ? strategy.position_avg_price * (1 - stopLossLevel) : na
plotTpLong   = posIsLong ? strategy.position_avg_price * (1 + takeProfitLevel): na
plotStopShort= posIsShort? strategy.position_avg_price * (1 + stopLossLevel) : na
plotTpShort  = posIsShort? strategy.position_avg_price * (1 - takeProfitLevel): na

plot(plotStopLong,  color=color.red,   linewidth=2, style=plot.style_line, title="Stop Loss Long")
plot(plotTpLong,    color=color.green, linewidth=2, style=plot.style_line, title="Take Profit Long")
plot(plotStopShort, color=color.red,   linewidth=2, style=plot.style_line, title="Stop Loss Short")
plot(plotTpShort,   color=color.green, linewidth=2, style=plot.style_line, title="Take Profit Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-RSI-and-Moving-Average-Combined-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crypto RSI Mini Sniper Quick Response Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d