Strategy vault / Trend following
Trend Following Strategy Based on EMA and SMA Crossover
The "Trend Following Strategy Based on EMA and SMA Crossover" is a trend-following trading strategy based on the crossover of Exponential Moving Averages (EMAs) and Simple Moving Averages (SMAs). This strategy aims…
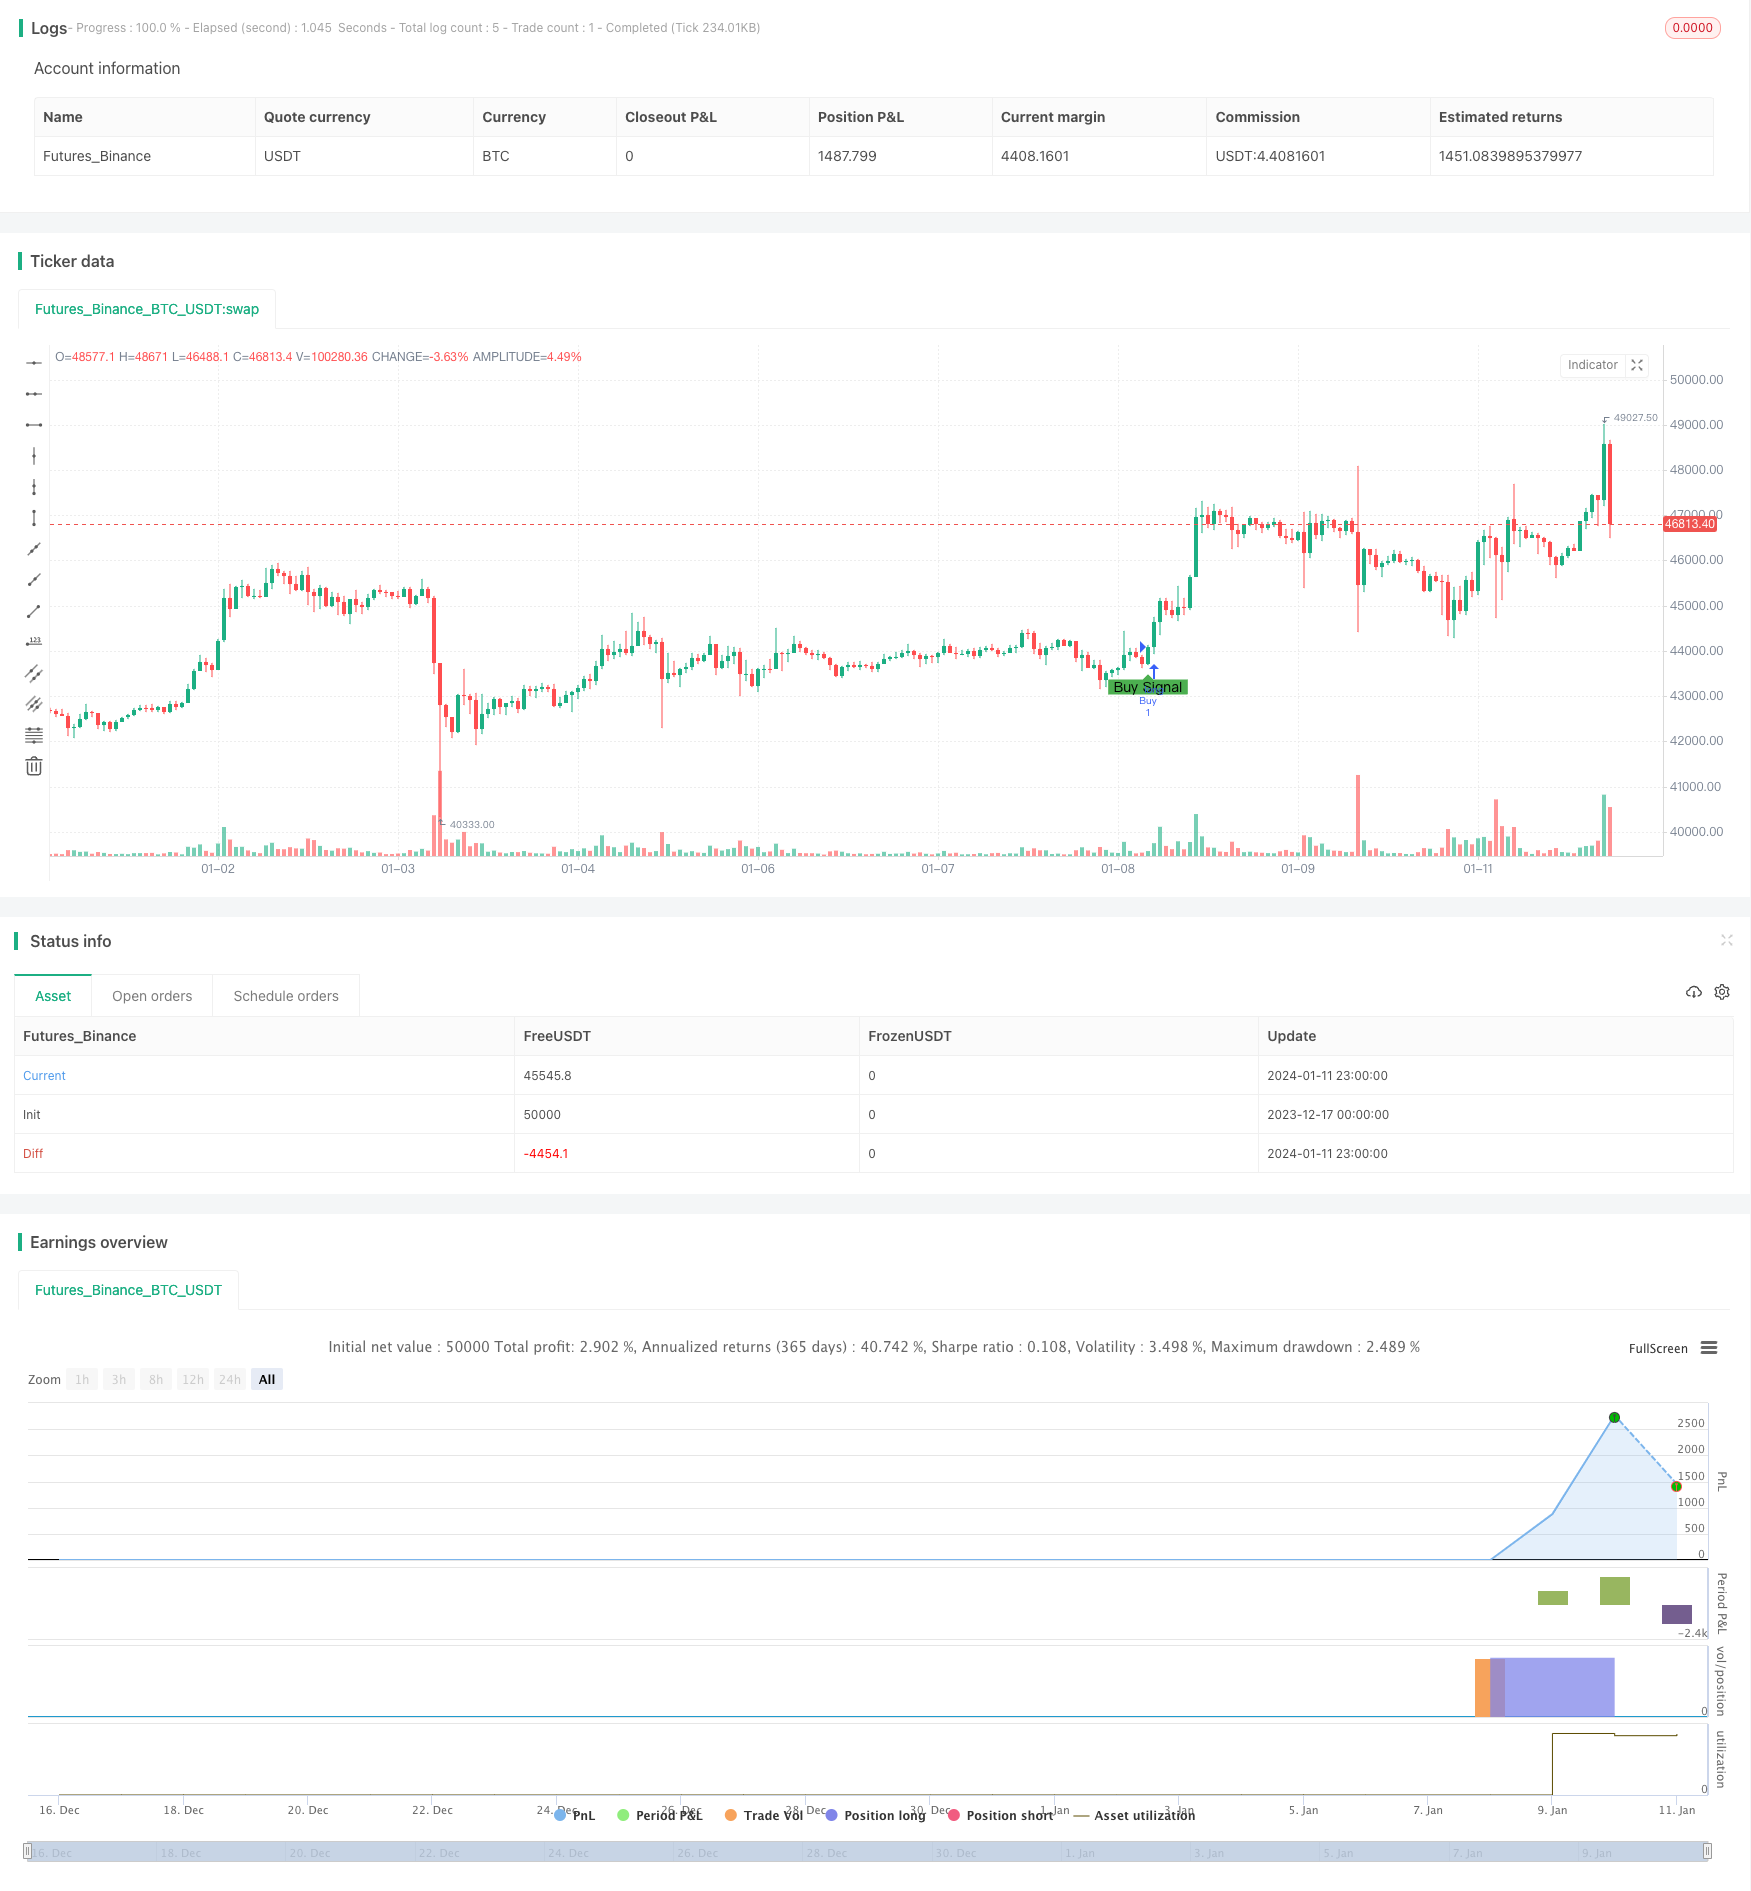
Overview
The "Trend Following Strategy Based on EMA and SMA Crossover" is a trend-following trading strategy based on the crossover of Exponential Moving Averages (EMAs) and Simple Moving Averages (SMAs). This strategy aims to identify potential buy and sell signals by capturing moments when the short-term EMA crosses above the long-term SMA.
Strategy Logic
This strategy generates trading signals based on two conditions:
- The latest 5-period EMA crossed above the latest 20-period SMA
- On the 4-hour timeframe, the latest 5-period EMA crossed above the latest 20-period SMA
When both conditions are true, a buy signal is generated. When both conditions are false, a sell signal is generated.
By comparing EMA and SMA crossovers across different timeframes, this strategy comprehensively judges the trend direction and generates trading signals. The short-term EMA reflects price changes more sensitively while the long-term SMA has better trend filtering capability. When the short-term EMA crosses above the long-term SMA, it indicates a slight trend reversal and generates a buy signal. Conversely, when the short-term EMA crosses below the long-term SMA, it indicates a trend reversal and generates a sell signal.
Adding the 4-hour EMA and SMA crossover filters out short-term noise and makes trading signals more reliable.
Advantages of the Strategy
This strategy has the following advantages:
- Simple and easy to understand
- Quick response, timely captures trend reversal
- Noise filtering by incorporating multiple timeframes
Risks of the Strategy
There are also some risks with this strategy:
- Prone to false signals, signals should be carefully validated
- Does not cope well with trendless markets
- EMA and SMA parameters need to be chosen carefully
Risks can be managed through incorporating stop loss/take profit, parameter optimization etc.
Enhancement Areas
Some ways to enhance this strategy:
- Test more EMA and SMA parameter combinations
- Add other indicators for signal validation e.g. MACD, Bollinger Bands
- Build a dynamic stop loss mechanism
- Filter by trading volume
Conclusion
In summary, this is a basic trend following strategy using simple EMA and SMA crossover rules. It can be improved via parameter optimization, signal filtering etc. to adapt better and improve strategy performance.
Source Pine Script
/*backtest
start: 2023-12-17 00:00:00
end: 2024-01-12 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA and SMA Crossover Strategy", shorttitle="Shashank Cross", overlay=true)

// Condition 1: Latest EMA (Close, 5) crossed above Latest SMA (Close, 20)
ema5 = ta.ema(close, 5)
sma20 = ta.sma(close, 20)

condition1 = ta.crossover(ema5, sma20)

// Condition 2: [0] 4-hour EMA ([0] 4-hour Close, 5) crossed above [0] 4-hour SMA ([0] 4-hour Close, 20)
ema5_4h = request.security(syminfo.tickerid, "240", ta.ema(close, 5))
sma20_4h = request.security(syminfo.tickerid, "240", ta.sma(close, 20))

condition2 = ta.crossover(ema5_4h, sma20_4h)

// Combine both conditions for a buy signal
buy_signal = condition1 and condition2

// Plotting signals on the chart
plotshape(buy_signal, color=color.green, style=shape.labelup, location=location.belowbar, size=size.small, text="Buy Signal")

// Strategy logic
if (buy_signal)
    strategy.entry("Buy", strategy.long)

// Exit long position on the next bar at market price
if (ta.barssince(buy_signal) == 1)
    strategy.close("Exit")

// You can add more code for stop-loss, take-profit, etc., as per your strategy.
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-EMA-and-SMA-Crossover.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Multi Indicator Trend Following Strategy with Dynamic Risk ManagementPine Script · Trend following · 2h
- Dynamic Moving Average Crossover Combo StrategyPine Script · Trend following · 10m
- Dynamic Moving Average Trend Crossover StrategyPine Script · Trend following · 1d
- Multi Technical Indicator Moving Average Crossover Trend Following Quantitative Trading StrategyPine Script · Trend following · 1h