Strategy vault / Trend following
Trend Following Strategy Based on Moving Average Crossover 442624
This strategy determines the price trend direction by calculating two moving averages with different parameter settings and comparing their crossover situations, so as to implement trend following trading. When the…
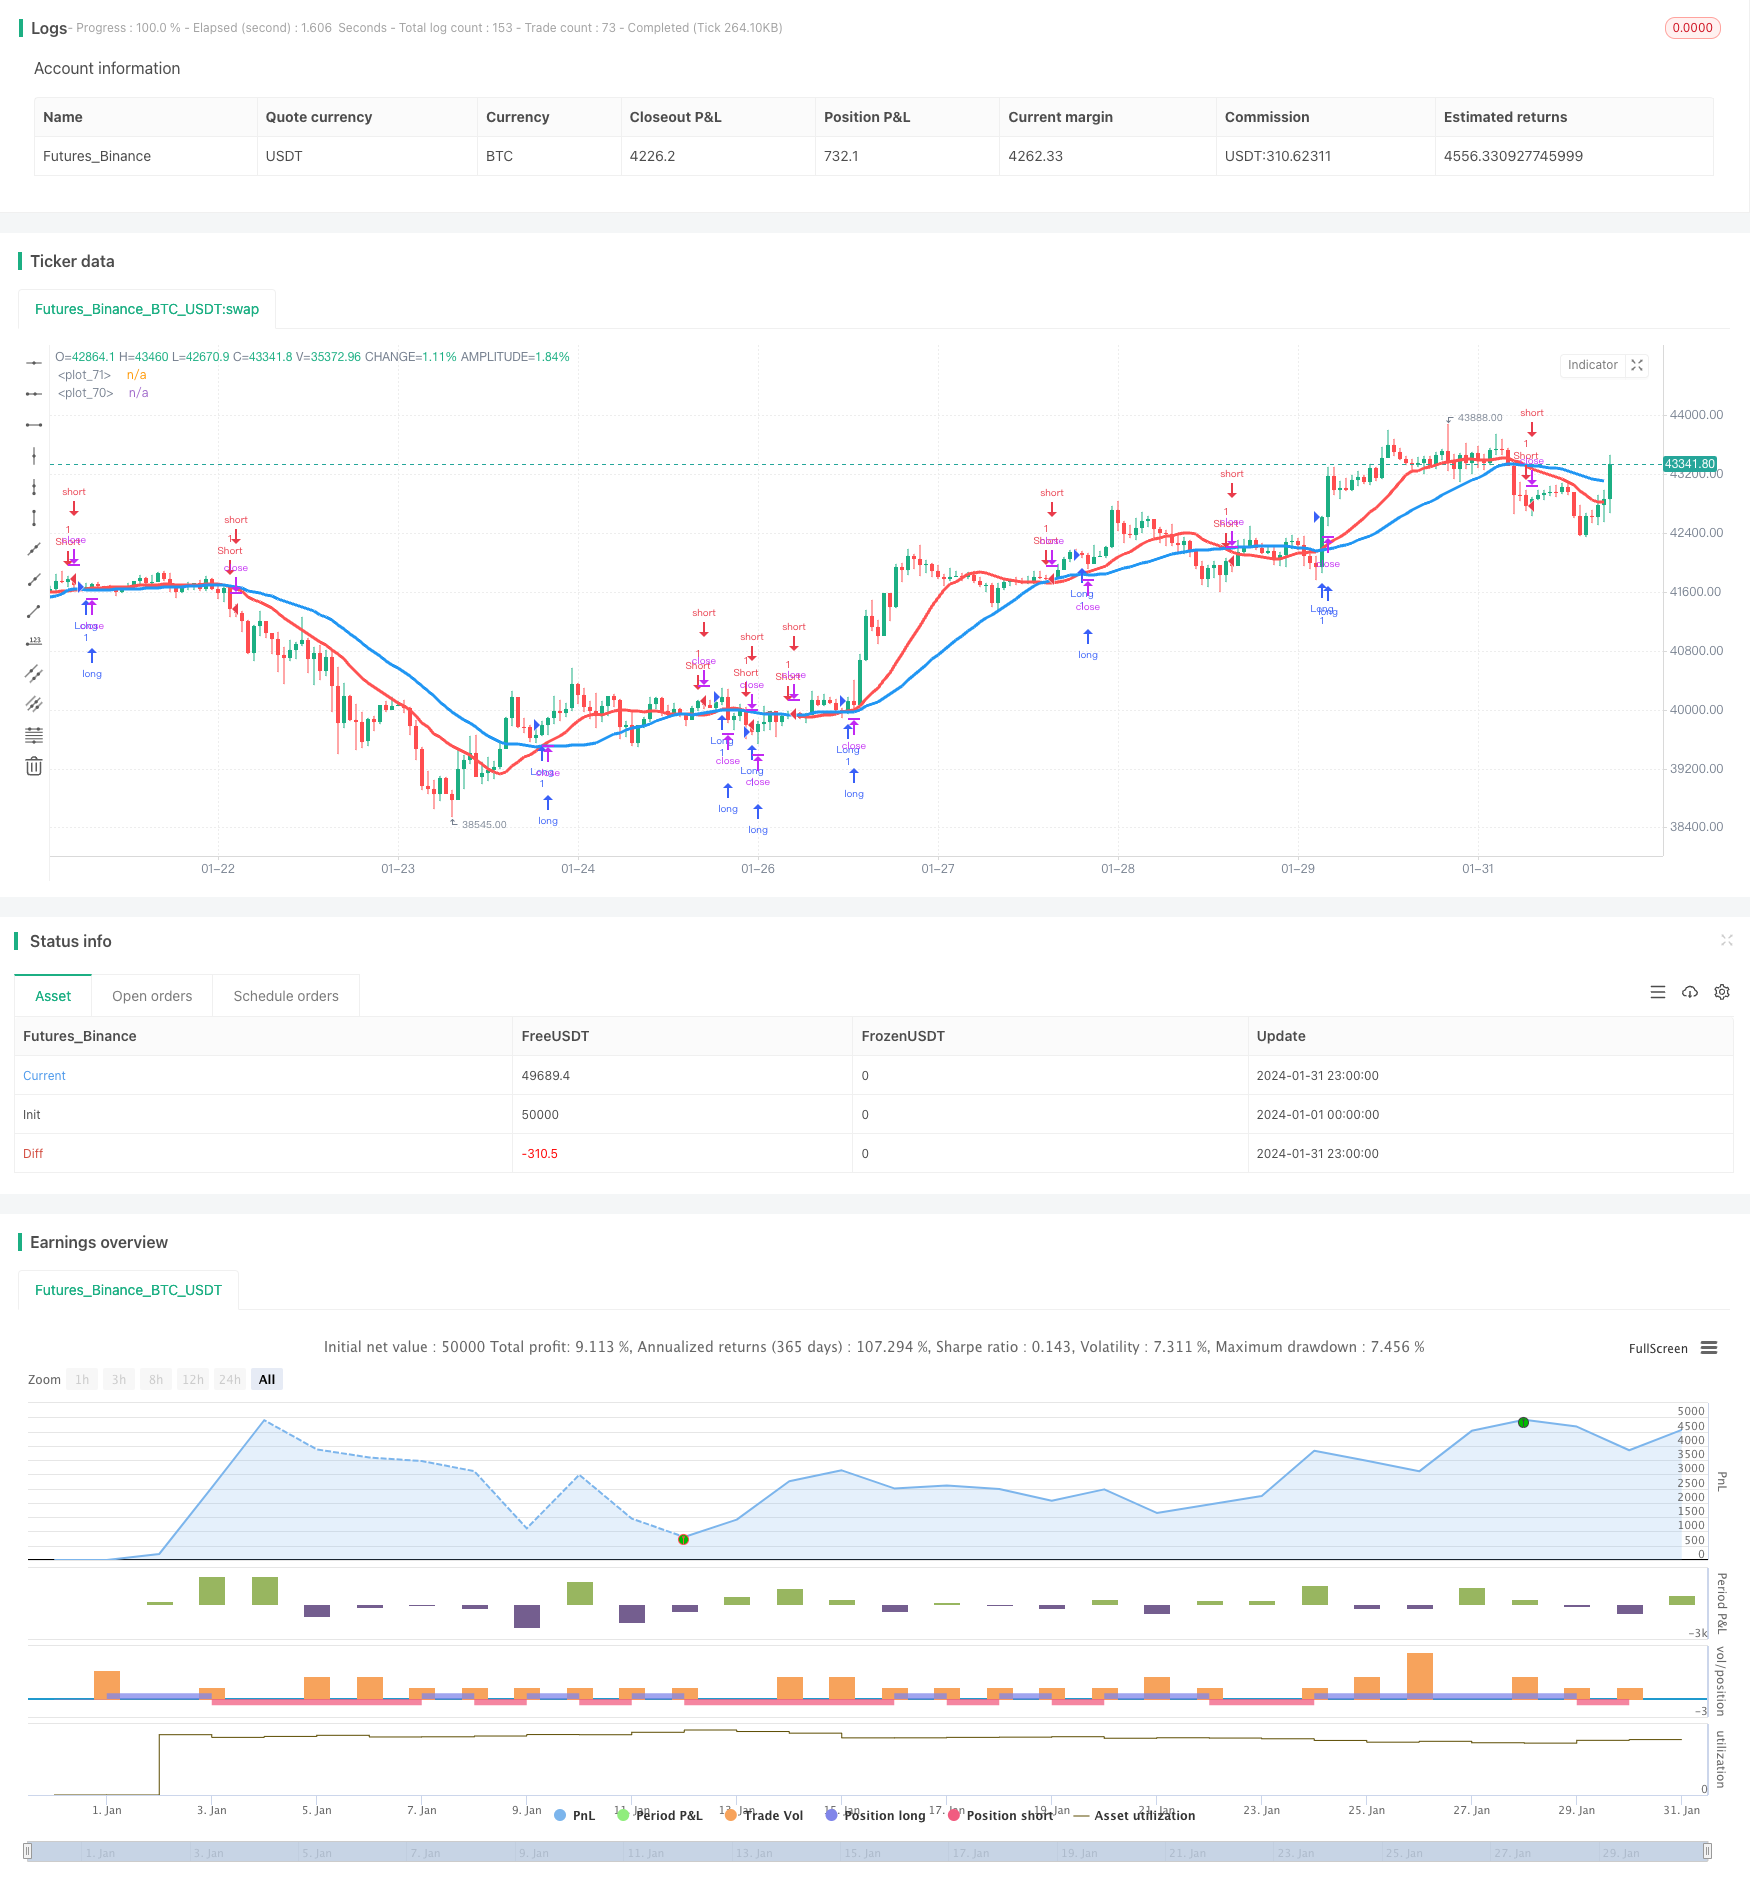
Overview
This strategy determines the price trend direction by calculating two moving averages with different parameter settings and comparing their crossover situations, so as to implement trend following trading. When the fast moving average breaks through the slow moving average from below, it is judged as a bullish signal. When the fast moving average breaks through the slow moving average from above, it is judged as a bearish signal. This strategy can achieve judgment of trends of different cycles by adjusting parameters.
Strategy Principle
This strategy uses two sets of moving averages with different parameter settings for comparison. The first moving average parameter is set by len1 and type1, and the second moving average parameter is set by len2 and type2. Where len1 and len2 represent the cycle length of the two moving averages respectively, and type1 and type2 represent the algorithm type of the moving average.
When the fast moving average crosses above the slow moving average to form a golden cross, it is judged as a bullish signal. When the fast moving average crosses below the slow moving average to form a dead cross, it is judged as a bearish signal.
According to the direction of the crossover signal, long or short positions will be executed. When a bullish signal is triggered, if the needlong parameter is true, a long position will be opened with the quantity default_qty_value or percentage_of_equity. When a bearish signal is triggered, if the needshort parameter is true, a short position will be opened with the quantity default_qty_value or percentage_of_equity.
Advantages
- Support the combination of 7 different types of moving averages to flexibly adapt to market conditions
- Customize parameters of two moving averages to judge long-term and medium-short term trends
- Simple and clear signal judgment rules, easy to understand and implement
- Support long and short positions, can carry out trend tracking transactions
Risks and Solutions
Moving averages have lagging properties and may miss price reversal points
Solution: Appropriately shorten moving average cycles, or use in combination with other indicatorsNot suitable for markets with high volatility and frequent reversals
Solution: Add filtering conditions to avoid trading in oscillating marketsThere are certain risks of false signals
Solution: Add other filtering indicators for combination to improve signal reliability
Optimization Directions
- Optimize the cycle combination of moving averages, and test the impact of long and short cycle parameters on strategy return
- Test the performance of different types of moving averages to find the optimal moving average algorithm
- Add trading volume variable or Bollinger Bands for combination to improve signal quality
- Optimize position management strategy to improve fixed position percentage_of_equity approach
Summary
This strategy judges the price trend by comparing the crossovers of two moving averages, and makes corresponding long and short operations to capture and profit from trends. The advantage is that the signal rules are simple and clear, the parameters are adjustable, the applicability is strong, and it can be optimized and adjusted for various market environments. Pay attention to prevent the lagging risks of moving averages and choppy markets, which can be reduced by adding other indicators for filtering to improve signal quality.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | long |
| v_input_2 | true | short |
| v_input_3 | 15 | Fast MA length |
| v_input_4 | true | Fast MA Type |
| v_input_5_close | 0 | Fast MA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | 30 | Slow MA length |
| v_input_7 | true | Slow MA Type |
| v_input_8_close | 0 | Slow MA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_9 | false | Color of bar |
| v_input_10 | false | 1 SMA, 2 EMA, 3 VWMA, 4 DEMA, 5 TEMA, 6 KAMA, 7 Price Channel |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy(title = "Noro's MAs Cross Tests v1.0", shorttitle = "MAs Cross tests 1.0", overlay=true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100.0, pyramiding = 0)

needlong = input(true, "long")
needshort = input(true, "short")

len2 = input(15, defval = 15, minval = 2, maxval = 1000, title = "Fast MA length")
type2 = input(1, defval = 1, minval = 1, maxval = 7, title = "Fast MA Type")
src2 = input(close, defval = close, title = "Fast MA Source")

len1 = input(30, defval = 30, minval = 2, maxval = 1000, title = "Slow MA length")
type1 = input(1, defval = 1, minval = 1, maxval = 7, title = "Slow MA Type")
src1 = input(close, defval = close, title = "Slow MA Source")

col = input(false, defval = false, title = "Color of bar")

o = input(false, title = "1 SMA, 2 EMA, 3 VWMA, 4 DEMA, 5 TEMA, 6 KAMA, 7 Price Channel")

//DEMA 1
dema1 = 2 * ema(src1, len1) - ema(ema(close, len1), len1)

//TEMA 1
xEMA1 = ema(src1, len1)
xEMA2 = ema(xEMA1, len1)
xEMA3 = ema(xEMA2, len1)
tema1 = 3 * xEMA1 - 3 * xEMA2 + xEMA3

//KAMA 1
xvnoise = abs(src1 - src1[1])
nfastend = 0.20
nslowend = 0.05
nsignal = abs(src1 - src1[len1])
nnoise = sum(xvnoise, len1)
nefratio = iff(nnoise != 0, nsignal / nnoise, 0)
nsmooth = pow(nefratio * (nfastend - nslowend) + nslowend, 2)
kama1 = nz(kama1[1]) + nsmooth * (src1 - nz(kama1[1]))

//PriceChannel 1
lasthigh1 = highest(src1, len1)
lastlow1 = lowest(src1, len1)
center1 = (lasthigh1 + lastlow1) / 2

//DEMA 2
dema2 = 2 * ema(src2, len2) - ema(ema(close, len2), len2)

//TEMA 2
xEMA12 = ema(src2, len2)
xEMA22 = ema(xEMA12, len2)
xEMA32 = ema(xEMA22, len2)
tema2 = 3 * xEMA12 - 3 * xEMA22 + xEMA32

//KAMA 2
xvnoise2 = abs(src2 - src2[1])
nfastend2 = 0.20
nslowend2 = 0.05
nsignal2 = abs(src2 - src2[len2])
nnoise2 = sum(xvnoise2, len2)
nefratio2 = iff(nnoise2 != 0, nsignal2 / nnoise2, 0)
nsmooth2 = pow(nefratio2 * (nfastend2 - nslowend2) + nslowend2, 2)
kama2 = nz(kama2[1]) + nsmooth2 * (src2 - nz(kama2[1]))

//PriceChannel 2
lasthigh2 = highest(src2, len2)
lastlow2 = lowest(src2, len2)
center2 = (lasthigh2 + lastlow2) / 2

//MAs
ma1 = type1 == 1 ? sma(src1, len1) : type1 == 2 ? ema(src1, len1) : type1 == 3 ? vwma(src1, len1) : type1 == 4 ? dema1 : type1 == 5 ? tema1 : type1 == 6 ? kama1 : type1 == 7 ? center1 : 0
ma2 = type2 == 1 ? sma(src2, len2) : type2 == 2 ? ema(src2, len2) : type2 == 3 ? vwma(src2, len2) : type2 == 4 ? dema2 : type2 == 5 ? tema2 : type2 == 6 ? kama2 : type2 == 7 ? center2 : 0
plot(ma1, color = blue, linewidth = 3, transp = 0)
plot(ma2, color = red, linewidth = 3, transp = 0)

//Signals
trend = ma2 > ma1 ? 1 : ma2 < ma1 ? -1 : trend[1]
up = trend == 1 and ((close < open and close[1] < open[1]) or col == false)
dn = trend == -1 and ((close > open and close[1] > open[1]) or col == false)

if up
    strategy.entry("Long", strategy.long, needlong == false ? 0 : na)

if dn
strategy.entry("Short", strategy.short, needshort == false ? 0 : na)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-Moving-Average-Crossover-442624.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d