Strategy vault / Trend following
Trend Following Strategy Based on Moving Averages 439203
This strategy is a trend following strategy based on moving averages. It utilizes EMA lines of different periods to construct multiple sets of trading signals for trend tracking. When the price breaks below longer…
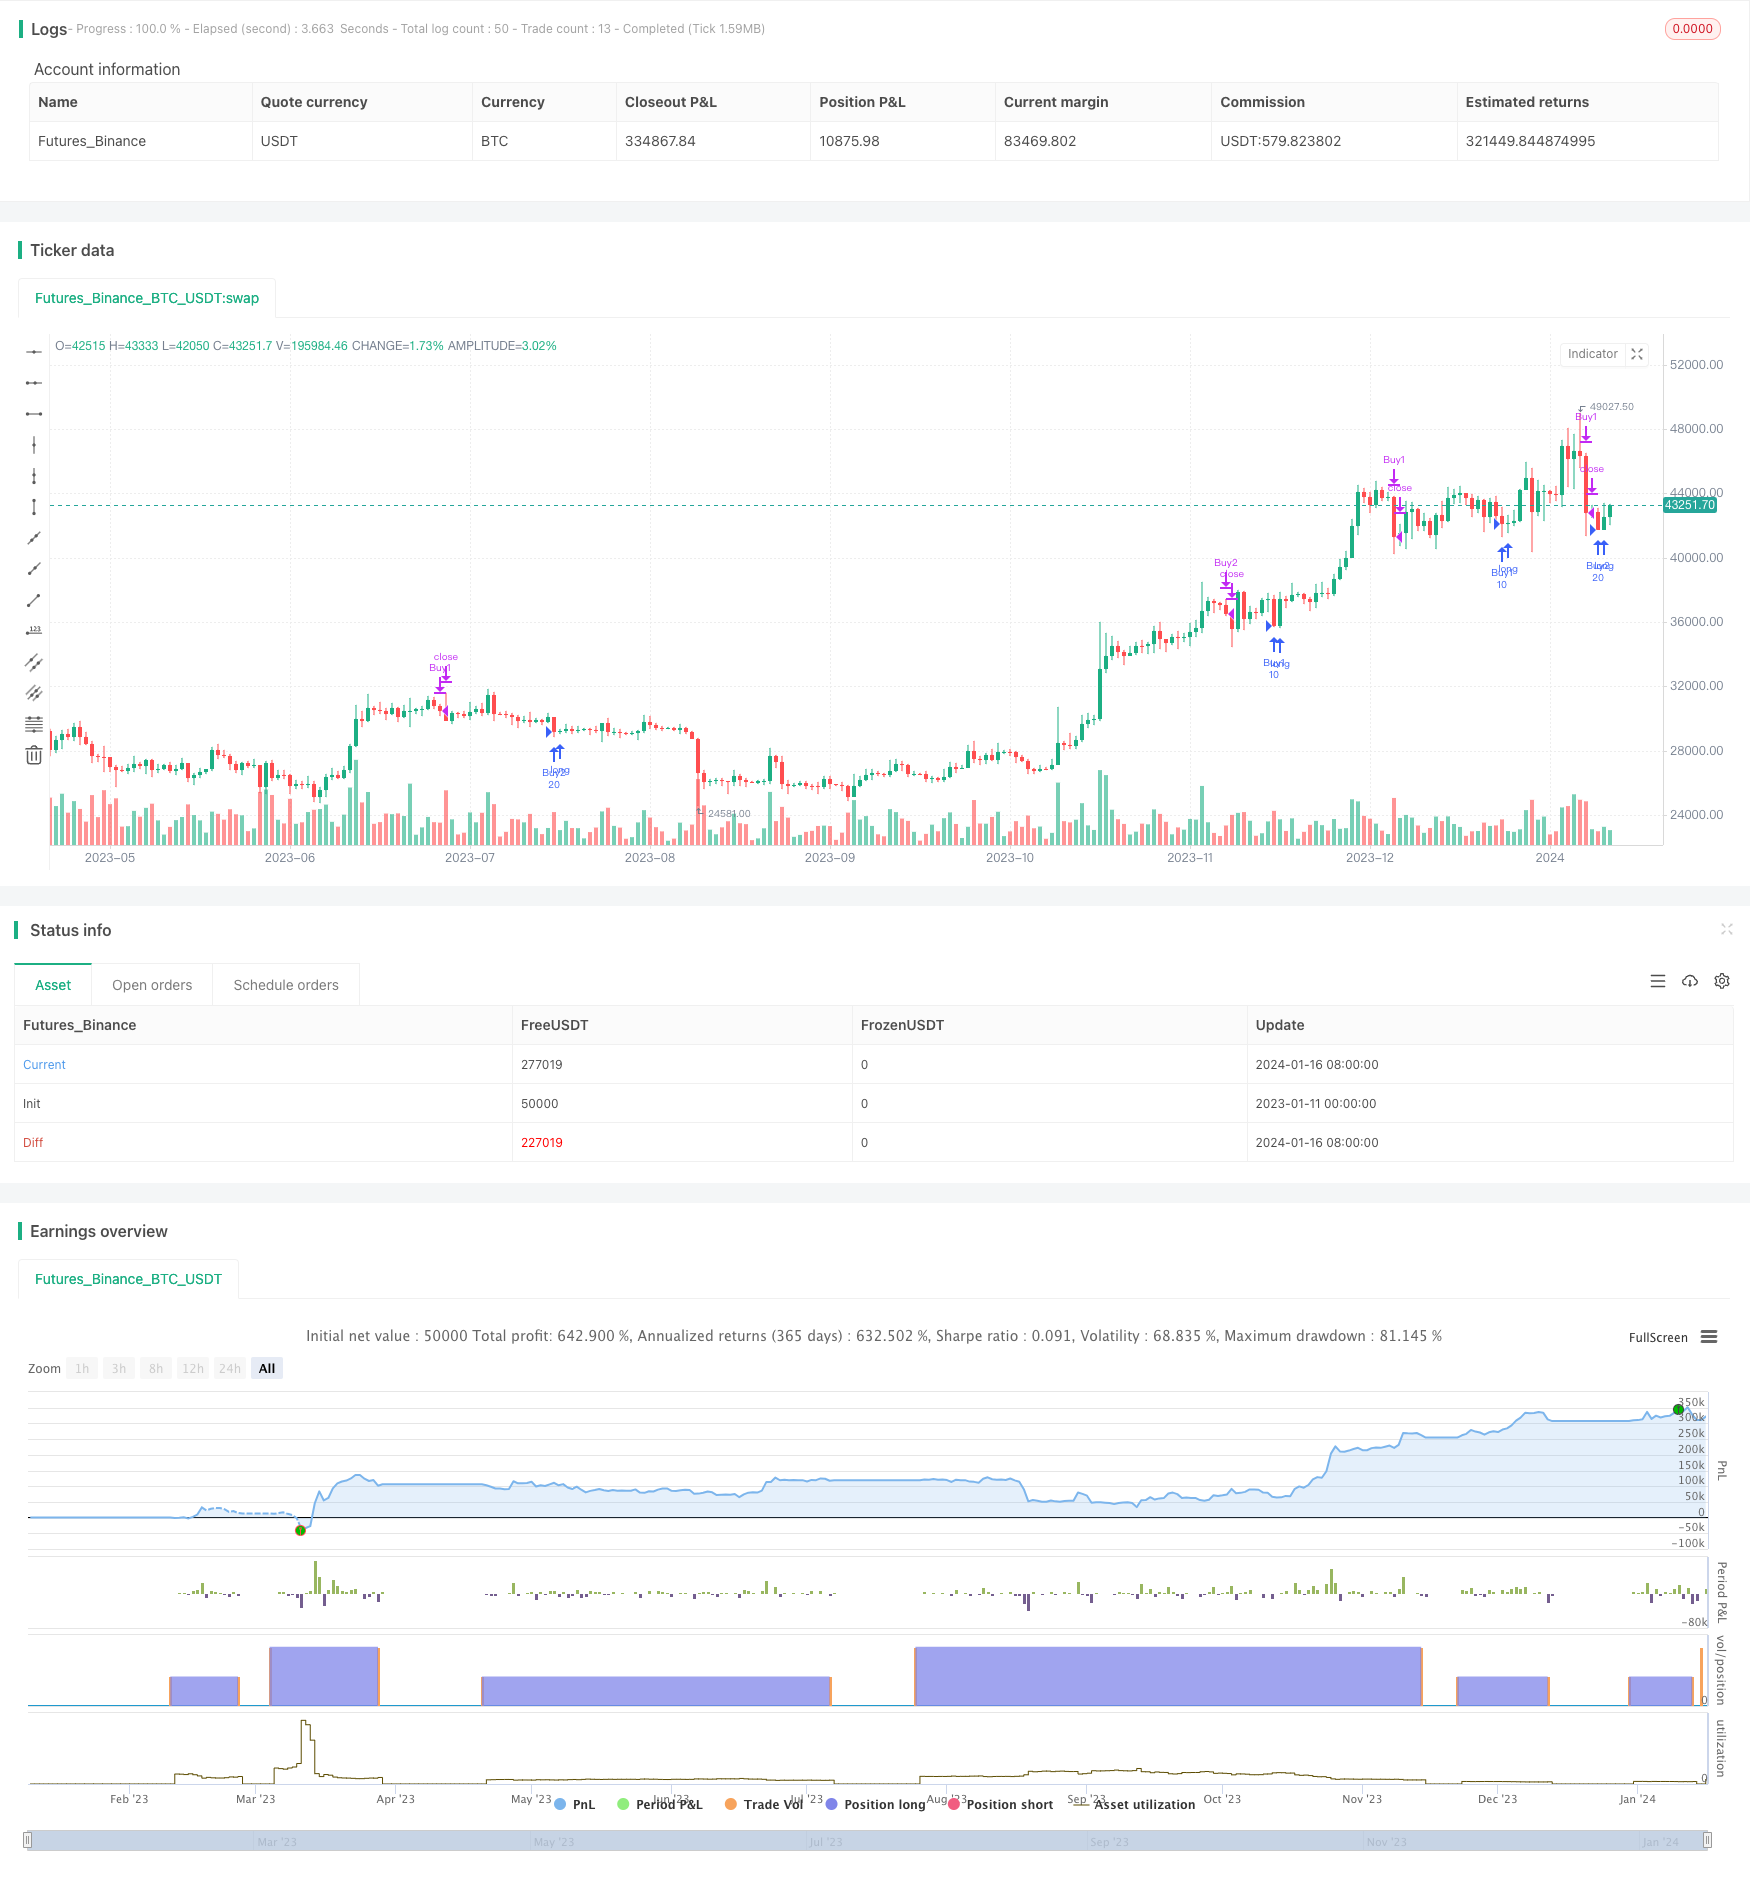
Overview
This strategy is a trend following strategy based on moving averages. It utilizes EMA lines of different periods to construct multiple sets of trading signals for trend tracking. When the price breaks below longer period moving averages, the strategy will progressively build long positions to lower the average cost. The strategy also sets stop loss conditions based on short period moving average turns to secure profits.
Strategy Logic
The strategy employs 5 EMA lines of different periods for constructing trading signals, which are 10-day, 20-day, 50-day, 100-day and 200-day EMA. The strategy defines 4 buying conditions based on the price relationship with these EMA lines to implement pyramid trading.
When the price is below 20-day EMA while above 50-day EMA, the first buy signal is triggered. When below 50-day EMA while above 100-day EMA, the second buy signal is triggered. The third and fourth buy signals are triggered when the price drops below 100-day EMA and 200-day EMA respectively. The position size also expands progressively from qt1 to qt4.
On the sell side, there are two groups of stop loss conditions. The first is to stop loss when price surpasses 10-day EMA while 10-day EMA is above other EMA lines. The second is similar but it exits when price drops below previous close of 10-day EMA. These two conditions are to secure short-term profits during trends.
Advantage Analysis
The biggest advantage of this strategy is the ability to automatically track market trends for long-term holds. By utilizing multiple entry conditions and progressive position building, it constantly reduces cost basis to yield excess returns. It also diversifies away the pricing risk associated with a single entry price level.
On the stop loss side, the strategy tracks short period moving average turning points to quickly take profit and avoid further losses. This minimizes the downside risk.
Risk Analysis
The biggest risk this strategy faces is being stuck in long lasting consolidations or downtrends. When the overall market enters a ranging or downward channel, moving average signals become less reliable. This could lead to sustained losses from continued long builds.
Another risk point is that moving averages do not always pinpoint turns accurately. Price gaps or explosive moves could result in faulty signals. This calls for additional technical indicators for verification and optimization.
Optimization Directions
Other technical indicators like volume or Bollinger Bands could be incorporated into the buying conditions to further improve entry accuracy.
The second layers of stop loss based on Bollinger Upper Band or key support areas could also be added. This helps avoid unnecessary small stops. Implementing adaptive stop loss to trail prices is another enhancement area to better protect profits.
Conclusion
This strategy implements trend following trading via a moving average system. Through pyramid position building, it aims to maximize returns from sustained trends while securing capital preservation with dual stop loss mechanisms. This is a strategy worthy of further tracking and live testing. Parameters and models can be incrementally optimized based on practical performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 5 | Quantity 1 |
| v_input_int_2 | 10 | Quantity 2 |
| v_input_int_3 | 15 | Quantity 3 |
| v_input_int_4 | 20 | Quantity 4 |
| v_input_1 | true | Profit Percentage |
| v_input_int_5 | 2 | Pyramiding |
Source Pine Script
/*backtest
start: 2023-01-11 00:00:00
end: 2024-01-17 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA_zorba1", shorttitle="zorba_ema", overlay=true)

// Input parameters
qt1 = input.int(5, title="Quantity 1", minval=1)
qt2 = input.int(10, title="Quantity 2", minval=1)
qt3 = input.int(15, title="Quantity 3", minval=1)
qt4 = input.int(20, title="Quantity 4", minval=1)
ema10 = ta.ema(close, 10)
ema20 = ta.ema(close, 20)
ema50 = ta.ema(close, 50)
ema100 = ta.ema(close, 100)
ema200 = ta.ema(close, 200)

// Date range filter
start_date = timestamp(year=2021, month=1, day=1)
end_date = timestamp(year=2024, month=10, day=27)
in_date_range = true

// Profit condition
profit_percentage = input(1, title="Profit Percentage")  // Adjust this value as needed

// Pyramiding setting
pyramiding = input.int(2, title="Pyramiding", minval=1, maxval=10)

// Buy conditions
buy_condition_1 = in_date_range and close < ema20 and close > ema50 and close < open and close < low[1]
buy_condition_2 = in_date_range and close < ema50 and close > ema100 and close < open and close < low[1]
buy_condition_3 = in_date_range and close < ema100 and close > ema200 and close < open and close < low[1]
buy_condition_4 = in_date_range and close < ema200 and close < open and close < low[1]

// Exit conditions
profit_condition = strategy.position_avg_price * (1 + profit_percentage / 100) <= close
exit_condition_1 = in_date_range and (close > ema10 and ema10 > ema20 and ema10 > ema50 and ema10 > ema100 and ema10 > ema200 and close < open) and profit_condition and close < low[1] and close < low[2]
exit_condition_2 = in_date_range and (close < ema10 and close[1] > ema10 and close < close[1] and ema10 > ema20 and ema10 > ema50 and ema10 > ema100 and ema10 > ema200 and close < open) and profit_condition and close < low[1] and close < low[2]

// Exit condition for when today's close is less than the previous day's low
//exit_condition_3 = close < low[1]

// Strategy logic
strategy.entry("Buy1", strategy.long, qty=qt1 * pyramiding, when=buy_condition_1)
strategy.entry("Buy2", strategy.long, qty=qt2 * pyramiding, when=buy_condition_2)
strategy.entry("Buy3", strategy.long, qty=qt3 * pyramiding, when=buy_condition_3)
strategy.entry("Buy4", strategy.long, qty=qt4 * pyramiding, when=buy_condition_4)

strategy.close("Buy1", when=exit_condition_1 or exit_condition_2)
strategy.close("Buy2", when=exit_condition_1 or exit_condition_2)
strategy.close("Buy3", when=exit_condition_1 or exit_condition_2)
strategy.close("Buy4", when=exit_condition_1 or exit_condition_2)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-Moving-Averages-439203.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h