Strategy vault / Trend following
Trend Following Strategy Based on Stochastic and CCI
This strategy combines Stochastic indicator and CCI indicator to identify trend direction, and uses Rate of Change indicator to filter out range-bound trends, in order to follow the trend. The strategy adopts…
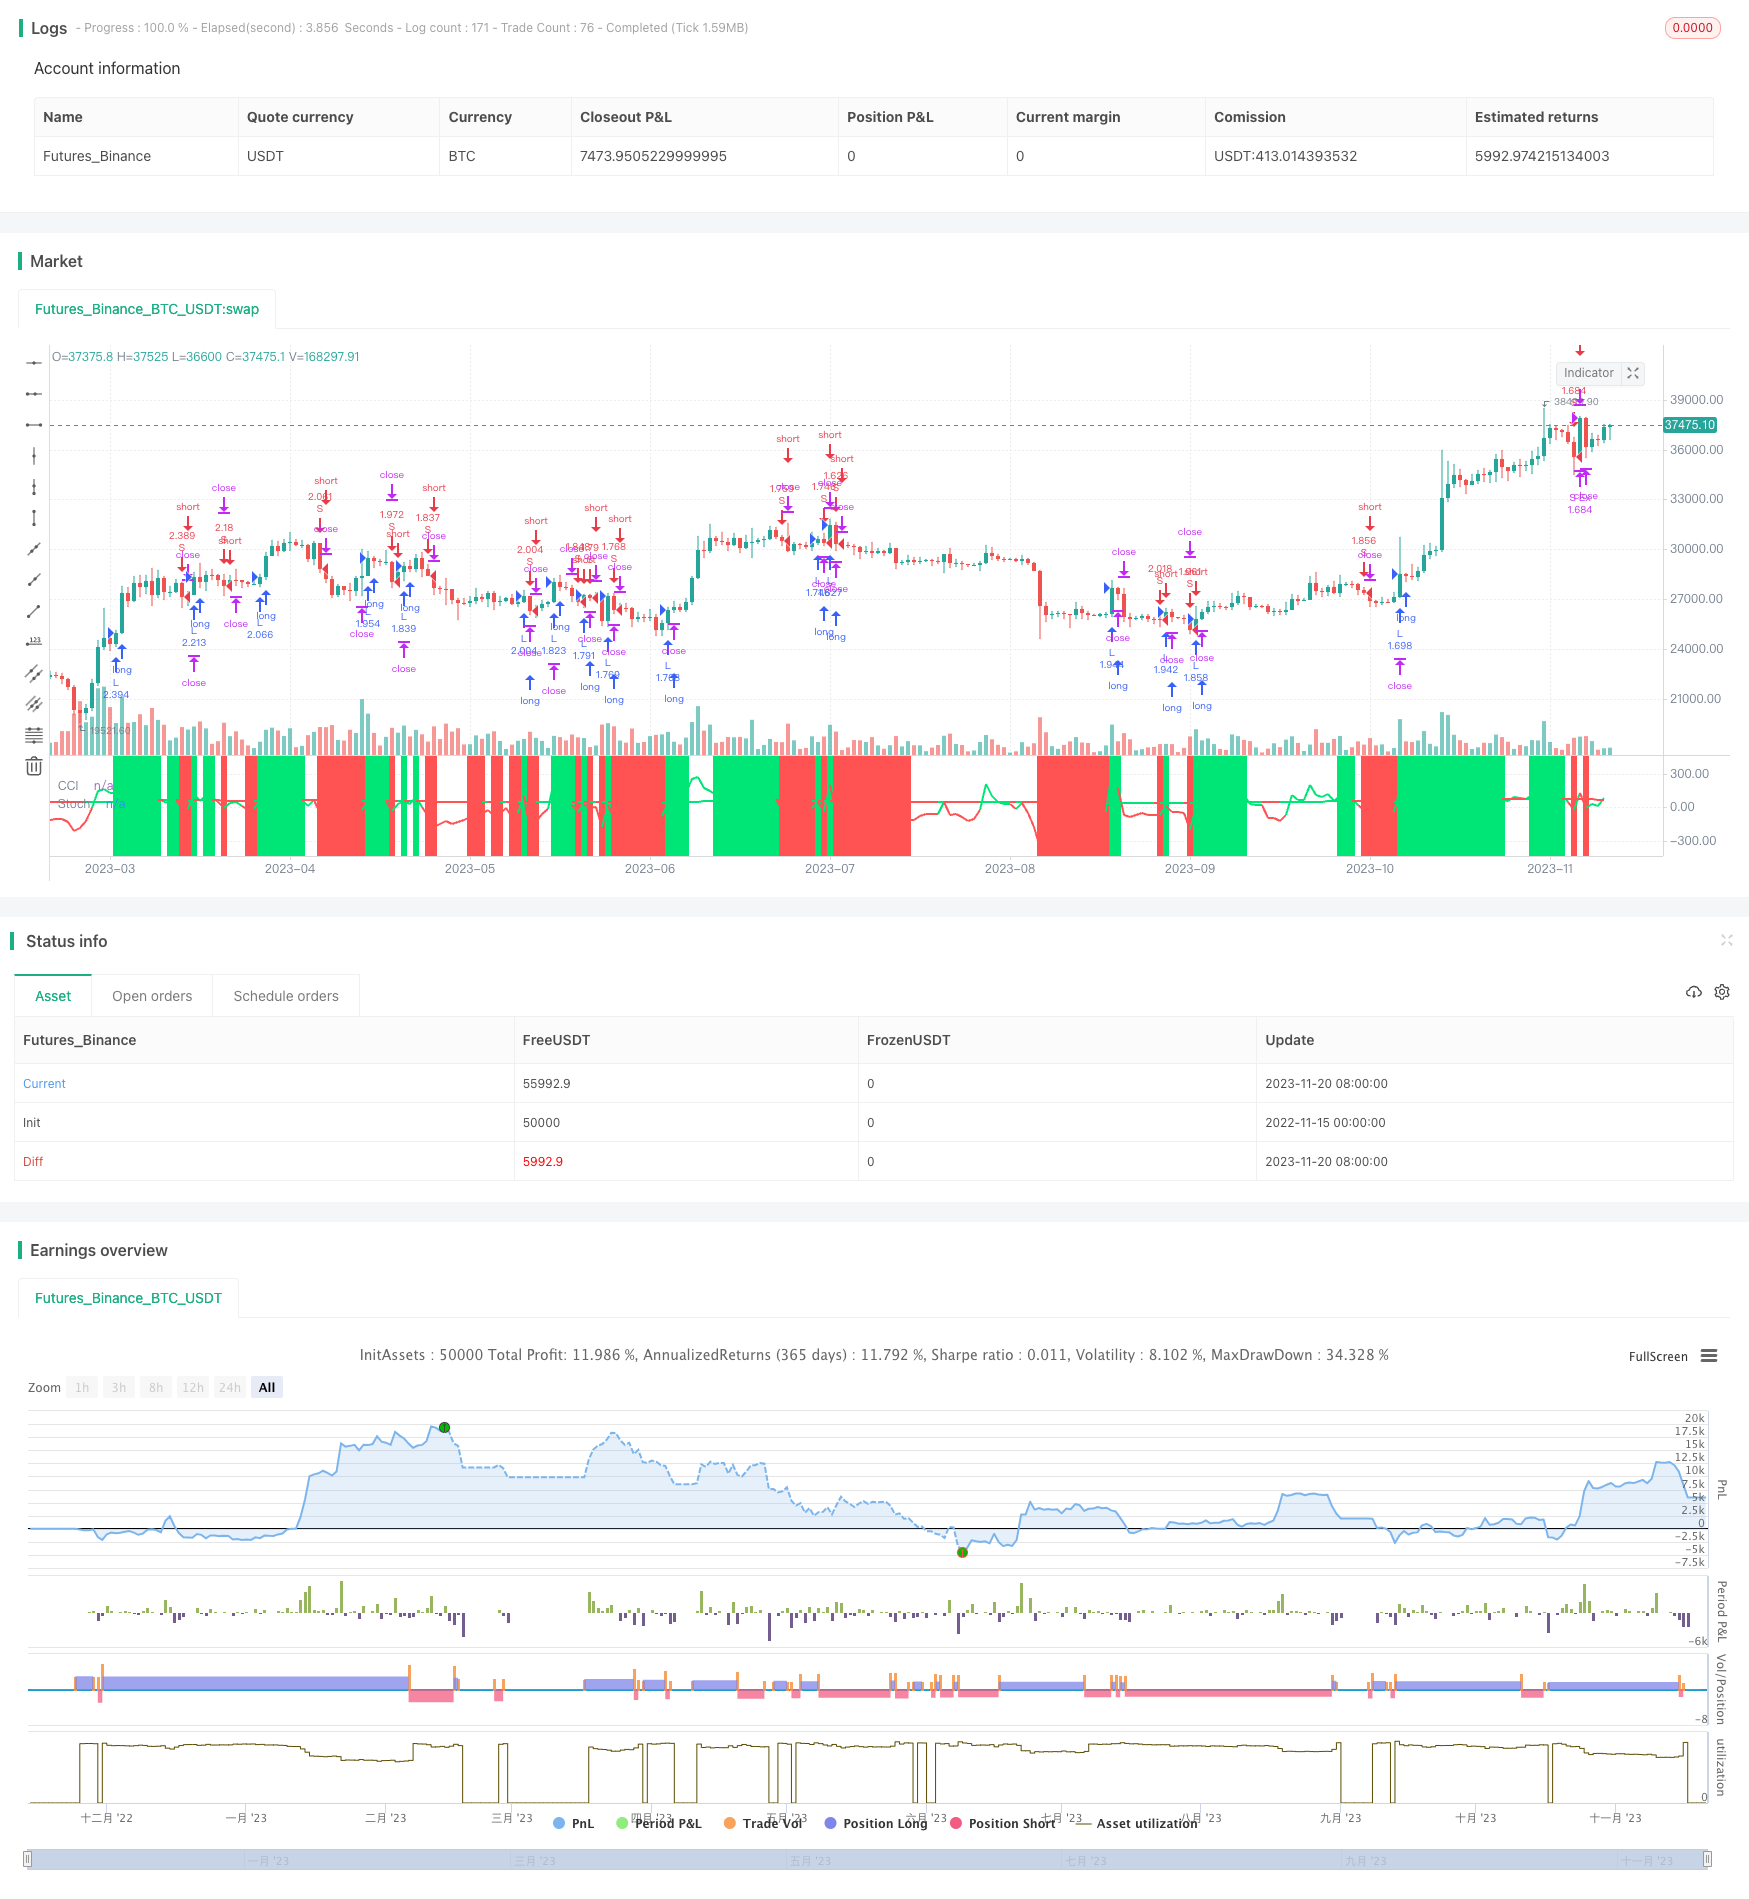
Overview
This strategy combines Stochastic indicator and CCI indicator to identify trend direction, and uses Rate of Change indicator to filter out range-bound trends, in order to follow the trend. The strategy adopts breakout entry and stop loss exit.
Strategy Logic
- Stochastic indicator judges bullish/bearish pattern
Golden cross of Stochastic is buy signal, while death cross is sell signal - CCI indicator determines trend direction CCI above 0 indicates bullish market, while below 0 bearish market
- Rate of Change indicator filters range-bound trend
Set parameters of Rate of Change to judge whether price is in an active trend - Entry and exit rules Long entry: Stochastic golden cross & CCI > 0 & active trend Short entry: Stochastic death cross & CCI < 0 & active trend Stop loss exit: 3% stop loss for both long and short side
Pros Analysis
- Combination of Stochastic and CCI improves accuracy of trend judgment
- Rate of Change filters out range-bound trends, avoiding invalid trades
- Both long and short trading, able to catch different trend types
- Breakout entry timely catches trend opportunity
- Strict stop loss prevents huge loss and controls risk
Risks Analysis
- Improper parameter setting may lead to over-conservative or aggressive strategy
- Limited effect of indicators, may fail in extreme market conditions
- Breakout entry misses early stage of trends, giving up part of profit
- Too tight or too wide stop loss fails in risk control
Optimization Directions
- Parameter optimization to find optimum combination
- Add more trend indicators to improve effectiveness
- Use trailing stop loss or time-based stop loss to reduce chance of stop loss breach
- Add risk metrics like max drawdown to fully control risk
Summary
This strategy judges trend direction by integrating Stochastic, CCI and Rate of Change indicators, and catches trend opportunity with breakout tracking. Its pros lie in accurate judgment empowered by indicator combination, filtering of range-bound market, and strict stop loss for risk control. The next step is to further improve the strategy via parameter optimization, multiple indicators, stop loss strategy to make it more robust and flexible.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2019 | Backtest Stop Year |
| v_input_5 | 12 | Backtest Stop Month |
| v_input_6 | 31 | Backtest Stop Day |
| v_input_7 | 13 | CCI Length |
| v_input_8 | 19 | RSI Length |
| v_input_9 | 12 | RSI-EMA Length |
| v_input_10 | 30 | roclength |
| v_input_11 | 7 | pcntChange |
| v_input_12 | 3 | Stop Loss % |
Source Pine Script
/*backtest
start: 2022-11-15 00:00:00
end: 2023-11-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Stochastic CCI BF ?", overlay=false, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.075)

/////////////// Time Frame ///////////////
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay, 0, 0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(31, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay, 0, 0)

testPeriod() => true

///////////// CCI /////////////
src = close
ccilength = input(13, minval=1, title="CCI Length")
c=cci(src, ccilength)

///////////// Stochastic /////////////
len = input(19, minval=1, title="RSI Length")
lenema = input(12, minval=1, title="RSI-EMA Length")
up = rma(max(change(src), 0), len)
down = rma(-min(change(src), 0), len)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
out = ema(rsi, lenema)

///////////// Rate Of Change /////////////
source = close
roclength = input(30, minval=1)
pcntChange = input(7.0, minval=1)
roc = 100 * (source - source[roclength]) / source[roclength]
emaroc = ema(roc, roclength / 2)
isMoving() => emaroc > (pcntChange / 2) or emaroc < (0 - (pcntChange / 2))

/////////////// Strategy ///////////////
long = out > out[1] and isMoving() and c > 0
short = out < out[1] and isMoving() and c < 0

last_long = 0.0
last_short = 0.0
last_long := long ? time : nz(last_long[1])
last_short := short ? time : nz(last_short[1])

long_signal = crossover(last_long, last_short)
short_signal = crossover(last_short, last_long)

last_open_long_signal = 0.0
last_open_short_signal = 0.0
last_open_long_signal := long_signal ? open : nz(last_open_long_signal[1])
last_open_short_signal := short_signal ? open : nz(last_open_short_signal[1])

last_long_signal = 0.0
last_short_signal = 0.0
last_long_signal := long_signal ? time : nz(last_long_signal[1])
last_short_signal := short_signal ? time : nz(last_short_signal[1])

in_long_signal = last_long_signal > last_short_signal
in_short_signal = last_short_signal > last_long_signal

last_high = 0.0
last_low = 0.0
last_high := not in_long_signal ? na : in_long_signal and (na(last_high[1]) or high > nz(last_high[1])) ? high : nz(last_high[1])
last_low := not in_short_signal ? na : in_short_signal and (na(last_low[1]) or low < nz(last_low[1])) ? low : nz(last_low[1])

sl_inp = input(3.0, title='Stop Loss %') / 100

since_longEntry = barssince(last_open_long_signal != last_open_long_signal[1])
since_shortEntry = barssince(last_open_short_signal != last_open_short_signal[1])

slLong = in_long_signal ? strategy.position_avg_price * (1 - sl_inp) : na
slShort = strategy.position_avg_price * (1 + sl_inp)
long_sl = in_long_signal ? slLong : na
short_sl = in_short_signal ? slShort : na

/////////////// Execution ///////////////
if testPeriod()
    strategy.entry("L",  strategy.long, when=long_signal)
    strategy.entry("S", strategy.short, when=short_signal)
    strategy.exit("L Ex", "L", stop=long_sl, when=since_longEntry > 0)
    strategy.exit("S Ex", "S", stop=short_sl, when=since_shortEntry > 0)

/////////////// Plotting ///////////////
bgcolor(long_signal ? color.lime : short_signal ? color.red : na, transp=30)
bgcolor(not isMoving() ? color.white : long ? color.lime : short ? color.red : na, transp=80)
plot(out, color = out > out[1] ? color.lime:color.red, linewidth = 2, title="Stoch")
plot(c, color = c > 0 ? color.lime:color.red, linewidth = 2, title="CCI")Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Following-Strategy-Based-on-Stochastic-and-CCI.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Trend Tracking Strategy Based on Multi factor Model with Adaptive Trailing StoplossPine Script · Trend following · 1d
- Price Divergence Based Trend Trading StrategyPine Script · Trend following · 2h
- Trend Following Strategy Based on Moving Average Crossover 430022Pine Script · Trend following · 1d
- Price Divergence Strategy v10Pine Script · Trend following · 1h
- SuperTrend Trading Strategy with Multiple FiltersPine Script · Trend following · 1h