Strategy vault / Trend following
Trend Prediction Dual Moving Average Strategy
The Trend Prediction Dual Moving Average Strategy is a strategy that tries to predict trend changes before the actual break from one trend to another. It extends LazyBear's WaveTrend indicator. The strategy can…
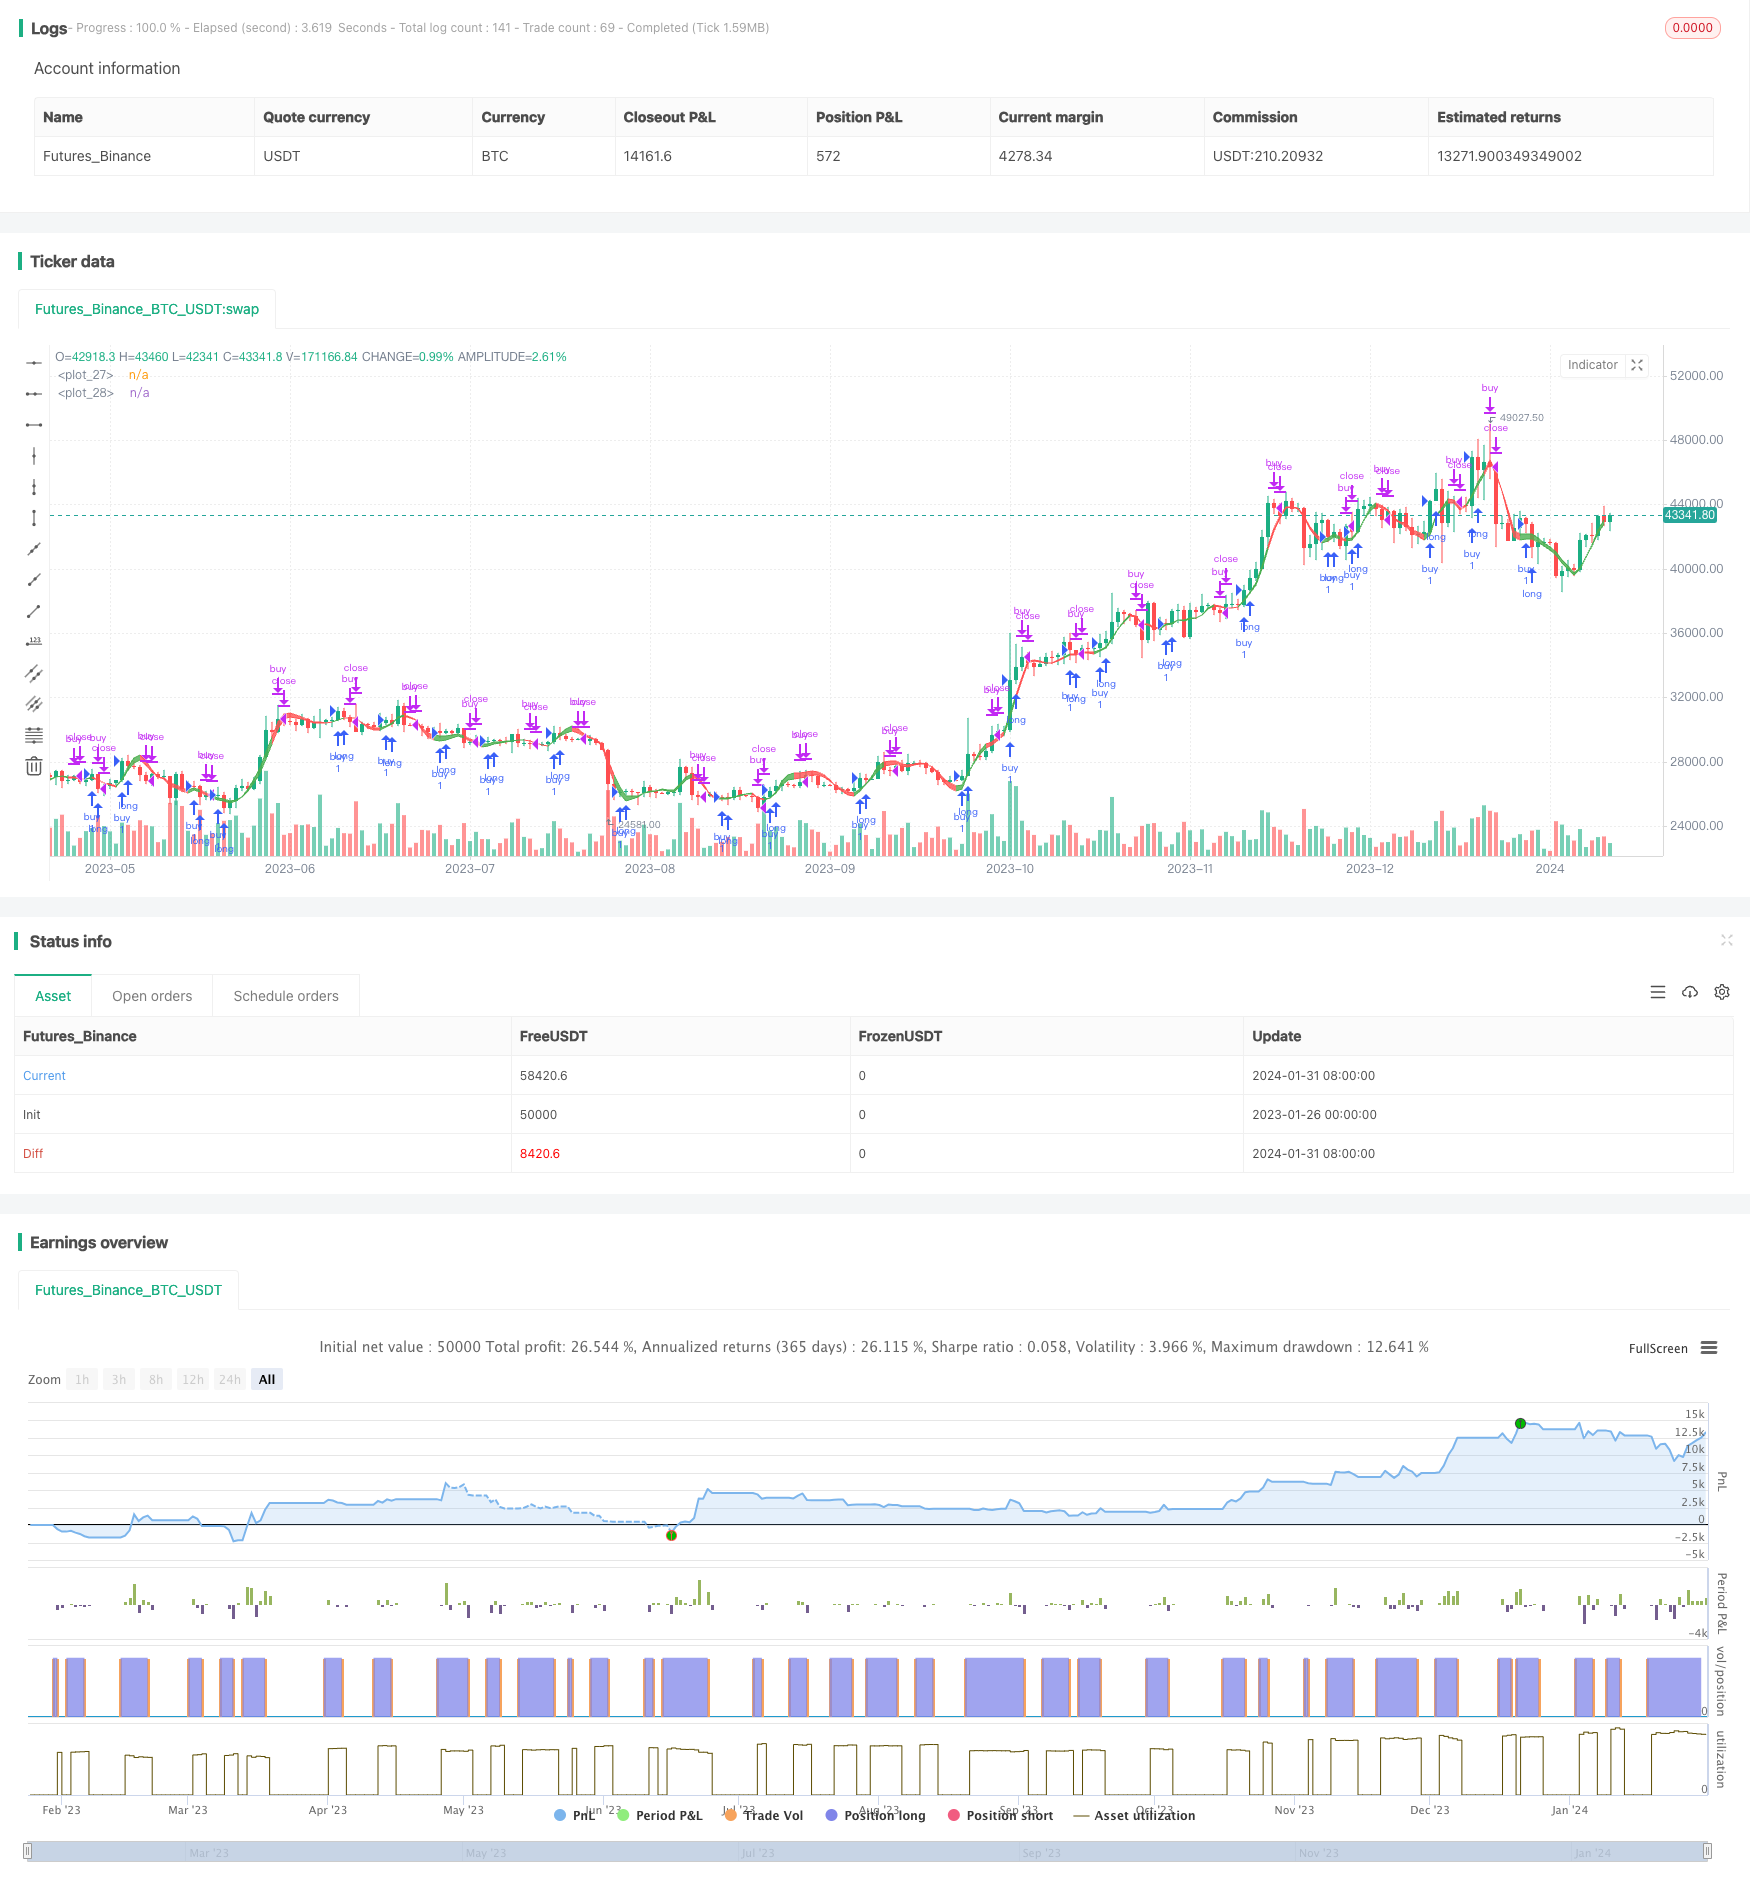
Overview
The Trend Prediction Dual Moving Average Strategy is a strategy that tries to predict trend changes before the actual break from one trend to another. It extends LazyBear's WaveTrend indicator. The strategy can identify price trends and display buy and sell signals through curve filling visual effects.
Strategy Principle
The strategy uses LazyBear's WaveTrend indicator as the basis. WaveTrend itself is an excellent trend tracking indicator. The strategy extends and optimizes on this basis. The main steps are as follows:
- Calculate average HLC price
- Calculate EMA average price
- Calculate EMA of absolute deviation of price
- Calculate zero-leveled adjusted indicator
- Calculate EMA of trend
- Calculate fast and slow moving averages
Through such processing, random price fluctuations can be filtered out and relatively clear trends can be identified. The cross of fast and slow moving averages can be used to issue buy and sell signals.
Advantage Analysis
The strategy has the following advantages:
- Can effectively identify price trends
- Timely signal generation, can predict trend reversals in advance
- Clearly visualize trends through curve filling
- Large parameter optimization space that can be adjusted according to different varieties and cycles
Risk Analysis
The strategy also has some risks:
- Like all technical indicator strategies, there is a risk of failure in case of extreme price volatility
- Improper parameter settings may cause false signals
- Signal lag may result in losses
These risks can be mitigated through methods like adjusting parameters, combining other indicators, etc.
Optimization Directions
The strategy can be optimized in the following aspects:
- Adjust parameters to suit more varieties and cycles
- Increase stop loss strategy to control loss risk
- Combine with other indicators to improve signal accuracy
- Increase machine learning models to assist in judging trends and issuing signals
Summary
Overall, the Trend Prediction Dual Moving Average Strategy is a very promising strategy. It can effectively identify price trends and try to predict trend changes in advance. With some optimization and improvement, the strategy can become a powerful quantitative trading system. Its simple and straightforward trading logic and clear visual effects also make it a strategy worth learning and researching.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Channel Length |
| v_input_2 | 21 | Average Length |
| v_input_3 | 4 | WTFactor |
Source Pine Script
/*backtest
start: 2023-01-26 00:00:00
end: 2024-02-01 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("BreakingDawn [JackTz]", overlay = true)

// WaveTrend [LazyBear]
// ░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░░

n1 = input(10, "Channel Length")
n2 = input(21, "Average Length")

WTfactor = input(4, title=" WTFactor")
averageHlc3 = sum(hlc3, WTfactor) / WTfactor
ap = averageHlc3
esa = ema(ap, n1)
d = ema(abs(ap - esa), n1)
ci = (ap - esa) / (0.015 * d)
tci = ema(ci, n2)
wt1 = tci
wt2 = sma(wt1,4)
wtAvg = wt1-wt2
wtPeriodAvgVal = wtAvg * 45 + averageHlc3
wtPeriodAvg2Val = wtAvg * 25 + averageHlc3

buy = wtAvg[1] < wtAvg and wtAvg < close
sell = wtAvg[1] > wtAvg

fillColor = buy ? color.green : color.red
control = plot(wtPeriodAvgVal, color = fillColor)
signal = plot(wtPeriodAvg2Val, color = fillColor)
fill(signal, control, color = fillColor)

if year > 2016
    strategy.entry("buy", strategy.long, when = buy)
    strategy.close("buy",when = sell)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Trend-Prediction-Dual-Moving-Average-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d